
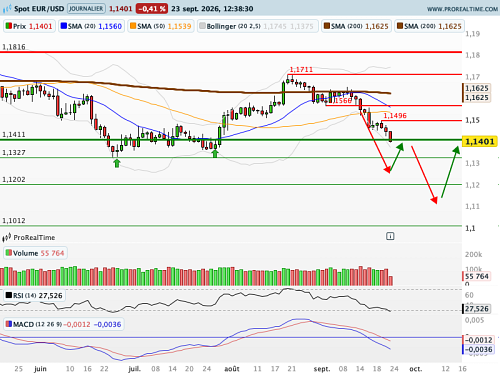
The EUR/USD currency pair trades near 1.1376, down 0.05%, pressured by a complex matrix of geopolitical friction, monetary divergence between the Federal Reserve and the European Central Bank, and widening fiscal deficits across Eurozone member states as global markets navigate late-September 2026 volatility.
The Bottom Line
- Monetary Divergence: Persistent structural inflation differentials continue to test the policy limits of the European Central Bank relative to North American counterparts.
- Fiscal Strain: Sluggish aggregate demand and rising debt-to-GDP ratios across core continental economies undermine institutional confidence in the single currency.
- Geopolitical Friction: Ongoing trade restrictions and energy security premiums impose continuous drag on Eurozone industrial output.
Unpacking the Macroeconomic Matrix Weighing on the Single Currency
Foreign exchange markets have steadily repriced the euro as structural vulnerabilities come to the forefront. At the close of Q3 2026, the EUR/USD pair hovers at 1.1376, reflecting a modest intraday decline of 0.05% in early trading. Here is the math: persistent energy cost differentials and subdued productivity growth across the continent have systematically eroded the eurozone’s traditional current account surplus advantages.
Institutional desks note that capital flows are increasingly favoring dollar-denominated assets. This shift is driven by higher real yields in the United States and a defensive posture among global asset managers. But the balance sheet tells a different story regarding Europe’s structural resilience. While export-driven economies like Germany grapple with sluggish manufacturing orders, the broader fiscal framework remains constrained by strict debt rules that limit aggressive public stimulus.
Monetary Policy Asymmetry and Yield Spreads
The divergence in central bank reaction functions remains a primary driver of foreign exchange dynamics. According to recent analysis by Reuters, the European Central Bank faces mounting pressure to maintain accommodative monetary settings to support fragile sovereign debt markets, even as core inflation proves sticky.
Conversely, the Federal Reserve retains greater flexibility to manage domestic economic momentum without inducing acute balance-of-payments crises. This divergence in policy intent widens the yield differential between German Bunds and U.S. Treasuries, driving institutional capital away from euro-denominated fixed income. Currency strategists point out that until European productivity metrics align with global competitors, the single currency will struggle to sustain upward momentum against the greenback.
| Metric / Indicator | Current Level (Q3 2026) | Quarterly Trend |
|---|---|---|
| EUR/USD Spot Rate | 1.1376 | -0.05% |
| U.S.–Eurozone Yield Spread | Widening | Dollar Positive |
| Eurozone Manufacturing PMI | Contraction Zone | Persistent Drag |
Supply Chain Fractures and Corporate Impact
Multinational corporations operating across the currency corridor are actively hedging against heightened volatility. Supply chain realignments, catalyzed by regulatory shifts and trade fragmentation, have increased input costs for eurozone manufacturers. According to reporting from the Wall Street Journal, industrial firms are shortening supply chains and relocating production facilities to mitigate exposure to currency fluctuations and geopolitical flashpoints.
Corporate treasurers are forced to deploy complex derivative strategies to protect profit margins against erratic swings in exchange rates. As energy markets adjust to ongoing structural supply realignments, European industrial competitiveness remains inextricably linked to the trajectory of the euro. Markets will monitor incoming employment and retail sales data closely for any sign of shifting momentum as the fourth quarter approaches.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute financial advice.
