
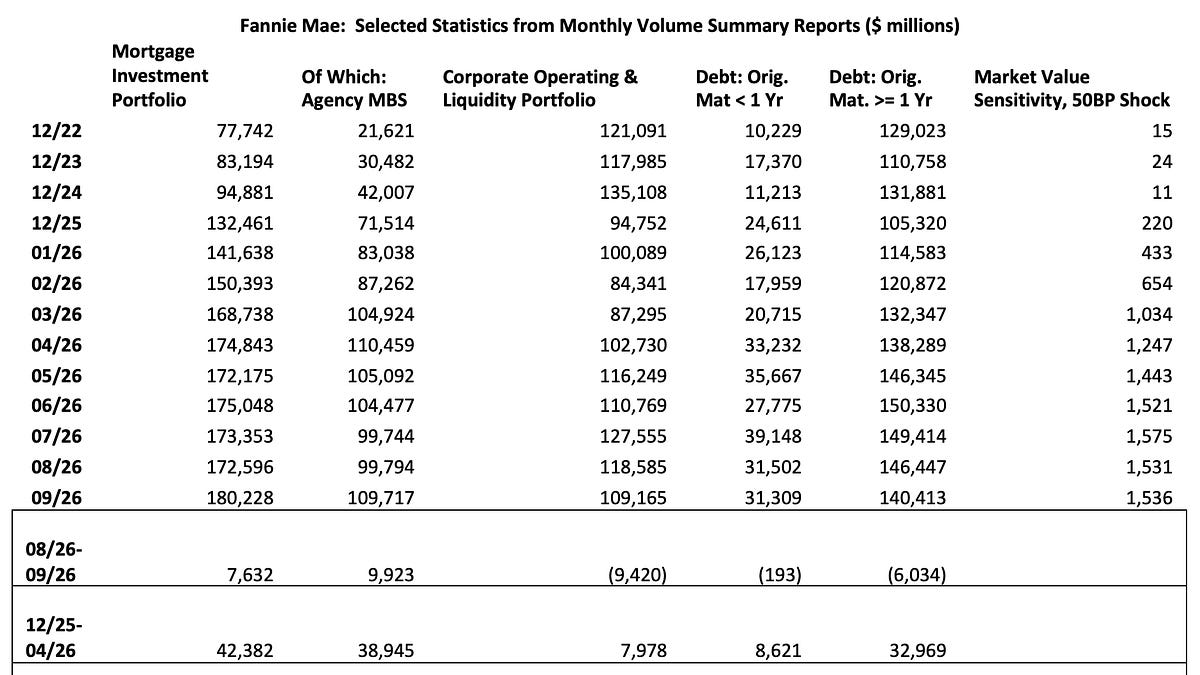
Federal housing enterprises Fannie Mae and Freddie Mac expanded their Agency mortgage-backed securities portfolios in September, adding $9.923 billion and $1.785 billion respectively, according to monthly volume summaries released by the government-sponsored enterprises.
September Portfolio Adjustments Across the GSEs
- Combined Agency MBS holdings experienced their largest monthly expansion since March, though totals at month-end were little changed from April.
- Fannie Mae’s total mortgage investment portfolio rose by $7.623 billion, while Freddie Mac’s portfolio declined by $3.012 billion.
- Year-to-date additions reached a combined $50.663 billion, tracking below earlier implied policy targets.
Portfolio Shifts and Federal Housing Finance Agency Context
The September expansion follows a period of contraction that drew market scrutiny. Fannie Mae’s holdings grew by $38.203 billion from the end of last year, while Freddie Mac posted a $12.46 billion increase over the same timeframe. Despite the recent purchases, the combined $50.663 billion year-to-date growth trails the $200 billion in GSE MBS purchases implied by a post from Trump on January 8.
The recent downward trajectory in holdings over the summer months caught analysts off guard. In response to reports detailing the contraction between April and August, Federal Housing Finance Agency Director Bill Pulte stated on September 18 that the enterprises were beginning to acquire larger quantities of mortgage-backed securities. Housing economist Tom Lawler noted that while new purchasing commitments made in late September would likely settle in October or later, and as such would not show up on the GSEs September monthly volume summaries, the latest data indicates acquisition pacing had already accelerated prior to Pulte’s announcement.
| Metric | Fannie Mae (September Change) | Freddie Mac (September Change) |
|---|---|---|
| Agency MBS Holdings | +$9.923 billion | +$1.785 billion |
| Total Mortgage Investment Portfolio | +$7.623 billion | -$3.012 billion |
| Year-to-Date MBS Increase | +$38.203 billion | +$12.460 billion |
| Debt Outstanding (YTD) | +$41.971 billion | -$38.964 billion |
Interest-Rate Risk and Yield Movements in Fixed-Income Markets
Market-value sensitivity to a 50 bp upward shock in interest rates remained largely unchanged for both enterprises, hovering near historically elevated levels. Meanwhile, current-coupon MBS yields dropped significantly alongside intermediate and long-term Treasury yields. This downward yield movement accelerated immediately following September consumer price index and producer price index releases that ran somewhat hotter than anticipated.
A notable correlation between interest rates and oil prices observed over the summer dissolved in October, replaced by a tight correlation with Tech stocks. Analysts interpreted this shift as investors rotating out of Tech stocks and into bonds. Current-coupon MBS yields fell by 34 basis points from the end of September through October, reversing half of the 68 basis point surge recorded between August and September.
Municipal Bond Market Recovery and Relative Spreads
Current-coupon MBS versus Treasury spreads edged higher over the month following a wider expansion in September, though spreads finished October below their October 16 peak. Elevated implied interest-rate volatility continued to underpin the wider spreads observed since August. Concurrently, the municipal bond market stabilized in October after sharp absolute and relative underperformance in September.
During September, municipal markets absorbed heavy retail selling driven by investors harvesting losses to offset capital gains elsewhere. AAA municipal bond yields surged, and increased significantly more than Treasury yields. As taxable market yields drifted downward in the latter half of October, municipal yields fell by margins exceeding Treasuries, compressing ratios down from their September highs while remaining elevated relative to earlier in the year.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute financial advice.
