
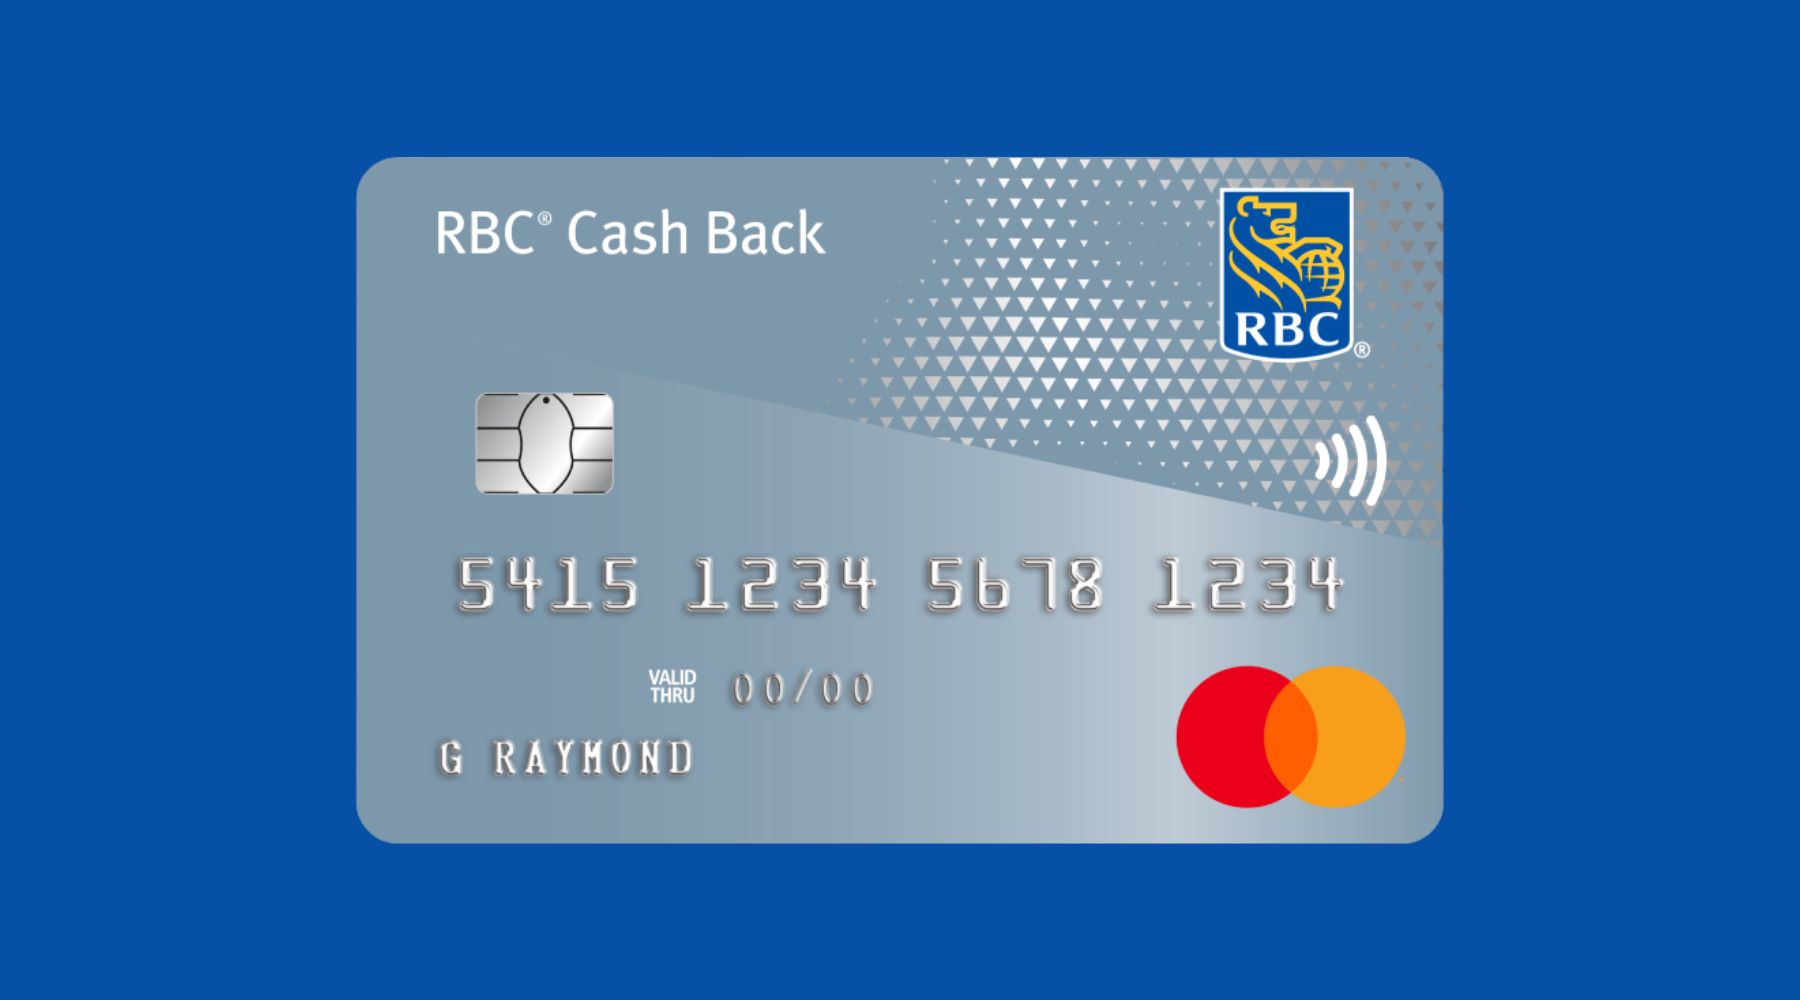
The Royal Bank of Canada (NYSE: RY) offers the RBC Cash Back Mastercard as an entry-level, no-fee credit card designed for everyday consumers seeking straightforward rewards.
The Bottom Line
- Zero Annual Fee: The card carries a $0 annual fee for both primary and additional cardholders, reducing upfront overhead costs for budget-conscious consumers.
- Tiered Earning Limits: Grocery rewards of 2% apply only to the first $6,000 spent annually, dropping to 1% thereafter, while all other purchases earn up to 1%.
- Partner Ecosystem Perks: Cardholders receive fuel discounts and bonus points when linking their accounts to Petro-Canada and Rexall, plus promotional DoorDash subscription offers.
Evaluating the Rewards Structure and Spending Caps
Marketed primarily as a low-barrier financial product, the RBC Cash Back Mastercard targets individuals avoiding the typical $99 to $120 annual fees attached to premium credit options. According to Savvy New Canadians, cardholders earn 2% cash back on grocery store purchases up to a maximum threshold of $6,000 per year. Exceeding this $6,000 limit shifts the grocery reward tier down to 1% for the remainder of the annual cycle.
Beyond groceries, the card offers up to 1% unlimited cash back on all other qualifying purchases and pre-authorized bill payments. However, Finder notes that the baseline tier for general spending starts at 0.50% on the first $6,000 before escalating to 1%. Furthermore, cash back rewards are not credited instantly; cardholders must reach a $25 redemption threshold before funds hit their accounts.
Fee Schedules and Interest Rates
For consumers evaluating revolving debt, understanding the underlying interest rates is essential. The RBC Cash Back Mastercard charges a purchase interest rate of 20.99%, while cash advances carry a 22.99% rate, which adjusts slightly to 21.99% for residents of Quebec, as reported by Finder data.
Unlike premium travel or rewards cards, the basic package excludes built-in travel medical insurance or roadside assistance. Cardholders seeking these protections must pay extra fees to add optional features like balance protection insurance, identity protection, or road assistance directly onto their accounts.
Comparative Analysis: RBC Versus Competitor Offerings
When stacked against alternative no-fee products in the Canadian market, structural differences emerge. For instance, the Tangerine Money-Back Credit Card provides an alternative model by offering 2% unlimited cash back across up to three self-selected spending categories—such as gas, groceries, or recurring bills—with monthly payouts rather than annual redemptions.
| Credit Card | Annual Fee | Grocery / Category Reward Rate | Base Reward Rate |
|---|---|---|---|
| RBC Cash Back Mastercard | $0 | 2% (up to $6,000/year spend) | Up to 1% (0.50% on first $6,000) |
| Tangerine Money-Back Credit Card | $0 | 2% unlimited (in up to 3 chosen categories) | 0.50% on all other purchases |
Partnership Perks and Ancillary Benefits
To enhance consumer value without altering base earn rates, RBC integrates several retail partnership benefits into the cardholder agreement. Finder notes additional integrations, including 50 Be Well points per $1 spent at Rexall and a complimentary six-month DashPass subscription through DoorDash, offering $0 delivery fees on qualifying orders.
Security features remain standard across the product tier. Purchase Security and Extended Warranty Insurance covers eligible items against loss, theft, or damage for up to 90 days, while doubling the manufacturer’s original Canadian warranty for an additional year.
Market Positioning and Consumer Eligibility
Securing the card requires meeting baseline eligibility criteria established by the financial institution. Applicants must hold Canadian citizenship or permanent residency, reach the age of majority in their respective province or territory, and provide standard identification documentation alongside a valid Social Insurance Number.
While the card’s earn rates may trail behind specialized high-tier competitors, its zero-fee structure and straightforward grocery rewards position it as a functional entry-level option for households managing predictable, everyday domestic expenses.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute financial advice.
