
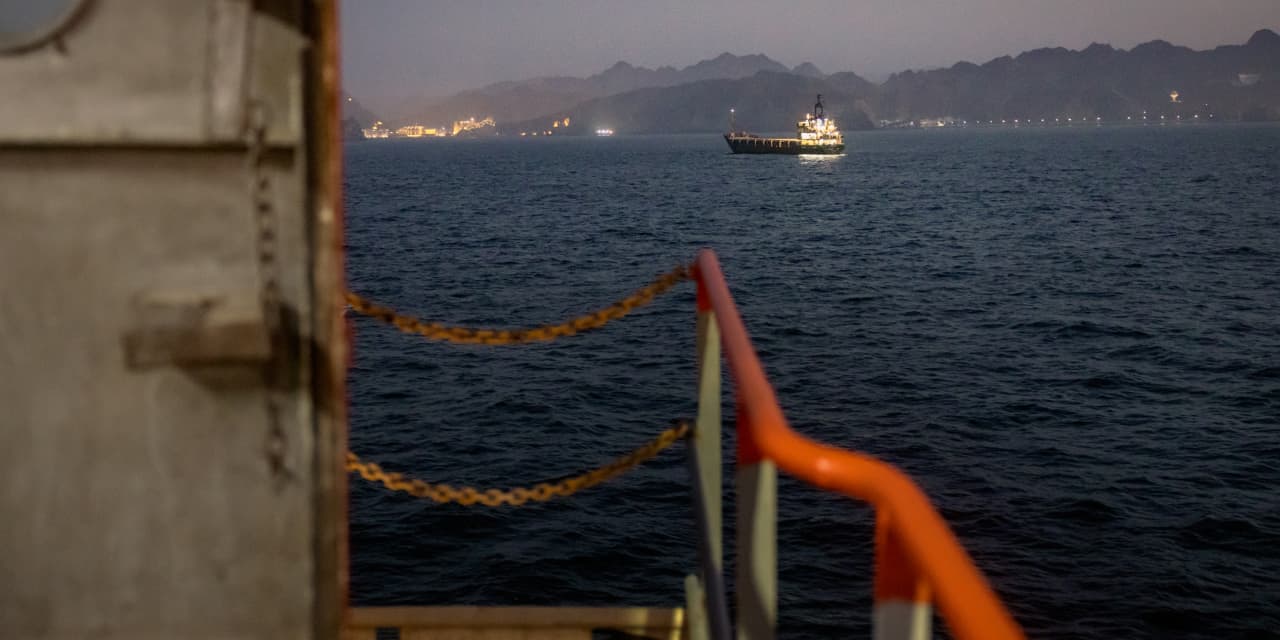
Saudi Arabia is heavily increasing its maritime oil exports through the Strait of Hormuz following an attack on its domestic East-West pipeline. According to market reports from September 2026, the kingdom and neighboring Persian Gulf exporters are relying on this vital chokepoint to maintain crude flows to global markets, primarily Asia, despite ongoing geopolitical risks and maritime security hurdles.
The Bottom Line
- Infrastructure Vulnerability: Drone attacks by Iran-backed militias in Iraq severely damaged the 750-mile East-West pipeline, forcing a temporary shutdown and shifting export reliance back to maritime routes.
- Throughput Realities: Industry estimates indicate between 8 million and 10 million barrels of crude and products move daily through the Strait of Hormuz, with recent U.S. Navy escorts helping facilitate higher transit volumes.
- Market Implications: Physical supply tightness keeps refining margins volatile and retail fuel prices elevated globally, insulating tanker operators while posing sustained cost pressures for downstream consumers.
Pipeline Disruptions Force a Critical Maritime Pivot
The geopolitical risk profile for Middle Eastern energy logistics shifted abruptly following coordinated drone strikes on Saudi Arabia’s primary inland corridor. According to reports from MarketWatch and Morningstar, the 750-mile East-West pipeline—spanning a distance roughly equivalent to the drive between New York City and Indianapolis—suffered critical structural damage after attacks by Iran-backed militias in Iraq. Before the shutdown, the pipeline possessed a nominal capacity of up to 7 million barrels per day, serving both domestic refiners and providing an overland bypass around regional flashpoints.
With that vital artery offline, state producer Saudi Arabian Oil Co. (Aramco) [Ticker: 2222.SR] has been forced to redirect export volumes toward maritime channels. While some market participants anticipate partial repairs returning the pipeline to 50% capacity within days, the infrastructure now sits squarely within an active zone of vulnerability. That reality has thrust the Strait of Hormuz back into the spotlight as the primary conduit for maintaining the kingdom’s contractual obligations and daily output quotas.
| Export Channel | Nominal / Estimated Capacity | Current Operational Status |
|---|---|---|
| East-West Pipeline | 3M to 4M barrels/day (utilization prior to shutdown) | Temporarily shut down for repairs following drone strikes |
| Strait of Hormuz (Total Flow) | 18M to 20M barrels/day (historical/current tracked volume) | Active, supported by naval escorts and “dark” transit adjustments |
| Strait of Hormuz (Saudi Share) | 8M to 10M barrels/day (estimated daily average) | Experiencing increased tanker traffic and heightened security protocols |
Navigating the Volatile Chokepoint of Hormuz
Quantifying precise export volumes moving through the Strait of Hormuz remains a complex logistical challenge for analysts and shipping firms. According to Robin Mills, CEO of Qamar Energy, moving an average of 8 million to 10 million barrels a day of crude and products through the strait represents the current baseline. This figure sits below the pre-war benchmark where approximately 20 million barrels traversed the waterway, the vast majority bound for Asian destination ports.
Energy Secretary Chris Wright noted in media statements that U.S. Navy escorts have recently helped facilitate outbound flows reaching roughly 18 million barrels per day across all regional exporters. However, tracking accuracy is consistently hindered by “dark” crossings—instances where vessels disable their GPS-like transponder signals to evade potential hostile interference from Iranian forces. As Mills observed, “It’s all very cloudy, but a reasonable average to me is something between 8 million barrels a day to 10 million barrels a day getting through the strait.”
This heavy reliance on maritime transport directly impacts shipping dynamics for global operators. Increased vessel density in a contested corridor naturally raises freight rates for Very Large Crude Carriers (VLCCs) and Suezmax tankers. Major integrated energy corporations such as ExxonMobil Corporation (NYSE: XOM) and Shell plc (NYSE: SHEL) continue to monitor these transit friction points closely as regional price parity shifts alongside the elevated geopolitical risk premium.
Refining Bottlenecks and Sustained Price Pressures
Despite the successful resumption of heavy tanker traffic through the Persian Gulf, the broader macroeconomic impact on refined products remains acute. Industry experts emphasize that increased crude throughput via Hormuz exerts only a marginal downward effect on retail fuel inventories, as global refining capacity serves as the ultimate bottleneck.
According to data from AAA cited by Morningstar, U.S. national retail averages for regular gasoline climbed to $4.43 per gallon, marking a notable departure from seasonal post-Labor Day downward trends. Meanwhile, the U.S. average retail diesel price touched an all-time high of $6.40 per gallon. These elevated input costs underscore how physical market tightness continues to buffet consumers, ensuring that energy inflation remains a persistent challenge for industrial supply chains worldwide.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute financial advice.
