
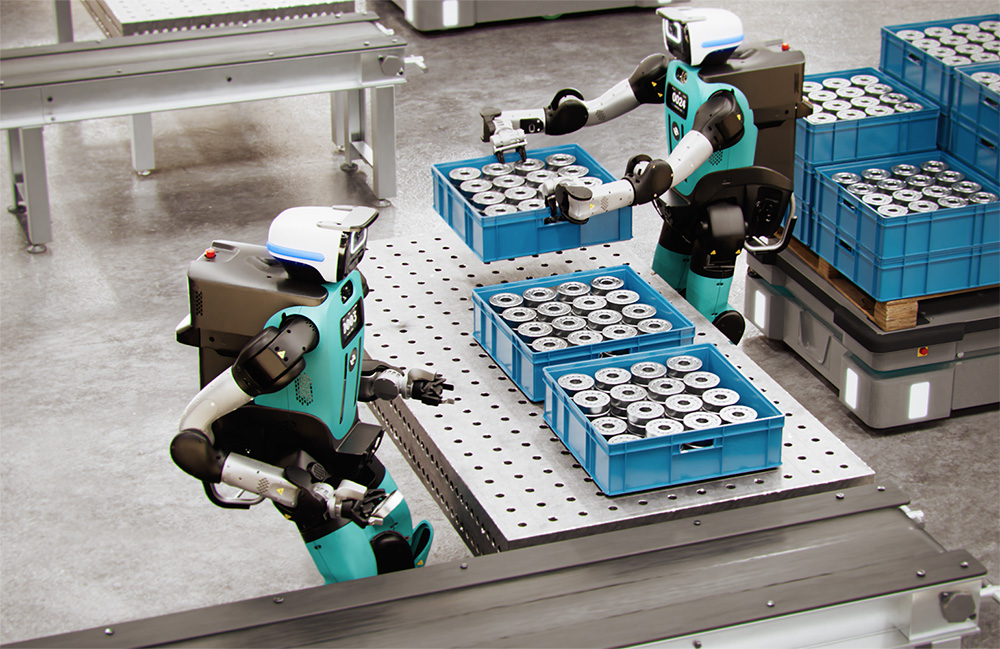
Agility Robotics officially entered the public markets this morning, November 5, 2026, debuting on the Nasdaq under the ticker “AGLT.” The Salem, Oregon-based firm completed its merger with Churchill Capital Corp XI, opening at $11.26 per share. This listing marks the first time a pure-play legged humanoid robotics company has gone public.
Churchill XI Shareholders Approve Public Transition
The transition to a public entity follows a definitive approval from Churchill XI shareholders on November 2, where over 84% of votes favored the merger, according to The Robot Report. The transaction, which finalized on November 4, provides Agility with approximately $465 million in gross proceeds. This funding structure includes $164 million from the Churchill XI trust account, a $201 million private investment in public equity (PIPE) led by Foxconn, and a $100 million round secured post-announcement.
While the company enters the market with momentum, the financial reality remains in a heavy investment phase. Agility reported $1.78 million in revenue for 2025 against a net loss of $138.1 million. With $103 million in cash reserves at the close of 2025, the new capital is earmarked to scale production and support the rollout of the next-generation Digit 5. Per Unite.AI, existing shareholders and the Churchill sponsor remain bound by a 180-day lock-up period, though early release clauses tied to stock performance metrics persist.
The Operational Reality of Digit
Unlike many humanoid startups currently trapped in the “tech demo” phase, Agility has focused on tangible logistics deployments. The company’s flagship robot, Digit, has already logged over 65,000 hours of operation across nine customer facilities, including deployments with GXO Logistics, AGCO, and Toyota Motor Manufacturing Canada. These machines are primarily tasked with repetitive, physically demanding tote-moving operations.
The path forward rests on the conversion of $300 million in committed multiyear orders for the Digit 5 into actual revenue. Agility has established “RoboFab,” a manufacturing facility designed for an annual output of 10,000 units, and utilizes its “Agility Arc” cloud platform to manage fleet orchestration. These components are critical for transitioning from pilot programs to high-density industrial adoption.
Agility Explores Wheeled-Base Robots for Consumer Domains
The company is already signaling that the bipedal form factor may not be its only hardware play. The Robot Report noted that Agility is exploring wheeled-base robots to address consumer-facing domains where bipedal locomotion might be inefficient. While co-founder Jonathan Hurst clarified in a recent social media engagement that Digit itself will likely remain legged, the company’s roadmap explicitly includes a broader family of human-centric, multipurpose machines.
CEO Peggy Johnson has suggested a pivot toward licensing Agility’s intellectual property. By positioning itself as a technology supplier, the company aims to serve as the “backbone” of the broader humanoid industry.
Agility Faces Challenge of 2027 Delivery Targets
The following table outlines the current financial and operational trajectory as reported by the company:
| Metric | Status/Value |
|---|---|
| 2025 Revenue | $1.78 Million |
| 2025 Net Loss | $138.1 Million |
| Committed Digit 5 Orders | >$300 Million |
| Operational History | 65,000+ Hours |
The immediate challenge for Agility is the execution of its 2027 delivery targets. With early-access deliveries for the Digit 5 slated for the first half of 2027 and general availability targeted for the end of that year, the company must prove it can scale manufacturing without sacrificing the safety standards that have become its hallmark. As The Robot Report noted, the industry is watching closely to see if Agility can maintain its position as the only U.S. publicly listed pure-play humanoid robotics company with active commercial deployments.
The core question remaining is whether the market will value Agility as a software-driven robotics platform or a hardware-heavy manufacturer. While the $300 million in orders provides a strong signal of industrial intent, the gap between committed orders and realized revenue remains the primary hurdle for long-term valuation.
