
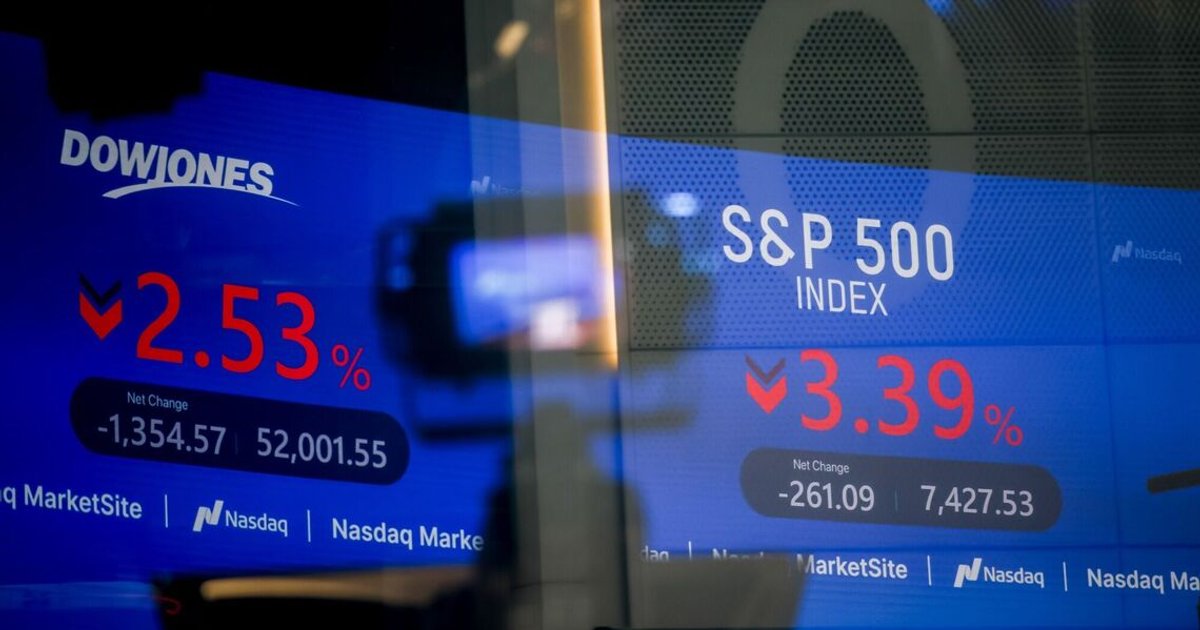
US technology stocks faced a massive correction following the US midterms, erasing US$2.5 trillion in market value as the Nasdaq 100 fell 6.4% on November 5. This volatility has spread to Asian markets and Singapore-listed tech stocks, leaving investors to weigh whether to capitalize on lower valuations or reduce exposure amid rising regulatory scrutiny of artificial intelligence.
The sell-off, reported by The Straits Times, was triggered by a Democratic sweep of Congress, which heightened concerns regarding tighter oversight of AI infrastructure, including electricity and water usage, grid costs, and data centre permits. This political shift coincides with investor skepticism over the timeline for converting massive capital expenditures in chips and data centres into tangible corporate profits.
Strategic Takeaways for AI Exposure
- Regulatory Risk: A Democratic-led Congress may introduce stricter rules on data centre construction and resource consumption, potentially delaying infrastructure projects.
- Valuation Reset: The correction represents a “reset” in a highly crowded trade, where market sentiment and leverage have amplified the downward price movement.
- Sector Divergence: While cloud giants with strong balance sheets may remain resilient, smaller AI providers reliant on debt face higher risks from potential project delays.
Market Volatility Spreads from US to Asia
The contagion from the US markets moved rapidly into the semiconductor-heavy indices of South Korea, Taiwan, and Japan on November 6. In the United States, the S&P 500 fell 4.4%, while the Philadelphia Semiconductor Index experienced a more severe decline of 12.2%.
Industry analysts suggest that the magnitude of the fall was exacerbated by crowded AI positions and the use of borrowed money to speculate on the sector. As investors rushed for an exit, the combination of genuine uncertainty and amplified selling pressure drove prices down. However, Saxo chief investment strategist Charu Chanana noted on November 6 that the sell-off appears to reflect changing sentiment and valuation assessments rather than an immediate collapse in business fundamentals.
Diverging Outlooks for Cloud Giants and Chipmakers
The impact of potential regulatory delays creates a complex landscape for different segments of the AI value chain. According to Afdhal Rahman, executive director of wealth advisory at OCBC, major cloud providers such as Microsoft, Alphabet, and Amazon are relatively well positioned in the near term.
If tighter regulations delay data centre construction, these cloud giants could experience relief from heavy capital spending, leaving them with more available cash. Conversely, this reduction in spending could lead to fewer orders for chipmakers, storage suppliers, and equipment manufacturers. While the immediate outlook for hardware may be volatile, major cloud providers have indicated they expect to increase spending in 2027, suggesting long-term demand for computing power remains intact.
Investors Manage Risk Through Liquidity and Sector Selection
For investors looking to manage exposure, the strategy depends heavily on liquidity and time horizons. Charu Chanana suggests that long-term investors who can tolerate further volatility may continue regular investing, provided their holdings align with their risk profiles. For those attempting to “buy the dip,” a focus on companies with strong balance sheets, steady cash flow, and reasonable valuations is recommended.
Afdhal Rahman identifies specific areas of interest and caution within the sector. He expresses a preference for graphics processors, custom chips, and networking equipment, while maintaining a more cautious stance on memory stocks, where current prices may already incorporate expected growth. In the software segment, companies with proprietary data or deep ties to leading AI labs are viewed as better positioned to defend their market share.
The risks are most pronounced for smaller AI cloud providers. Because these entities often rely heavily on debt, any delay in securing permits for data centres could force them to service interest costs for longer periods before generating revenue. Investors trading on margin are advised to calculate their potential downside to avoid forced liquidations.
The Path Toward 2027 Infrastructure Spending
While the immediate market reaction is driven by political and sentiment-based shifts, the underlying technological demand shows signs of long-term persistence. The core question for the coming months is whether the Democratic Congress’ focus on resource management—specifically electricity and water use—will result in legislative hurdles that materially alter the growth trajectory of AI infrastructure.
The next critical indicators will be the earnings forecasts from major chipmakers and any adjustments to capital expenditure guidance from the world’s largest cloud service providers. Despite the current rout, the fundamental requirement for computing power and the technological opportunities presented by AI have not disappeared; rather, the market is recalibrating the price it is willing to pay for that future growth.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute financial advice.
