

Baltic equities displayed divergent momentum at the close of Q2, with the Vilnius stock exchange advancing with a strong increase while regional net profits declined year-over-year. Despite higher operational costs eroding corporate margins, institutional analysts highlight that targeted share price targets continue to indicate substantial valuation upside across select sectors.
The Bottom Line
- Margin Compression: Aggregate sales among tracked firms rose well, but median net income dropped as rising costs caught up with top-line growth.
- Lithuanian Outperformance: The OMX Baltic Benchmark GI index climbed 3.4% overall, anchored by Viļņa’s strong quarterly advance, outpacing Tallinn (+2.4%) and Riga (+3.1%).
- Valuation Disconnect: Strong operational quarters do not automatically translate to “buy” ratings; analysts emphasize that higher risk profiles and inflation pressures require selective stock picking.
Regional Market Dynamics and the Cost Pressures Squeezing Net Margins
When markets opened following the conclusion of the second quarter, analysts at Swedbank and Enlight Research parsed financial statements from 14 major Baltic equities. Here is the math: while median sales revenue grew by a healthy rate year-over-year, median net income fell. Simultaneously, the trailing 12-month return on equity (ROE) compressed to approximately 9%.
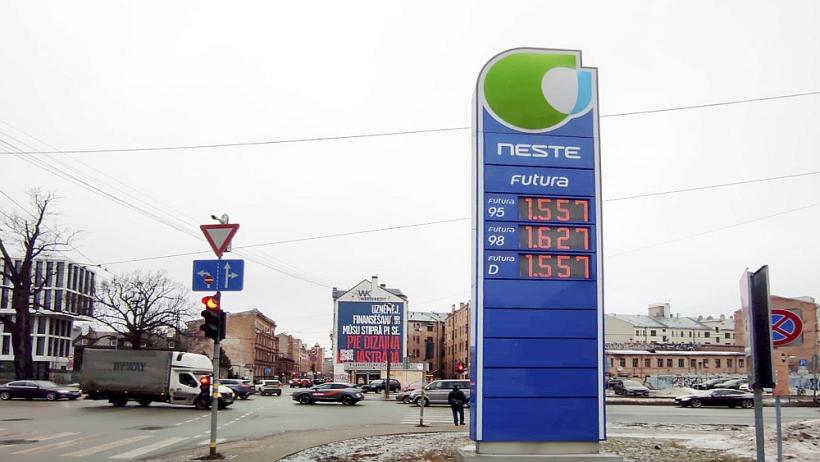
The macroeconomic backdrop explains the squeeze. According to European Commission data, regional fuel costs escalated, with diesel prices in Latvia increasing by 15.8% last week.
“A good company and a good investment are not the same thing,” noted Avaron analyst Silver Schmeiman during a recent market review. Evaluating any regional asset requires balancing raw earnings growth against equity risk premiums and shifting capital costs.
Banking Sector Divergence: Coop Pank Outpaces LHV
In the Estonian banking sector, Coop Pank demonstrated robust balance sheet expansion. The bank posted a net profit of 8.2 million euros, representing a 24% increase compared to the prior-year period. Net income climbed 14% to 22.3 million euros, while operating expenses increased 10% to 11.1 million euros.
Coop Pank expanded its loan portfolio by 15% YoY to reach 2.23 billion euros. Asset quality improved concurrently, with non-performing loans dropping from 2.8% to 2.1%. Return on equity reached 13.5%.
Conversely, LHV Group reported a Q2 net profit of 24.7 million euros. While this marked a 25% recovery over Q1, it remained 20% lower year-over-year. LHV faced headwinds from 5.8 million euros in loan impairment provisions and an 8% rise in operating expenses. Nevertheless, the group’s total loan portfolio expanded 15% to 5.77 billion euros, bolstered by its UK subsidiary, LHV Bank, which saw its lending portfolio surge 66% toward the one-billion-euro threshold.
Construction and Real Estate Rebalancing: Merko and EfTEN
In the construction segment, Merko Ehitus booked second-quarter revenue of 92.7 million euros, up 12% YoY, lifting its secured order book to a record 836 million euros. However, EBITDA declined due to persistent inflation in building materials and equipment, down to 8.1 million euros.
Despite this margin pressure, Swedbank adjusted its price target upward, factoring in major regional infrastructure developments such as the Rūdiņķi military camp in Lithuania. The key operational question remains conversion speed: how efficiently Merko can push its record backlog through to the bottom line.
| Company | Sector | Q2 Revenue / Metric | YoY Change / Trend |
|---|---|---|---|
| Coop Pank | Banking | 8.2M EUR (Net Profit) | +24% YoY |
| LHV Group | Banking | 24.7M EUR (Net Profit) | -20% YoY |
| Merko Ehitus | Construction | 92.7M EUR (Revenue) | +12% YoY |
| Eleving Group | Financial Services | 87M EUR (Revenue) | +10% vs. Forecast |
Meanwhile, alternative asset managers actively restructured portfolios. EfTEN Real Estate Fund capitalized on asset rotation by divesting its DSV logistics hub in Riga and the Menulio office asset in Vilnius, simultaneously acquiring the Magistrali shopping center in Tallinn. The transactions lift annualized rental income for the newly acquired hub, offsetting temporary vacancies during the transitional quarter.
Specialty Lenders and Consumer Credit Growth
Latvian specialty lenders demonstrated aggressive top-line expansion. Eleving Group grew its loan portfolio by 39% to 522 million euros, generating 87 million euros in revenue—outperforming Enlight Research projections by 10%.
Similarly, DelfinGroup expanded its loan book by 18% to 153 million euros. Rigorous cost control and lower credit loss provisions allowed net profit to edge up to 2.9 million euros, maintaining a projected return on equity exceeding 30% alongside high dividend distributions following Indexo’s majority stake acquisition.
The Investment Outlook Ahead
As the market moves deeper into the second half of the year, regional valuations remain tethered to execution risks and energy market volatility. While high-yielding equities in retail and specialty finance offer compelling dividend models, institutional investors continue to price in macroeconomic headwinds tied to input cost inflation and regional security premiums.
Worth a look
