
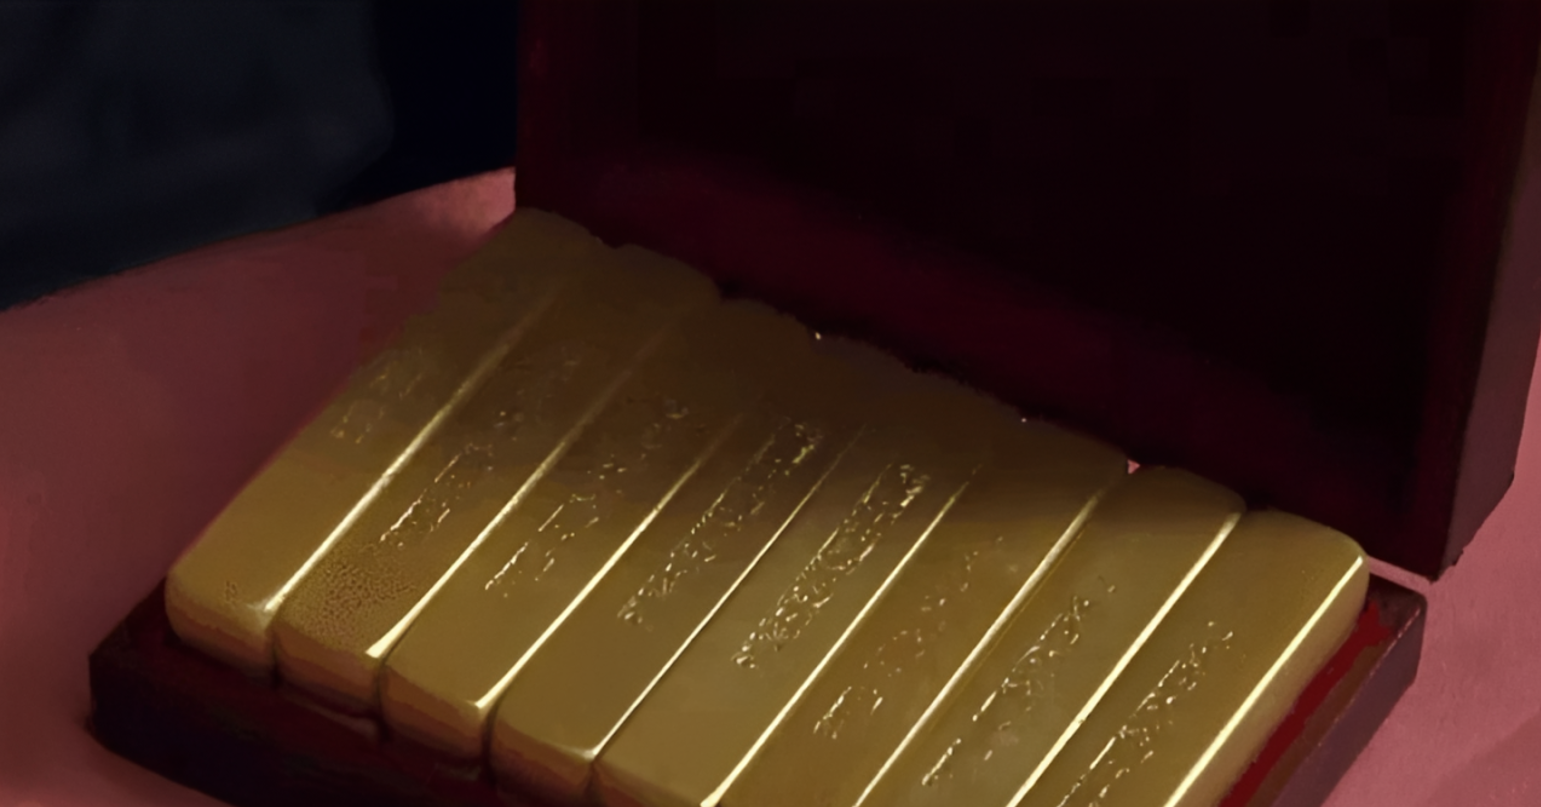
In a volatile macroeconomic climate marked by shifting precious metal valuations, an informal private transaction involving 400 grams of gold bars valued at 140,000 yuan (approximately 546 million VND) executed as a personal loan in Vietnam illustrates the complex intersection of private debt structuring, counterparty risk, and fluctuating commodity pricing.
Here is the math: when underlying asset prices swing unpredictably, informal debt contracts collateralized by physical bullion routinely trigger severe legal and financial friction between private parties.
The Bottom Line
- Asset Volatility: Informal collateral loans backed by physical gold expose lenders to severe opportunity costs when spot prices appreciate rapidly.
- Contractual Ambiguity: Unregistered private lending agreements frequently lack explicit provisions for asset appreciation, leading to disputes over principal repayment versus equity-like returns.
- Macroeconomic Pressures: Retail demand for physical gold as a hedge against currency devaluation continues to strain informal credit arrangements across Southeast Asian markets.
Collateral Structuring and Counterparty Risk in Private Lending
Private lending arrangements backed by physical assets require rigorous legal frameworks to withstand market volatility. When a borrower receives physical gold bars as a loan instrument, the mechanics diverge sharply from standard institutional banking. According to private wealth advisors, unhedged commodity loans create asymmetric risk profiles where the lender absorbs the downside of fiat depreciation while capping their upside.
The transaction involving 400 grams of gold highlights the friction inherent in verbal or loosely drafted agreements. As global bullion markets experience sustained institutional inflows, retail lenders engaging in informal peer-to-peer financing face severe enforcement challenges. Without formal hypothecation agreements registered under commercial law, reclaiming appreciating assets often devolves into protracted civil disputes.
Macroeconomic Hedging and Retail Bullion Demand
Retail participants increasingly turn to physical gold to preserve purchasing power amid persistent inflationary pressures. Central bank accumulation and geopolitical instability have driven spot prices higher, fundamentally altering the economics of legacy private loans. When a borrower secures funds tied to a fixed weight of precious metal rather than a fixed fiat value, the lender effectively sells a call option on the commodity without collecting premium compensation.
Financial analysts note that this phenomenon mirrors broader structural trends in emerging markets. As local currencies fluctuate against reserve assets, private contracts denominated in bullion serve as an alternative monetary system. However, this creates systemic vulnerability for retail lenders who fail to account for compound valuation shifts over the duration of the debt instrument.
| Parameter | Informal Bullion Loan | Institutional Secured Credit |
|---|---|---|
| Collateral Type | Physical Gold Bars | Registered Securities / Real Estate |
| Documentation | Verbal / Simple Written Note | Comprehensive Legal Covenants |
| Interest Mechanism | Variable / Commodity Linked | Secured Overnight Financing Rate (SOFR) Plus Spread |
| Default Recovery | Civil Litigation / Informal Mediation | Standardized Foreclosure / Margin Call |
Valuation Dynamics and the Cost of Informal Agreements
The core vulnerability of asset-backed private credit lies in the divergence between execution value and redemption value. In the reported transaction, 140,000 yuan anchored the initial liability. As market rates reprice the underlying 400 grams of gold, the economic reality of the loan shifts entirely.
Professional economists emphasize that informal lenders frequently overlook opportunity costs. Locking up capital in physical commodities without a structured appreciation clause strips the lender of liquidity and yield potential. Consequently, private market participants must adapt institutional risk management strategies—such as regular mark-to-market valuations and mandatory margin maintenance—to safeguard personal capital against rapid commodity appreciation.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute financial advice.
Related reading
- Foreign Envoys Warn China Rewriting Maritime Rules as US Defends Taiwan Energy Resilience
- New Tropical Storm Forms in Northern Atlantic With No Threat to Land
- Reform UK faces Electoral Commission probe over record £72m funding windfall (time.news)
- Oil Prices Surge & Bitcoin Jumps 4% as Saudi Arabia Halts European Shipments (newsy-today.com)
