
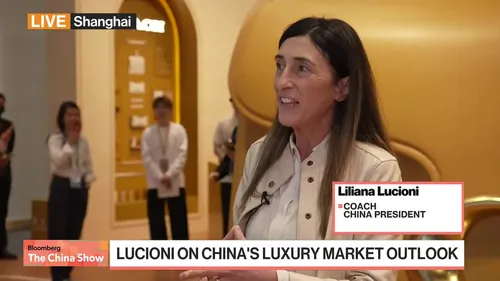
Liliana Lucioni, China President at Coach (NYSE: COCH), signaled a cautious outlook for the luxury sector during the China International Import Expo in Shanghai, citing persistent weakness in domestic consumer spending. Speaking on the sidelines of the event, Lucioni addressed the challenges facing premium brands as Chinese consumers tighten budgets amid broader macroeconomic uncertainty.
The remarks come at a critical juncture for the global luxury market, which has increasingly relied on Chinese demand to offset slowing growth in Western markets. While the luxury sector often shows resilience during economic downturns, the current contraction in discretionary spending in China is testing the premium segment’s ability to maintain margins and volume.
Strategic Implications for Coach China Operations
- Consumer Sentiment Headwinds: Weakened domestic spending is forcing luxury leaders to recalibrate growth expectations for the mainland market.
- Market Positioning: Brands like Coach are navigating a bifurcated market where high-end demand remains, but the aspirational middle class is retreating.
- Macroeconomic Sensitivity: The luxury sector’s performance remains tightly coupled with China’s broader property market and employment stability.
Luxury Demand Faces Pressure from Weakened Chinese Spending
The discussions in Shanghai highlight a disconnect between high-end brand aspirations and the current reality of the Chinese consumer wallet. As reported by Bloomberg, Lucioni's commentary shows a period of transition for the luxury market in the region.
For Tapestry, Inc. (NYSE: TPR), the parent company of Coach, the Chinese market serves as a primary engine for international growth. However, the current environment of subdued consumer confidence suggests that the rapid expansion seen in previous years may face structural resistance. The ability of Coach to capture market share will likely depend on its ability to pivot toward more resilient consumer segments while managing inventory levels in a cooling economy.
But the balance sheet tells a different story regarding the luxury sector’s broader trajectory. While individual brands may face localized headwinds, the competition for the “ultra-high-net-worth” segment remains intense, creating a divide between entry-level luxury and top-tier exclusivity.
Comparative Market Context for Premium Brands
To understand the scale of the challenge, one must look at the broader performance of the luxury and premium goods sector within the Chinese market. The following table illustrates the divergence in consumer behavior across different pricing tiers.
| Consumer Segment | Spending Behavior | Market Sensitivity |
|---|---|---|
| Ultra-Luxury | Stable / Growing | Low |
| Premium (Coach) | Moderating | Medium-High |
| Aspirational | Declining | High |
The data suggests that the “aspirational” consumer—those who purchase luxury goods as occasional treats or status markers—is the segment most impacted by the current economic climate. This group is the primary driver for brands positioned in the accessible luxury tier.
Macroeconomic Drivers Shaping the Luxury Outlook
The weakness in consumer spending is not an isolated phenomenon but is deeply rooted in China's current economic conditions. Factors such as deflationary pressures and a cooling real estate sector have a direct correlation with household wealth and, by extension, luxury consumption. Investors monitoring the sector are closely watching for signs of government stimulus that could reinvigorate domestic demand.
The implications extend beyond Coach. Competitors such as LVMH (EPA: MC) and Hermès (EPA: RMS) are also monitoring these shifts, as any significant change in Chinese consumer behavior ripples through the entire global luxury supply chain. If the spending slump persists, it may lead to a broader revaluation of luxury stocks in the coming quarters.
The next major indicator for the sector will be the upcoming quarterly earnings reports from major luxury conglomerates, which will provide more granular data on whether the spending weakness is localized to specific brands or is a systemic shift across the entire Chinese retail market.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute financial advice.
