
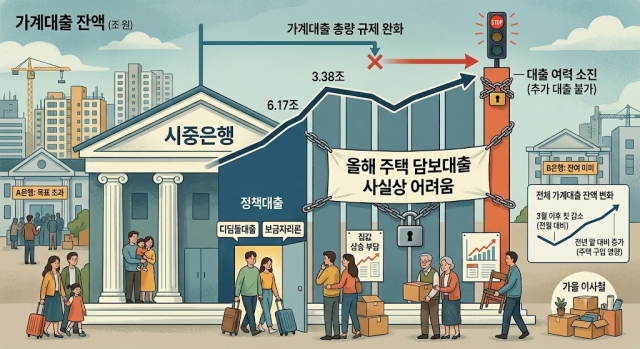
South Korea’s five major commercial banks have effectively shut down new household lending capacity just one month after regulatory easing expanded mortgage limits, as surging demand completely exhausts newly provisioned liquidity quotas ahead of the fourth quarter.
The Bottom Line
- Credit Squeeze: South Korea’s top five lenders have exhausted their expanded household loan thresholds, forcing abrupt product suspensions.
- Regulatory Pivot: Financial authorities recently relaxed aggregate caps, but retail borrowing velocity outpaced projected liquidity pools.
- Market Fallout: Prospective homebuyers face immediate financing roadblocks, shifting pressure onto secondary lenders and non-bank financial institutions.
Exhausting the Expanded Thresholds
When financial regulators elected to ease household debt aggregate limits, the objective was to inject flexibility into a constrained retail credit market. But the balance sheet tells a different story. Within a single month, consumer demand absorbed every won of the newly minted lending capacity across major institutions, including Shinhan Bank and KB Kookmin Bank. Here is the math: loan applications accelerated at a pace that neutralized regulatory breathing room almost as fast as it was granted.
This rapid depletion has forced credit committees to pull emergency levers. Major commercial lenders are once again locking down mortgage windows and tightening internal approval criteria to stay within annual aggregate targets monitored by the Financial Services Commission (FSC). For borrowers looking to lock in rates, the window has slammed shut far sooner than anticipated.
Macroeconomic Pressures and the Real Estate Feedback Loop
The sudden restriction highlights the persistent friction between housing market stabilization policies and consumer credit demand in South Korea. As housing transactions flickered back to life following minor policy adjustments, buyers rushed to secure financing. That velocity overwhelmed institutional risk models, leaving banks with little choice but to ration capital.
According to recent industry data tracked by Reuters, central bank policy rates and commercial lending yields have created an environment where retail borrowers aggressively front-run anticipated policy shifts. When banks slam the brakes, liquidity does not simply vanish; it migrates. Borrowers denied at primary commercial banks are spilling over into mutual savings banks, insurance companies, and online lending platforms, where borrowing costs are measurably higher.
| Lender Category | Policy Adjustment | Liquidity Status | Primary Impact |
|---|---|---|---|
| Top 5 Commercial Banks | Aggregate Cap Relaxed | Exhausted | New mortgage approvals suspended |
| Secondary Financial Institutions | Unchanged | Moderate Inflow | Absorbing overflow retail borrowers |
| Regulators (FSC) | Monitoring & Quota Review | Strict Enforcement | Targeting total household debt growth |
What Lies Ahead for Retail Borrowers
As the market approaches the close of Q3, commercial desks are bracing for a prolonged credit freeze. Regulators have shown little appetite to expand quotas further without concrete evidence of household deleveraging. Consequently, the burden of debt management has shifted entirely back onto the consumer.
Market observers note that until aggregate household debt metrics align with official targets, any future easing will likely be short-lived. For corporate strategists and retail banking divisions, this means revenue growth will have to come from fee-based services and corporate lending rather than residential mortgages.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute financial advice.
