
Driven by strong demand and rising prices across NOR Flash, NAND Flash, and eMMC products, the memory manufacturer achieved record quarterly and nine-month revenues while analysts maintain a bullish outlook.
The memory market’s sharp supply tightness has propelled Macronix International to historic financial milestones. Third-quarter consolidated revenue reached 24.237 billion New Taiwan dollars, representing a 26.7% increase from the previous quarter and a 195.1% jump compared to the same period last year, according to company figures reported by Yahoo.
Surging Pricing and Product Shifts Drive Third-Quarter Growth
Behind the revenue figures, pricing power and product mix have changed across the company's core memory lines. Institutional research indicates that third-quarter contract prices for SLC NAND, NOR Flash, and eMMC rose substantially, with SLC NAND seeing increases of 70% to 100%, NOR Flash climbing 40% to 60%, and eMMC gaining 20% to 30%.
These price adjustments pushed Macronix’s gross margin to an estimated 71.5%. The company’s internal product structure has simultaneously evolved. During the second quarter, parent-company sales figures showed NOR Flash accounting for 48% of revenue down from 58% in the first quarter, while NAND and eMMC combined expanded from 30% to 43% as detailed in market analysis from Pocket Securities. Within the NAND category, eMMC surged by 317% on a quarterly basis, capturing 58% of that specific segment.
Production Adjustments Lead to Lower Target Price for M
Despite robust pricing, some institutional trackers note that third-quarter revenue finished slightly below initial projections—reaching roughly 91.6% of earlier estimates. Local brokerages attribute this variance to production line adjustments made earlier in the year, which shifted NOR and ROM capacity toward eMMC manufacturing, alongside low inventory levels for NOR and SLC NAND and slower-than-expected yield improvements for eMMC according to reports from SETN.
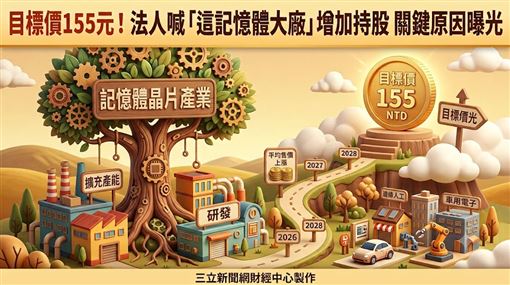
Reflecting these output constraints and production line conversion losses, a domestic advisory firm trimmed its target price for Macronix from 218 New Taiwan dollars down to 155 New Taiwan dollars while maintaining an add or increase holdings rating. Analysts project that persistent demand from Edge AI devices, boot drives, and automotive applications will keep supply tight and support a strong price floor for flash memory through 2027, with earnings per share potentially reaching 42.8 New Taiwan dollars by 2027.
Macronix Expands Capacity to Meet Growing Demand
Looking ahead, market participants are closely monitoring the upcoming October 27 online earnings conference led by Chairman and Chief Executive Officer Min-Charng Wu as noted by Money Link. Fourth-quarter forecasts point to continued sequential revenue growth of roughly 20%, with gross margins potentially rising past 75% as SLC NAND contract prices climb an additional 40%.
To capture sustained demand, Macronix previously approved an additional 15.8 billion New Taiwan dollars in capital expenditures to expand advanced manufacturing capacity highlighted in coverage by TechNice. The company plans to introduce 2.1k 3D NAND and 4k 12-inch NOR capacity by the final quarter of 2027, with volume production expected to contribute to output starting in the first half of 2028.
Related reading
