
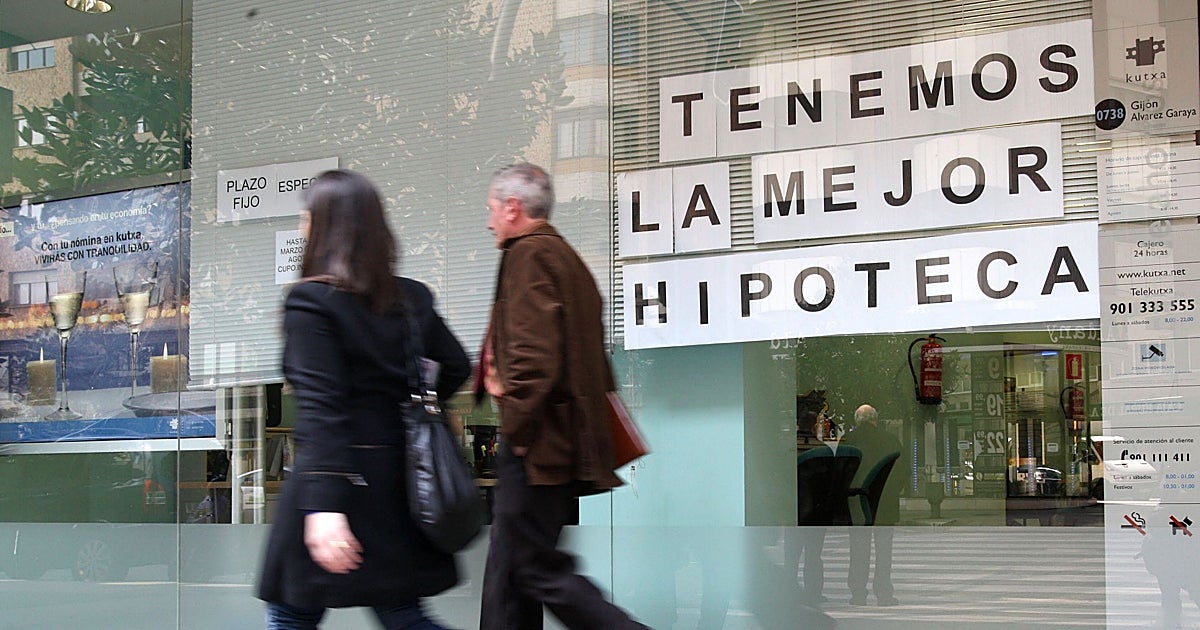
Mortgage Cancellations Hit Record Highs as Borrowers Fear Interest Rate Volatility
Mortgage cancellations reached historic highs as European borrowers rushed to clear debts, driven by mounting anxieties over potential central bank rate hikes and renewed interest rate spirals. Financial institutions report an unprecedented volume of early loan settlements, fundamentally altering balance sheets across the consumer lending sector.
The Bottom Line
- Debt Reduction Urgency: Borrowers are aggressively liquidating fixed- and variable-rate mortgages to shield household balance sheets from future macroeconomic tightening.
- Banking Liquidity Pressures: Financial institutions face accelerated prepayment speeds, which compress net interest margins and disrupt long-term yield projections.
- Insurance Scrutiny: Borrowers actively reviewing loan cancellation terms are simultaneously evaluating mandatory linked products, such as bundled mortgage life insurance policies.
Decoding the Rush to Clear Household Liabilities
The acceleration of mortgage terminations reflects a profound shift in consumer psychology. For years, low benchmark rates anchored by central bank accommodations encouraged long-term leverage. Today, persistent macroeconomic uncertainty has inverted that calculus. According to retail banking data, households are redeploying liquid savings to eliminate debt servicing costs entirely.
Here is the math: paying down a 3.5% or 4.5% mortgage delivers a risk-free, after-tax return equivalent to that interest rate. When weighed against volatile equity markets and stubborn inflation prints, risk-averse consumers are choosing balance-sheet fortification over yield chasing. But the balance sheet tells a different story for lenders, who now must contend with the premature disappearance of lucrative, long-duration interest streams.
| Metric Category | Observed Trend | Market Implication |
|---|---|---|
| Early Mortgage Extinguishments | Surged to record volumes | Accelerated cash-flow return to lenders; reduced future interest income |
| Interbank Benchmark Rates | Retained at restrictive plateaus | Heightened consumer sensitivity to variable-rate repricing risks |
| Linked Insurance Reviews | Widespread policy audits | Increased administrative friction around bundled insurance cancellations |
Navigating Linked Financial Products During Loan Extinguishment
Clearing a mortgage involves more than simply transferring the principal balance to the lender. Borrowers who bundled their home loans with mandatory or incentivized insurance products face an intricate web of contractual conditions. Financial advisors emphasize that extinguishing a loan does not automatically terminate associated policies, such as life or property insurance tied to the original credit facility.
Borrowers must explicitly communicate their intention to either extinguish or maintain these auxiliary insurance policies directly with their financial institution. As lenders process these mass cancellations, back-office operations face bottlenecks. These administrative hurdles require proactive communication from the consumer to ensure that unused insurance premiums are properly evaluated or proportionally refunded where contractually permitted.
Institutional Implications and Market Outlook
The broader banking sector cannot absorb this wave of early repayments without strategic adjustments. Retail divisions accustomed to steady, predictable interest margins must now reallocate capital in an environment where loan books are shrinking faster than projected. Competitors are aggressively revising their forward guidance for net interest income.
Furthermore, analysts note that this behavior signals a deep-seated caution among prime borrowers. Rather than leveraging cheap credit for asset acquisition, consumers are locking in debt-free status. As markets look toward the close of Q3 2026, the sustainability of this deleveraging trend will depend heavily on upcoming monetary policy announcements and whether benchmark rates maintain their restrictive posture.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute financial advice.
