
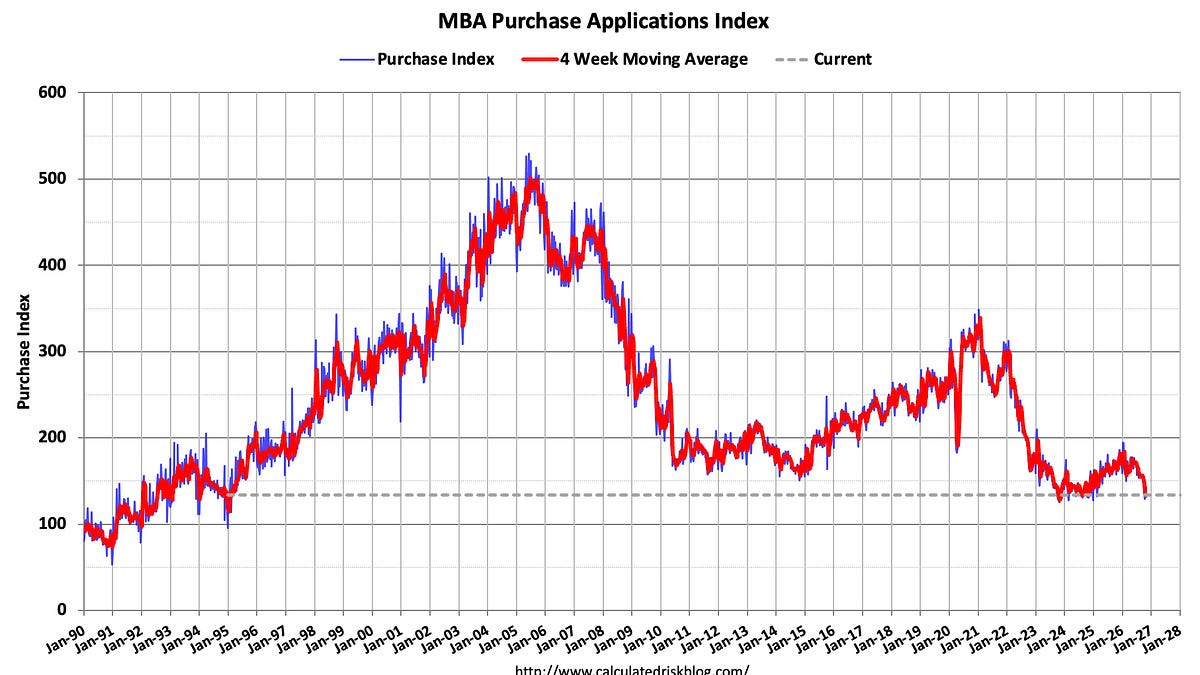
Mortgage applications fell 1.2 percent during the week ending October 30, 2026, as the unadjusted Purchase Index dropped 19 percent compared to the same week last year, according to data from the Mortgage Bankers Association (MBA) reported by Calculated Risk.
The slowdown in lending activity persists despite a recent dip in interest rates. While the 30-year fixed-rate mortgage drifted down to 7.3 percent last week—the lowest level since September 2026—the market remains sluggish. Borrowers are increasingly pivoting away from traditional fixed-rate products to mitigate high monthly costs.
Purchase activity hits 19 percent year-over-year decline
The Market Composite Index, which tracks total mortgage loan application volume, saw a 1.2 percent decrease on a seasonally adjusted basis from the previous week. On an unadjusted basis, the index fell by 2 percent. The most significant contraction is occurring in the purchase market; the seasonally adjusted Purchase Index declined 2 percent from one week earlier, while the unadjusted figure saw a 4 percent drop. This places current purchase activity 19 percent lower than it was during the same period in 2025.
This trend follows a period of volatility. Earlier in October, the MBA reported that mortgage applications had decreased by 2.7 percent for the week ending October 9, 2026, with the unadjusted Purchase Index sitting 16 percent lower than the previous year at that time.
Shifting borrower preference toward Adjustable-Rate Mortgages
As 30-year fixed rates remain elevated, a structural shift is appearing in how consumers architect their debt. Borrowers are increasingly opting for Adjustable-Rate Mortgages (ARMs) to secure lower initial payments. The ARM share of total mortgage activity has reached its highest level since September 2025.
This movement toward variable rates suggests a tactical response to the current interest rate environment.
Yields decline as Federal Reserve holds interest rates
The Federal Reserve’s decision to hold on additional rate hikes at its October meeting provided some downward pressure on yields. Mike Fratantoni, MBA’s SVP and Chief Economist, noted that while the 30-year rate declined to 7.3 percent, activity remains slow. Purchase volume is down, and refinance volume is effectively flat at a very low level.
The Refinance Index showed a marginal increase of 0.1 percent from the previous week, yet it remains 60 percent lower than the same week one year ago. Stagnant refinancing rates show how difficult it is to find meaningful savings in the current rate climate.
| Metric (Week Ending Oct 30, 2026) | Value / Change |
|---|---|
| 30-Year Fixed Mortgage Rate | 7.3% |
| Market Composite Index (Seasonally Adjusted) | -1.2% |
| Purchase Index (Unadjusted YoY) | -19% |
| Refinance Index (YoY) | -60% |
The impact of rate levels on housing inventory and pricing
With 30-year rates at 7.3 percent, existing home sales are expected to slow in the coming months. This deceleration typically places downward pressure on house prices as buyer demand remains constrained by the cost of capital.
The disconnect between available inventory and application volume highlights a persistent friction in the real estate ecosystem.
The current environment forces a difficult choice for both buyers and sellers. Sellers face the prospect of longer listing periods and potential price concessions, while buyers must contend with high borrowing costs or the inherent risks associated with the rising share of ARM products.
The 30-year fixed rate remains higher than the levels seen in November 2023, when the rate was 7.5 percent.
