
Microsoft said on Thursday it will package future Azure custom chips with Intel Foundry’s EMIB-T advanced packaging, becoming the first cloud operator to publicly commit its own silicon to Intel’s packaging line.
The agreement bundles more than packaging: multi-year Xeon supply, CXL memory collaboration, the first QAT virtual machines in the cloud, and TDX confidential computing for Azure, according to Zod.
The weight of this deal sits in the customer’s name. Intel Foundry has pushed advanced packaging to the front of its external business, but this is the first publicly disclosed order to package a major cloud provider’s in-house chips, as vlsi.kr’s analysis of the joint announcement lays out.
The parts involved, per zod.kr’s report, are next-generation versions of the Maia 200 AI inference accelerator and the Cobalt 200 CPU built for agent workloads. EMIB-T feeds power vertically through silicon vias into multiple dies stacked inside one package.
Saurabh Dige, Microsoft’s corporate vice president for Azure systems and architecture, framed the work as building infrastructure around the workloads that matter most to customers. Naga Chandrasekaran, the executive vice president who leads Intel Foundry, centered the agreement on extending future generations of Azure infrastructure with EMIB, optimizing silicon, packaging, compute, memory and software together.
Neither executive named a chip.
Small bridges, buried in the substrate
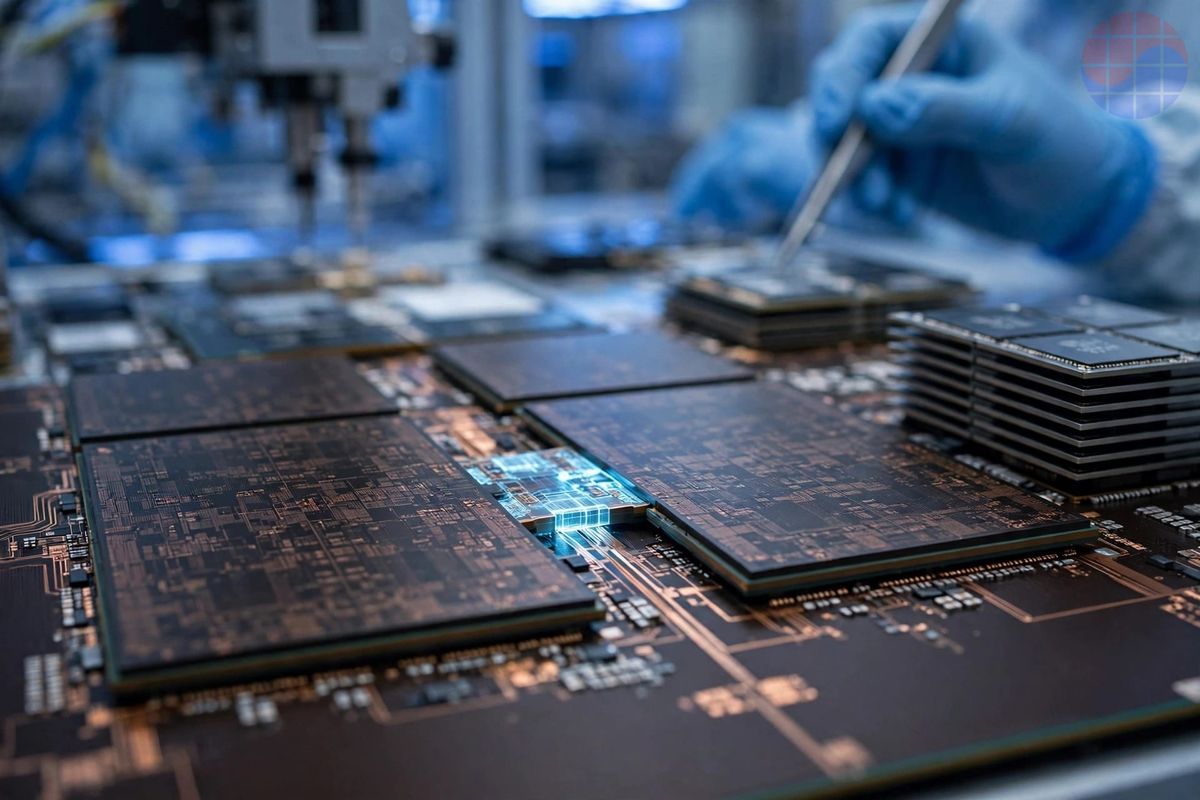
EMIB — Embedded Multi-die Interconnect Bridge — is a 2.5D packaging technique that buries a small silicon bridge inside the package substrate and connects neighboring dies only where their edges meet, over fine wiring laid on that bridge. Intel has manufactured it since 2017, for its own processors and for external customers’ silicon, according to the packaging documentation vlsi.kr cites.
EMIB-T is the variant that adds through-silicon vias to the bridge; a sibling variant, EMIB-M, adds MIM capacitors instead. The economic pitch is straightforward: silicon goes only where dies actually need to connect, sidestepping the cost and yield penalties that grow with interposer area, while simplifying the supply chain and assembly process.
Great to see our collaboration with @Microsoft continue to accelerate. Azure, Xeon, Intel Foundry and EMIB innovation are coming together to help build the next generation of AI infrastructure.
TSMC’s long-standing answer is CoWoS, in production since 2012, which seats dies on a full-area silicon interposer. Its newest variant, CoWoS-L, has itself shifted toward local silicon connections embedded in an RDL interposer — the same directional bet EMIB’s family made years earlier. The packaging industry, on this evidence, is converging on local bridges over monolithic interposers.
Two numbers, both with footnotes
Two performance figures anchor the announcement. Both come from the companies’ own measurements, and both rest on comparison setups detailed only in footnotes — footnotes that vlsi.kr pulled apart line by line.
| Claim | Measured configuration | Comparison configuration | Test completed |
|---|---|---|---|
| M-series v4 VMs, up to 2.3x performance and memory flexibility | 76 vCPUs; 1TB DRAM plus 1TB CXL (1,764GB) | 64 vCPUs; 1,007GB DRAM | November 10, 2026 |
| SQL backup, up to 2.5x faster on QAT VM | Xeon 6973P-C (Granite Rapids); 2.06TB memory; SQL Server 2025 | Dual Xeon Gold 8362; 1TB DDR4; Windows Server 2025 | November 2, 2026 |
The 2.3x figure describes Azure’s M-series v4 virtual machines using Xeon 6 CXL memory with Intel’s Flat Memory Mode, tested against demanding workloads. But the measured system carried more vCPUs and 757GB more total memory than the comparison system, running microVMs whose Python interpreter held a 12GB dataset in residence while cycling through nine tools across 13 steps. Read the 2.3x as CXL’s effect alone and the footnote contradicts you.
We're expanding our collaboration with @Microsoft to help support continued innovation across @Azure. 𝐌𝐢𝐜𝐫𝐨𝐬𝐨𝐟𝐭 𝐢𝐬 𝐭𝐡𝐞 𝐟𝐢𝐫𝐬𝐭 𝐜𝐨𝐦𝐩𝐚𝐧𝐲 𝐭𝐨 𝐚𝐧𝐧𝐨𝐮𝐧𝐜𝐞 𝐩𝐥𝐚𝐧𝐬 𝐭𝐨 𝐮𝐬𝐞 @Intel_Foundry'𝐬 𝐄𝐌𝐈𝐁 𝐚𝐝𝐯𝐚𝐧𝐜𝐞𝐝 𝐩𝐚𝐜𝐤𝐚𝐠𝐢𝐧𝐠. 𝐓𝐡𝐞… pic.twitter.com/eKQSEwStsf
The 2.5x figure covers SQL backup on a cloud-first QAT virtual machine — measured on a Granite Rapids-generation Xeon against a dual-socket Xeon Gold 8362 system with DDR4, according to Vlsi. Different CPU generations, different memory capacity, different SQL Server builds.
Neither figure measures the packaging. The announcement offered no performance numbers for EMIB-T at all, and both benchmarks carry the caveat that results may vary.
Xeon stays; Diamond Rapids follows
The packaging deal is one strand of a five-part agreement. Microsoft committed to keep Intel Xeon processors in Azure under a multi-year supply pledge, explicitly including the next-generation Diamond Rapids Xeon 7. The two companies will jointly pursue CXL-based Xeon integration targeting memory efficiency and system-level control in the datacenter.
Security gets its own lane. TDX-based confidential computing encrypts a virtual machine’s memory and CPU register state even while the VM moves between hosts — a capability aimed at workloads where tenants refuse to trust the hypervisor underneath them.
The wafers aren’t part of this deal
Reading EMIB adoption as a defection from TSMC isn’t supported by what was announced. Packaging and wafer fabrication are separable processes, and the joint statement never says which wafer process will produce the dies that EMIB-T later ties together. vlsi.kr flags precisely this as the the interpretation the announcement does not back.
What the deal does establish is directional. A hyperscaler with Microsoft’s silicon roadmap — Maia accelerators, Cobalt CPUs, and a Xeon fleet running alongside both — has now publicly anchored part of that roadmap to Intel’s packaging floor.
The blanks in the announcement
What the announcement omits runs nearly as long as what it states: no dollar value, no volumes, no schedule. On which chips use EMIB, the two outlets’ reporting diverges — zod.kr names the next-generation Maia 200 and Cobalt 200, while vlsi.kr’s close read of the announcement text found no chip named anywhere in it, with both executives’ statements avoiding part numbers entirely.
Intel Foundry traces its external business to March 2021, when then-CEO Patrick Gelsinger launched Intel Foundry Services and opened manufacturing capacity to outside chip companies, alongside plans for its first large-scale foundry operation in Arizona. For decades before that, Intel had designed and built only its own chips, which made the move a reversal of the integrated device manufacturer model it once embodied.
Since June 2023, the manufacturing arm has operated as a standalone unit under an “internal foundry” model, in which Intel’s own product groups buy capacity as external customers would, at prices benchmarked against the industry. At the time, Intel projected more than $20 billion in manufacturing revenue and the position of second-largest foundry.
Both headline figures carry the footnoted warning that results may vary. The money, the volumes, the schedule and the wafer source remain blank in the announcement as published Thursday.
Worth a look
- Czech NIX.CZ Hits Record 4 Tbps Traffic During GTA 6 Preload
- Activision, Toys for Bob Tease Spyro: A Realm Beyond at The Game Awards 2026
- Intel Reportedly Lays off Staff in Its Global IT Department (world-today-news.com)
- Microsoft Announces Second Wave of November Game Pass Additions Through Dec 3 (newsy-today.com)
