
Pakistani women are increasingly using digital platforms to secure financial autonomy, with mobile internet adoption climbing to 53 percent by 2025.
While these tools bypass traditional mobility constraints, significant cultural and structural barriers, including the “time tax” of domestic responsibilities and limited control over earned capital, continue to hinder sustainable growth.
While digital connectivity has provided a vital entry point for women, the transition from home-based entrepreneurship to long-term financial independence remains fraught with systemic challenges, according to reporting by CNA.
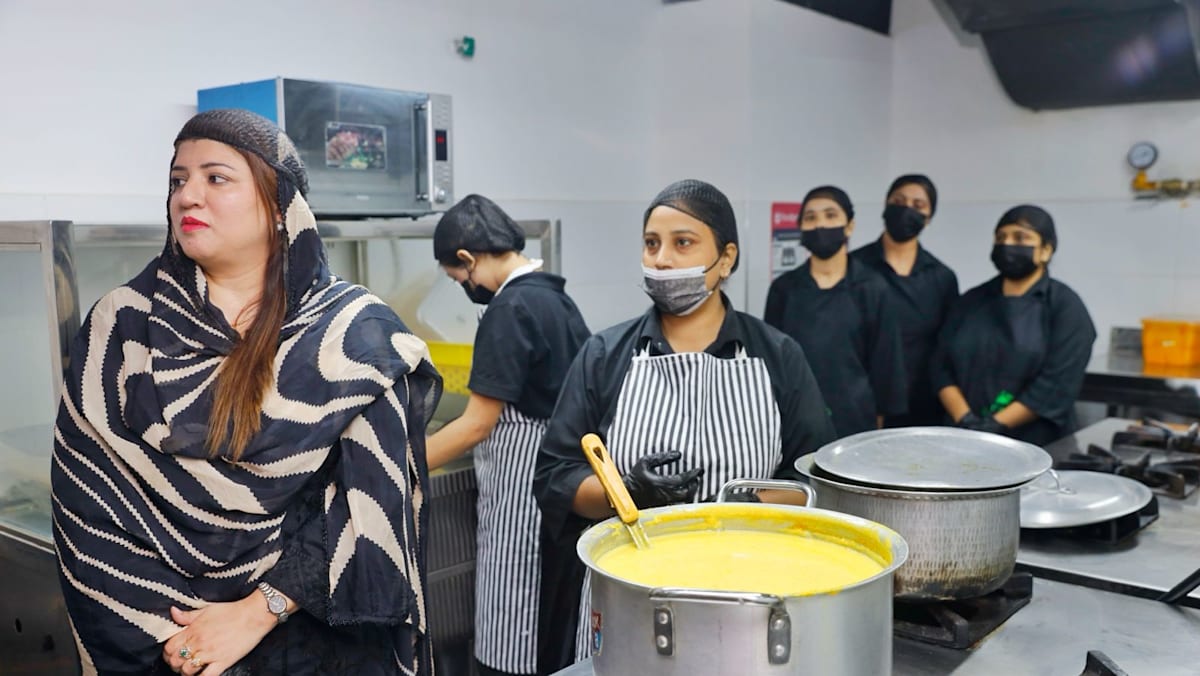
The digital evolution is perhaps best illustrated by the experience of Ayesha Kamil. A 42-year-old with a PhD in environmental science, Kamil transitioned from a professional career to launching a food delivery business via Foodpanda. Within 18 months, she expanded her operation to three kitchens employing 25 women, recently hitting a single-day revenue mark of 250,000 Pakistani rupees from 300 orders, khanlist.com reported.
Kamil’s model highlights a specific strategy: by creating women-only workspaces, she provides an environment where families who might otherwise restrict female employment feel comfortable allowing participation. However, such successes remain the exception rather than the rule in a broader labor market where female participation, though rising to 24.4 percent in 2024-25, still trails the 70 percent mark for men, urgent.news noted.

The Persistence of Structural Barriers
Even for women who successfully launch businesses, the “time tax”—the disproportionate burden of childcare and eldercare—often disrupts operations. Halima Iqbal, co-founder of the women-focused fintech company Oraan, notes that digital access does not automatically equate to financial control.
In many instances, women generating monthly revenues between 2 and 3 million Pakistani rupees still feel compelled to conceal earnings from their husbands to ensure they can support their own aging parents, CNA reported.
“If you see the life cycle of a woman, it is only at a later stage, when her children grow up or her relationship is stable, that she can work. Before that, she is not allowed to work or does not have the time to do so,” Halima Iqbal, co-founder of the women-focused fintech company Oraan, said.
This reality highlights a critical gap in the narrative of digital inclusion. While mobile wallets have made it easier to receive payments, the underlying social structures that dictate who controls household finances have not shifted at the same pace as the technology. The following data highlights the trajectory of female inclusion over the last decade:
| Metric | Historical Baseline | Recent Data (2024-25) |
|---|---|---|
| Mobile Internet Adoption (Women) | 19% (2020) | 53% |
| Female Labour-Force Participation | 21.4% (2020-21) | 24.4% |
| Male Labour-Force Participation | N/A | ~70% |
Government Digitizes Cash Assistance for 10 Million Beneficiaries
The push for digitization is not solely a grassroots movement; it is also a matter of state policy. The government’s Benazir Income Support Programme, which serves 10 million beneficiaries, transitioned to disbursing all cash assistance via mobile wallets this year.
This shift aims to reduce friction in financial transactions, though critics suggest that without concurrent improvements in financial literacy and credit access, the impact on long-term sustainability will remain limited, urgent.news reported.
The use of platforms like Foodpanda and Facebook by Pakistani women to earn an income has drawn attention from experts regarding the challenges of building sustainable businesses. In 2017, JazzCash initiated a partnership with Unilever to train women in the “Guddi Baaji” network as mobile banking agents, marking an early, coordinated effort to bridge the gap between rural retail and digital finance, CNA reported.
Established in 2012, Foodpanda operates as a Singaporean online food and grocery delivery platform under the ownership of Berlin-based Delivery Hero. The company significantly strengthened its presence in Pakistan by acquiring the local rival Eat Oye in 2014. By 2021, the organization had positioned itself as the largest food and grocery delivery platform in Asia outside of China.
The platform has increasingly focused on the domestic sector through its “Home Chefs” initiative, which launched in Pakistan specifically to assist female cooks in generating side income. This program, which provides a pathway for individuals lacking the capital for physical storefronts, currently supports between 8,000 and 9,000 home chefs, with long-term plans to scale the initiative to 100,000 participants across its markets.
Future Outlook for Financial Independence
As of late November 2026, the question of whether this digital surge will translate into lasting financial independence for women remains open. While the expansion of 40 million women into the mobile internet ecosystem provides a powerful new tool, the lack of control over earnings remains a major hurdle. “At the grassroots level, there is no control,” Iqbal told CNA.
