
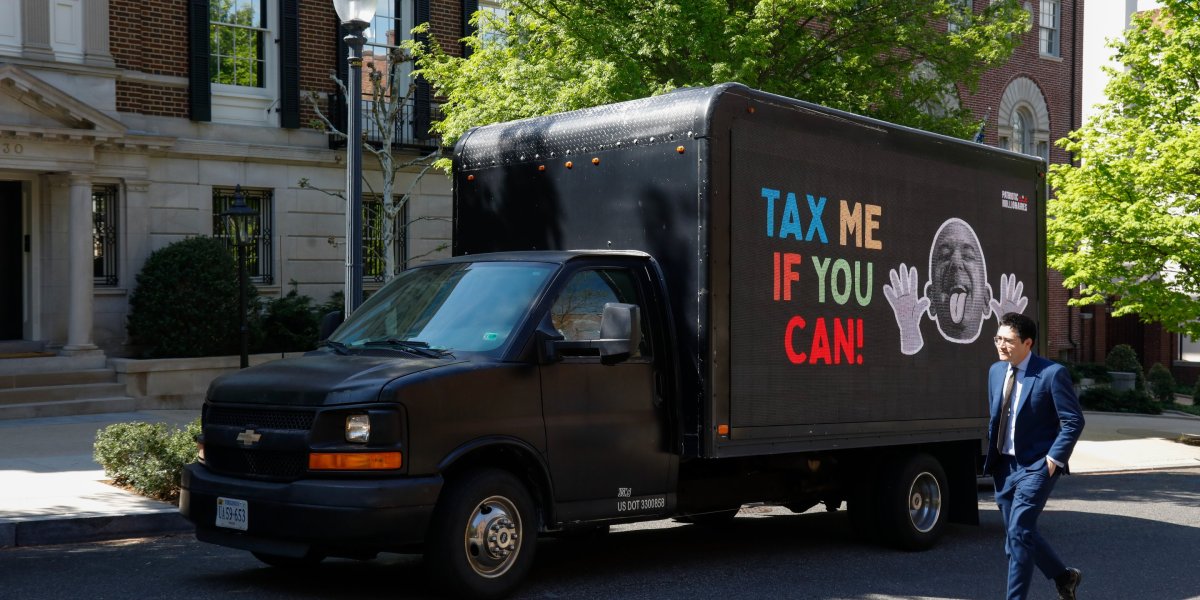
Private wealth structures face mounting pressure as historic public debt levels and rising service costs force governments to weigh sweeping tax revisions beyond the midterm elections.
- Federal debt and servicing costs create unavoidable pressure on policymakers to target private wealth, income, and capital gains for new revenue streams.
- Existing estate and gift tax exemptions of $15 million per individual provide current planning room, but reliance on these thresholds remaining static poses a risk.
- Geographic and multi-jurisdictional complexities—including state-level variations and citizenship-based taxation—require continuous structural adaptation rather than reactive changes.
Public finances will outlast the political theatre of any midterm election, shifting the focus in Washington toward how the government will raise more revenue. A government carrying historic levels of debt leaves administrators with limited room for additional borrowing and spending.
Taxation remains the most direct starting point for lawmakers seeking to bridge deficits. Decisions on income, capital gains, estate, and gift taxes dictate how capital is held, invested, and transferred between generations.
High-net-worth families often spread capital across public equities, private equity, real estate, venture capital, and international business interests. However, diversification across asset classes spreads investment risk without necessarily spreading tax risk.
| Tax and Asset Category | Primary Exposure | Planning Consideration |
|---|---|---|
| Estate and Gift Tax | Generational transfers | $15m individual / $30m couple exemptions |
| Capital Gains | Equities and real estate | Vulnerable to statutory rate adjustments |
| Multi-Jurisdictional Holdings | Cross-border assets | Internal Revenue Code vs. foreign law friction |
State taxation adds another layer of friction for families with property or businesses distributed across multiple state lines. Rules governing residency and local asset holding frequently interact unpredictably with federal mandates.
For international families, the United States system of citizenship-based taxation means American citizens remain subject to domestic tax on worldwide income while living abroad. Non-US families with American assets or beneficiaries face comparable compliance hurdles under the Internal Revenue Code.
Structures that function smoothly under foreign legal frameworks can produce unexpected liabilities when evaluated under American statutes. Legal, tax, and private wealth specialists must coordinate closely to avoid localized optimizations that trigger broader compliance penalties.
Reacting to isolated news headlines during periods of fiscal uncertainty often destabilizes a family’s overall financial architecture. Testing existing arrangements against scenarios ranging from plausible adjustments to extreme regulatory shifts offers a more reliable defense.
Families with adaptable structures are better positioned to respond calmly when rules change, preserving flexibility over where to establish businesses or hold assets. The underlying fiscal challenge will remain active regardless of which political party holds power in Washington.
Reviewing estate, trust, and ownership structures while time permits avoids the rush that invariably follows unexpected legislative overhauls. The central question for wealth holders is whether their affairs are organized to adapt to whatever fiscal policy emerges next.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute financial advice.
