
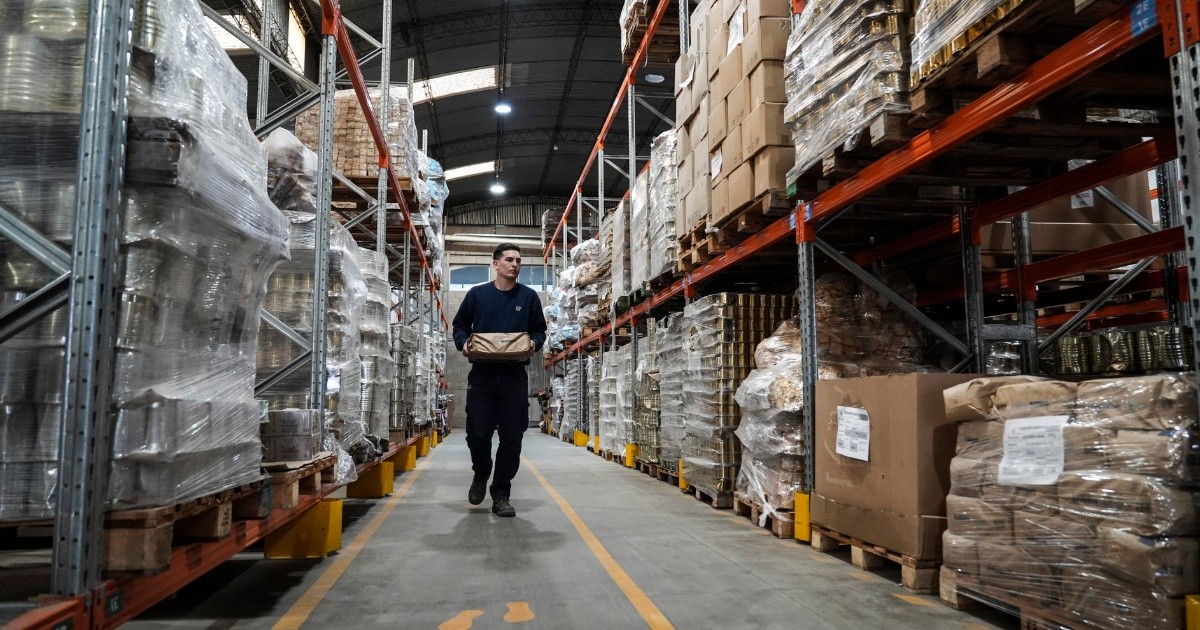
The industrial real estate market in Greater Rosario faces a supply increase as available warehouse and logistics inventory surged 70.5% year-over-year by September 2026, according to a regional survey by the Colegio de Corredores Inmobiliarios de Santa Fe Rosario (Cocir) and researchers Paula Báscolo and Hernán Lapelle from the National University of Rosario (UNR).
Industrial Property Growth Outpaces Rent Increases
- Inventory Expansion: Total listed industrial and logistics properties grew 46.5% annually to 293 units, encompassing 787,801 square meters of space.
- Rental Lag: Average asking rents reached $3.50 per square meter monthly, posting a 12.9% nominal increase that trailed the broader 16% dollar-denominated inflation rate.
- Yield Compression: Gross annual rental yields expanded to 8.1% overall, driven primarily by strong performance within the urban core where rents outpaced asset price appreciation.
Mapping the Greater Rosario Industrial Inventory Surge
The fifth joint survey conducted by Cocir and UNR researchers tracked 293 industrial and logistics facilities sized at 1,000 square meters or larger within a 25-kilometer radius of Rosario. This inventory represents a total footprint of 787,801 square meters across the metropolitan region, marking a 41.9% expansion in available surface area compared to the previous year. Rental properties command the lion’s share of this inventory, accounting for 162 distinct structures spanning over 500,000 square meters. Meanwhile, properties earmarked for outright purchase stand at 131 units covering 287,608 square meters.
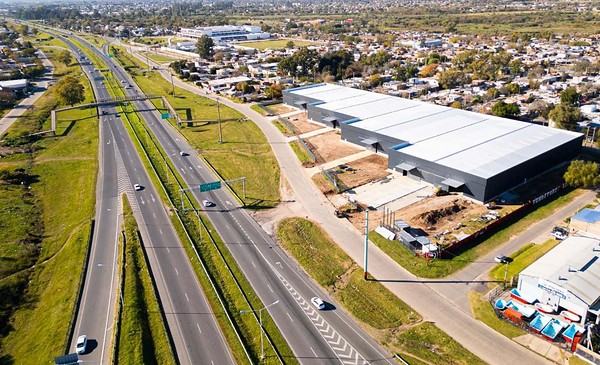
Geographic distribution heavily favors the intermediate corridor. The First Radio—defined as the zone situated between the Circunvalación avenue and the A012 National Route—consolidates 110 rental properties totaling 356,011 square meters. This single corridor captures roughly 71.2% of the entire regional space available for lease. Conversely, the Urban Radio within the Circunvalación belt contains 58% of all properties listed for sale, highlighting a clear structural divide between transactional preferences across sub-markets.
Market Shifts Reduce Industrial Property Demand
Economic headwinds have fundamentally altered commercial property valuations across the region. A shift in macroeconomic policy models has dampened corporate appetite for holding massive physical inventories, a practice previously utilized as an inflation hedge. Consequently, developers who broke ground on new facilities prior to the presidential administration shift now face a sluggish leasing environment characterized by depressed consumer demand and lower industrial output.
Asking prices for properties listed for sale averaged $520.42 per square meter across the broader market in September 2026. This figure reflects a modest 5.3% recovery compared to 2025 levels, though valuations remain below the peaks observed in 2024. The highest square-meter purchase prices concentrate within the First Radio at $583.31, whereas the Urban Radio trades at a discount. On the leasing side, monthly rents average $3.50 per square meter, with the First Radio leading at $3.60 while the Urban Radio lags at $2.81.
Calculated gross annual rental yields rose to 8.1% in September 2026, improving from 7.5% in 2025 and 5.7% in 2024. The urban core experienced the sharpest yield expansion, climbing from 3.8% to 6.6% as dollar-denominated rental rates outpaced property sales prices. In contrast, the First Radio saw yields contract slightly from 8.0% to 7.4% due to stronger capital appreciation in sale values, narrowing the historical yield gap between the downtown core and outer logistics hubs.
