
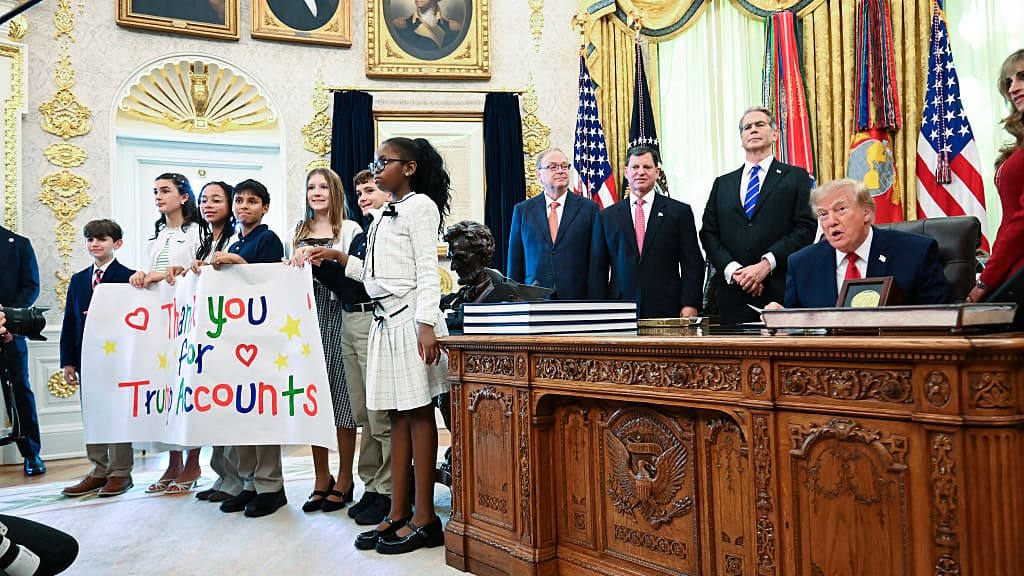
Sixty million American children under the age of 18 were automatically enrolled in government-backed “Trump Accounts” on October 1, 2026, according to an announcement by President Donald Trump in the Oval Office. The mass registration, detailed by Yahoo Finance and CNBC, brings the total number of enrollees to 70 million when combined with roughly 10 million accounts previously opened by parents and guardians since the program’s launch on July 4. That cumulative figure covers every American child under 18 with a valid Social Security number, utilizing regulatory architecture established under the legislative package known as the “One Big Beautiful Bill.”
How the Treasury Department Executed the Mass Auto-Enrollment
The U.S. Department of the Treasury moved swiftly to implement the infrastructure behind the accounts. Following proposed regulations published on Tuesday, the agency completed the automatic enrollment of more than 60 million children by Thursday, according to the agency. Treasury Secretary Scott Bessent emphasized the scope of the rollout in an announcement provided directly to CNBC, stating that millions of children are now positioned with accounts ready for activation.
The program establishes tax-deferred investment vehicles where funds are automatically directed into a portfolio tracking the S&P 500 Index, encompassing roughly 500 of the largest publicly traded U.S. companies. While these accounts bear the children’s names, parents and legal guardians maintain management control until the account holders reach 18. At that juncture, the accounts transition into traditional Individual Retirement Arrangements (IRAs).
Funding Sources, Private Philanthropy, and Stock Donations
Capital flowing into the program has surpassed $4.5 billion since its summer debut. The White House reported that this total comprises $1.3 billion in federal seed money, $2.6 billion in philanthropic donations, and more than $600 million contributed directly by family members and friends. Annual contributions from personal networks are capped at $5,000 per child.
A significant portion of the philanthropic backing stems from a $6.25 billion investment from Michael and Susan Dell. Their contribution provides a $250 seed deposit for children born between 2016 and 2024 who reside in ZIP codes where the median family income is at or below $118,000, alongside families stationed on military bases. Concurrently, newborns and young children born from 2025 through 2028 qualify for a one-time, tax-free $1,000 pilot contribution directly from the U.S. Treasury.
Updated Treasury guidelines also permit direct stock donations to the accounts. Certified financial planner Ben Henry-Moreland noted that this provision appeals to wealthy founders and shareholders because it bypasses the capital gains taxes normally triggered when selling securities and gifting cash. Under the new rules, donated individual stocks generally must remain untouched within the portfolio for a mandatory five-year holding period.
What Parents Must Do to Claim and Fund the Accounts
Despite the automated creation of 60 million accounts, active parental intervention remains mandatory to unlock the financial benefits. Treasury regulations dictate that automatic enrollment alone does not trigger the government’s seed money or subsequent private deposits.

To successfully establish their standing, parents must use the Trump Accounts application to authenticate their personal identity, confirm their familial connection to the minor, examine the provided account details, and agree to the governing stipulations. Completing this verification process is a prerequisite for receiving the Treasury’s $1,000 pilot contribution, accepting the Dell family deposits, and enabling annual contributions from relatives or employers.
Policy Criticisms and Outreach Gaps Ahead of the Midterms
The program’s rollout coincides with the approach of the midterm elections, as political figures navigate the economic policy landscape. Public policy analysts argue that while the sweeping infrastructure creates broad opportunities, structural design flaws persist regarding wealth inequality.
Madeline Brown, a senior policy associate at the Urban Institute, observed that the rulemaking introduces the idea of auto accounts, meaning children won’t miss out on philanthropic gifts or growth on those gifts even if an account has not been activated. Brown noted that the initiative lacks guaranteed supplemental annual contributions from the federal government specifically targeted at low-income children to close generational wealth gaps.
Furthermore, awareness of the accounts remains unevenly distributed. Because the initiative initially mandated that households actively sign up, securing broad participation proved difficult, particularly within lower-income communities. Treasury estimates project that an additional two million accounts will be generated annually through the auto-enrollment pipeline, leaving policymakers and advocates facing an ongoing challenge to educate families across diverse socioeconomic strata.
