
UK homeowners face surging mortgage rates as average two-year and five-year fixed deals climb to multi-month highs, even as global bond yields reprice sharply higher amid mounting government debt and fiscal deficits across major economies, according to recent financial reporting.
The current financial landscape is experiencing a jarring shift. Homeowners and market watchers alike are confronting a renewed surge in borrowing costs, driven by a powerful mix of rising global bond yields and shifting monetary policy expectations. While just under a third of households in the country carry a mortgage, according to the government’s English Housing Survey, the ripple effects of these macroeconomic shifts are poised to touch nearly every corner of the property market.
Where UK Mortgage Rates Stand Now
The vast majority of mortgage customers—some 87%—rely on fixed-rate deals. While their monthly payments do not change overnight when financial conditions shift, the landscape greeting those seeking new deals has grown significantly more expensive. According to financial information service Moneyfacts data, the average two-year fixed residential mortgage rate reached its highest point since May 11 at 5.77% by mid-September. Meanwhile, the average five-year fixed deal climbed to 5.83%, marking its highest level since November 8, 2023.
For those on variable arrangements, the exposure is more direct. Approximately 500,000 homeowners hold tracker mortgages that automatically adjust alongside the Bank of England’s rate, while another 500,000 sit on standard variable rates dependent on lender decisions. At the same time, about 800,000 fixed-rate mortgages carrying an interest rate of 3% or below are projected to expire annually through the end of 2027, exposing thousands of borrowers to sharp payment increases as they refinance.
Global Bond Yields Flash Warning Signs
The pressure on domestic borrowing costs does not happen in a vacuum. Global bond markets are undergoing a broad repricing as investors reevaluate inflation, energy prices, and government borrowing requirements. Yields have climbed across major economies: the US 30-year Treasury yield has approached 5.3%, Japan’s 10-year government bond yield has moved past 3% for the first time since 1996, and UK 30-year yields have reached their highest level since 1998.
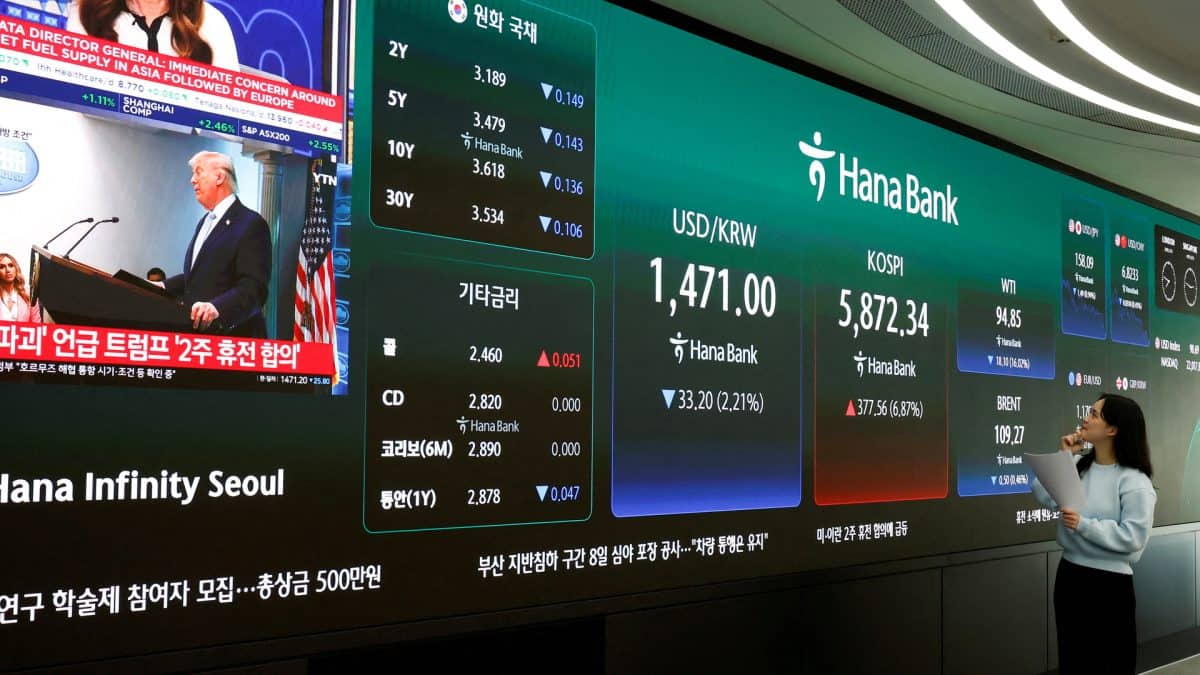
This simultaneous ascent in long-term yields tightens financial conditions across the board. Because long-term yields determine the cost of credit for governments, corporations, and households over extended periods, a sustained increase scales back expectations of imminent monetary easing. Investors who entered 2026 anticipating rate cuts are now witnessing a dramatic reversal, with market pricing pointing toward a higher probability of renewed rate hikes.
Uday Kotak, Indian banker, noted that as Japan’s 10-year bond crosses 3 per cent and the US’s hits 4.8 per cent, central banks may have no option but to expand balance sheets (print money) as government debt and deficits go up, adding that inflation and short-end rates would rise accordingly and warning everyone to be ready for a roller coaster ride in interest rate markets.
The Intersection of Energy Shocks and Sovereign Debt
Adding fuel to the bond market sell-off is a renewed spike in oil prices, sparked by fresh military exchanges between the US and Iran. Energy price shocks create an exceptionally difficult dilemma for policymakers. When oil climbs higher, it pushes inflation upward precisely as high borrowing costs begin to weigh down economic activity. Central banks are left to choose between tolerating elevated inflation or maintaining tight monetary conditions while economic growth slows.
| Mortgage Product Type | Average Rate / Details |
|---|---|
| 2-Year Fixed Residential | 5.77% (highest since May 11) |
| 5-Year Fixed Residential | 5.83% (highest since Nov 2023) |
| 2-Year Tracker Rate | 4.54% |
As these pressures converge, the traditional expectations held by borrowers at the start of the year have vanished. Refinancing costs for companies carrying heavy debt loads have risen, and future corporate earnings look less valuable in present-day terms as discount rates climb alongside government bond yields.
What Remains Unresolved for Borrowers
With central banks facing constrained choices between managing massive sovereign debt burdens and containing inflation, the trajectory for the remainder of the year remains volatile. For the hundreds of thousands of households facing expiring fixed terms, the central question is how long financial markets will demand such high premiums for long-term risk.
Worth a look
- Latvian Economy Sees Strongest Growth in Years, Experts Say
- China Launches 2,000-Server Submerged Data Center Off Shanghai, Building on Microsoft’s Concept
- How to Get Casetify Promo Codes, Student Discounts, and Sitewide Deals (newsdirectory3.com)
- India Mid- and Smallcaps: Record Highs Mask Sharp Market Polarization (time.news)
