
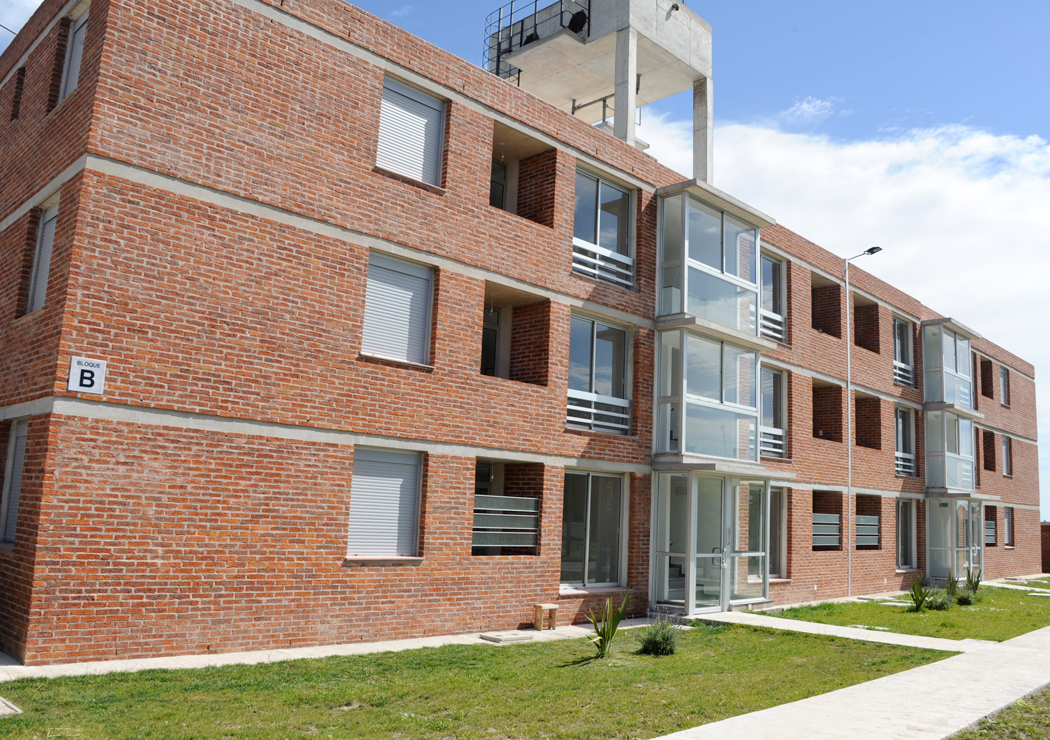
Uruguay's Ministry of Housing opened registration for 500 first-home loans with 95% financing and up to 50% subsidy.
Uruguay’s Ministry of Housing and Territorial Planning has opened online registration for 500 first-home mortgage loans under the Abriendo Puertas–Primera Vivienda program, Presidencia Uruguay reported, with applications accepted through Monday, November 30, 2026.
The state, via the BHU, will finance up to 95% of a home’s value.
The program targets a specific gap in Uruguay’s credit market: middle-income households that can afford a monthly mortgage payment but cannot accumulate the upfront savings most lenders require.
By covering up to 95% of the purchase price and capping the required down payment at 5%, the Ministry of Housing and Territorial Planning (MVOT) and the Banco Hipotecario del Uruguay (BHU) are effectively converting a savings problem into a payment problem—and then subsidizing half of that payment for qualifying households, according to Elobservador.
Housing Minister Tamara Paseyro framed the loan design as a direct response to that constraint. “When we took over the ministry, we saw that a significant number of Uruguayans with middle incomes had the ability to pay an installment, but did not have the ability to save—especially a sum as large as buying a home involves,” Paseyro said, according to the ministry’s website.
The scale is modest against the stated ambition. This call offers 500 loans; the program’s five-year target, as reported by Presidencia Uruguay, is 1,600. That gap—the bulk of the quinquennial envelope still to be allocated over the remainder of the quinquennium—tells applicants that this round is a first tranche, not the full envelope.
| Parameter | Montevideo, Maldonado, Ciudad de la Costa | Rest of the country |
|---|---|---|
| Maximum loan | ~US$117,000 (712,500 UI) | ~US$97,000 (589,000 UI) |
| Minimum household income | 77,000–146,000 pesos | 58,000–146,000 pesos |
| Terms common to all zones | ||
| Financing share | up to 95% of home value | |
| Required prior savings | 5% of purchase price | |
| Loan term | up to 25 years, in Unidades Indexadas (UI) | |
Why the 95% Threshold Is the Story
Hear the terms plainly: financing of up to 95% of a home’s value, denominated in Unidades Indexadas (UI)—Uruguay’s inflation- and wage-indexed unit—over a term of up to 25 years.
On a maximum 712,500 UI loan in the premium zones, that 5% savings requirement still means a buyer must bring roughly $6,000 in cash. That is the barrier the program was built to lower, and the reason Paseyro’s ministry is pairing the credit with a subsidy of up to 50% of the monthly installment.

The subsidy is not automatic, and both sources are explicit on this point. Presidencia Uruguay states eligibility depends on each household’s income and situation; El Observador reports the benefit depends on each household’s economic characteristics, and that not all successful applicants will receive the maximum 50% subsidy. Here is the math an applicant should internalize: the headline figures are ceilings, not entitlements.
Income Floors Drop Sharply Outside Coastal Markets
The geographic split in the income bands is the sharpest signal in the filing. In Maldonado and Ciudad de la Costa—the country’s high-priced coastal markets—required household incomes run from 77,000 to 146,000 pesos.
In the rest of the country, the floor drops to 58,000 pesos. The ceiling holds at 146,000 pesos nationwide, which means the same upper-income limit governs eligibility regardless of where the buyer is shopping, even though property prices clearly do not behave that way.
Loan caps track the same geography: approximately $117,000 in Montevideo, Maldonado and Ciudad de la Costa, against roughly $97,000 everywhere else—a sizable spread between the premium zones and the rest of the country.El Observador’s report adds a caveat that applies in both zones: approval and final amounts depend on the BHU’s credit evaluation and the conditions of the specific property, with the state bank responsible for appraising and verifying the home.
A Lottery, Not a Queue
Demand will almost certainly exceed supply, and the program has already built that expectation into its mechanics. The 500 loans will be distributed across Uruguay’s 19 departments according to how many qualifying applications each department generates. If eligible applications outnumber the available slots in any given department, Presidencia Uruguay reports, a proportional lottery will decide among qualifying registrants in that department.
What qualifies? Households can be single-person or multi-member, with a maximum of two loan holders. Applicants must meet the published conditions on age, income, work seniority, prior savings and credit evaluation set out in the call’s terms, per the ministry.
The property must be an existing or used home on the real estate market, located in the department where the applicant registers—a restriction that directly tags eligibility to geography, not just to price.
Who This Program Actually Reaches
Strip away the programspeak and the borrower profile is narrow and deliberate: a household earning between 58,000 and 146,000 pesos (or 77,000 to 146,000 in the coastal zones), with enough formal work history and credit standing to clear BHU underwriting, and savings of only 5%—a far smaller upfront sum than the down payment conventional mortgage underwriting typically demands.
That is the middle of the income distribution, explicitly excluded from targeted social-housing support but priced out of a standard financing structure.
Whether the 25-year UI term is protective or costly depends on where inflation and wage growth actually go over that horizon, something no source in this reporting addresses. What is verifiable: the debt is indexed, so the real monthly burden tracks Uruguayan wage dynamics rather than long-term nominal interest-rate risk.
How to Apply Before the November 30 Deadline
Registration is exclusively online, through the Ministry of Housing’s website, and closes at the end of Monday, November 30, 2026. There is no walk-in path; Presidencia Uruguay and El Observador both describe the same single channel. For questions on requirements and documentation, the ministry operates the toll-free line 0800 46427.
The window runs twelve days from this publication. Applicants who miss it should expect the program to recur under the quinquennial target of 1,600 loans, but this call’s allocation is fixed at 500, and the departmental distribution will only be settled once qualifying applications are counted and, where needed, the proportional draw is run.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute financial advice.
