
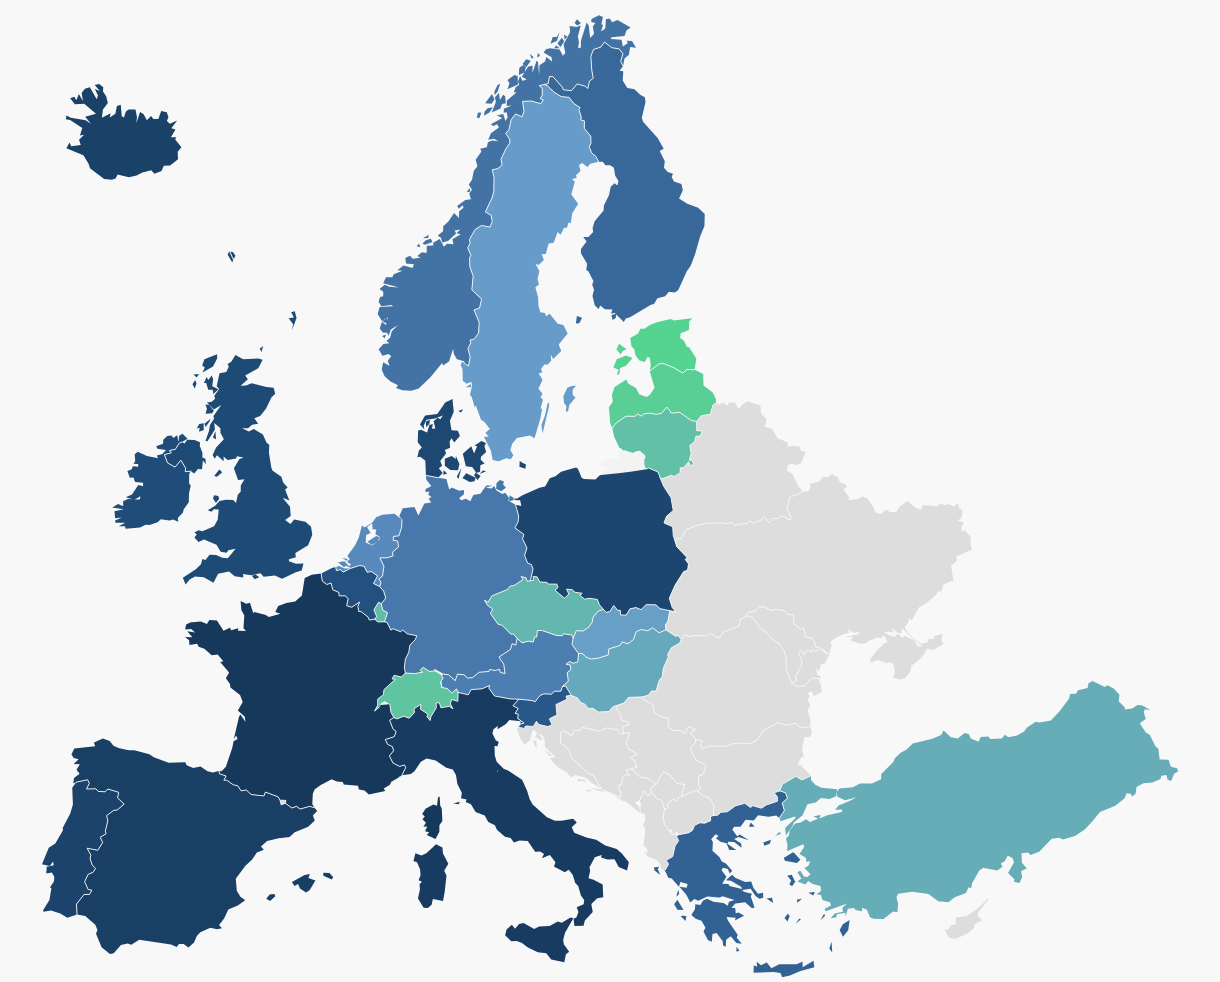
For the 13th year in a row, Estonia claims the top spot for the most competitive tax code in the Organisation for Economic Co-operation and Development, according to the annual International Tax Competitiveness Index published by the Tax Foundation.
That sustained ranking highlights a stark divide in fiscal policy across the 38 developed economies belonging to the intergovernmental organization established in 1961. While Estonia relies on a streamlined, growth-oriented structure, several other European nations anchor the opposite end of the index due to layers of administrative complexity and heavy levies.
The Four Pillars of Estonia’s Tax Advantage
Estonia’s leading score rests on four distinct structural features of its tax code. First, the country levies a 22 percent tax on corporate income that applies exclusively to distributed profits. Second, it maintains a flat 22 percent individual income tax that does not apply to personal dividend income.
Third, its real estate levy is assessed exclusively on the worth of the land itself, excluding capital and built structures. Finally, the nation on the Baltic Sea utilizes a territorial framework that fully shields international earnings generated by local businesses from domestic duties, subject to minimal limitations.
Other nations secure high marks by excelling in specific tax categories rather than a comprehensive model. Latvia, which recently adopted the Estonian framework for corporate taxation, maintains an efficient system for taxing labor income. New Zealand pairs a flat, low-rate individual income tax with a broad-based VAT while levying no taxes on inheritance, property transfers, assets, or financial transactions. Switzerland combines a competitive 19.5 percent corporate tax rate with a low, broad-based consumption tax and partial capital gains exemptions. Lithuania levies a 17 percent corporate tax, allows businesses to fully expense capital investments in machinery, equipment, and intangible rights, and applies a flat, low-rate individual income tax.
France and the Lower Ranks
At the opposite end of the spectrum, France ranks as the least competitive tax system in the OECD. The country combines the highest top corporate tax rate in the OECD at 36.1 percent—incorporating multiple surtaxes and distortive production taxes—with distortive property taxes, separate levies on estates, bank assets, and financial transactions, and a wealth tax on real estate.
Countries trailing at the bottom of the index share common structural traits. Four of the lowest-ranking five nations impose higher-than-average combined corporate tax rates alongside unusually narrow VAT bases that cover only 35 to 50 percent of final consumption.
| Country | Key Tax Feature | Primary Competitiveness Factor |
|---|---|---|
| Estonia | 22% corporate tax on distributed profits only | Top-ranked tax code for 13 years |
| Latvia | Adopted Estonian corporate tax model | Efficient labor income taxation |
| Switzerland | 19.5% corporate tax rate | Low, broad-based consumption tax |
| France | 36.1% top corporate tax rate | Lowest-ranking OECD tax system with wealth and production taxes |
Those same jurisdictions tend to rely heavily on distortive taxes, with four of the bottom five applying digital services taxes, financial transaction taxes, and inheritance taxes alongside wealth or capital duties. The Tax Foundation, a Washington, DC think tank founded in 1937 by a group of business leaders to monitor the tax and spending policies of government agencies, notes that these layered burdens contribute to complexity.
