
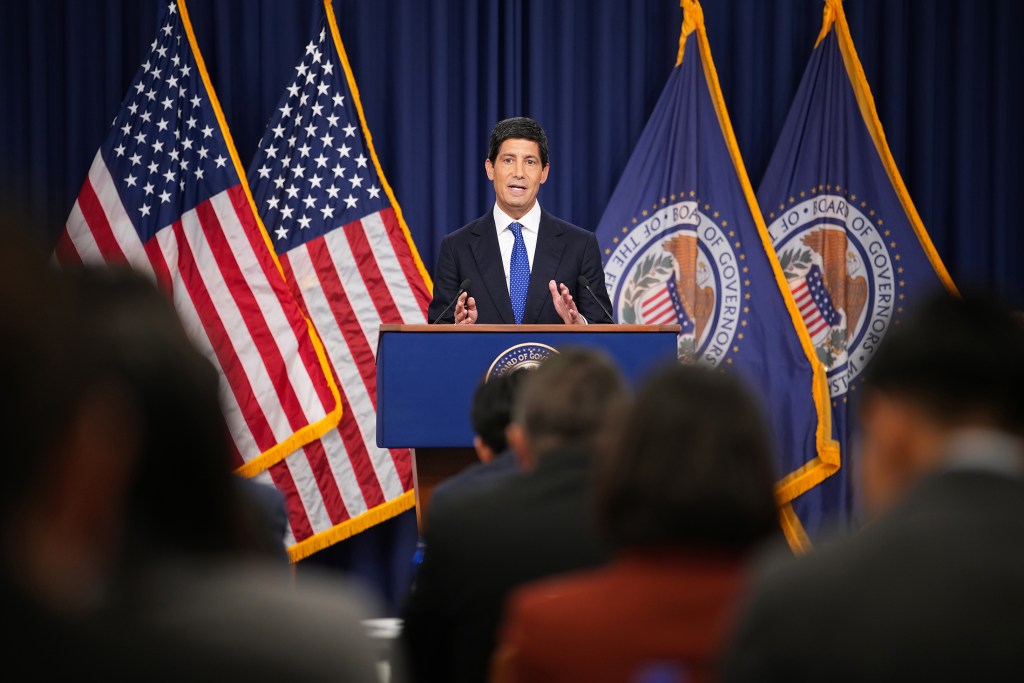
The Federal Reserve raised its benchmark interest rate by a quarter of a percentage point, lifting the target range to 3.75% to 4%. Approved unanimously by the Federal Open Market Committee, the move responds to persistent inflation. Borrowers face immediate shifts in variable-rate loans, while fixed-rate debt remains untouched.
The Bottom Line
- Benchmark Shift: The Fed raised rates to a range of 3.75% to 4%, marking the first increase since July 2023.
- Borrowing Impact: Fixed-rate mortgages remain locked at current levels, but variable-rate loans, car financing, and credit card APRs face upward pressure.
- Savers’ Advantage: High-yield savings accounts and certificates of deposit (CDs) offer incrementally better returns for cash holders.
Decoding the Federal Reserve Policy Shift
When the Federal Open Market Committee announced its unanimous decision to lift the benchmark rate by 25 basis points, financial markets reacted swiftly. Fed Chair Kevin Warsh addressed the move directly, stating according to the New York Times, “The plain fact is that inflation is too high and has been for too long.” This adjustment breaks a prolonged pause in monetary policy that began in the summer of 2023.
Here is the math. The Federal Reserve does not directly dictate retail consumer loan products. Instead, it adjusts the federal funds rate, which ripples outward through the entire banking system.
How Different Debt Instruments React to the New Baseline
The practical fallout of this monetary tightening depends entirely on the structure of your liabilities. If you hold a fixed-rate mortgage, your financial obligations remain completely insulated. That rate is locked for the life of the loan. But the balance sheet tells a different story for variable-rate products.
Adjustable-rate mortgages and other variable-rate loans are directly exposed to these rate adjustments. Furthermore, broader mortgage pricing connects heavily to long-term debt instruments. Treasury bond yields recently crossed the 5% threshold for the first time since 2023, driving the average 30-year fixed mortgage rate to 6.76%, according to reporting from the Washington Post.
Automotive financing costs are also shifting upward. Industry data from Cox Automotive indicates that the latest rate adjustment will tack approximately $6 onto the average monthly car payment for new buyers. Meanwhile, credit card annual percentage rates are tracking higher in lockstep with the federal funds rate, compounding the pressure on households carrying balances near all-time highs.
| Financial Product | Rate Mechanism | Current Market Impact |
|---|---|---|
| Federal Funds Rate | Set by FOMC | Raised to 3.75% – 4% range |
| 30-Year Fixed Mortgage | Tied to Treasury Yields | Averaging 6.76% amid 5% bond yields |
| Auto Loans | Variable/Fixed Retail | Adds ~$6 to average monthly payment |
| High-Yield Savings | Deposit Yields | Delivering improved returns for savers |
The Silver Lining for Capital Savers
While borrowers absorb heavier monthly outlays, the shifting monetary environment benefits net savers. Banking institutions are gradually adjusting yields upward on liquid cash vehicles. High-yield savings accounts and certificates of deposit now offer comparatively stronger returns than they did during the prolonged low-rate era.
As principal consumer finance analyst Ted Rossman of Money Management International noted to the Washington Post, “I know a rate hike may feel like bitter medicine, but we need it because we can’t just keep having this runaway price growth.”
Strategic Outlook for Households and Businesses
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute financial advice.
