
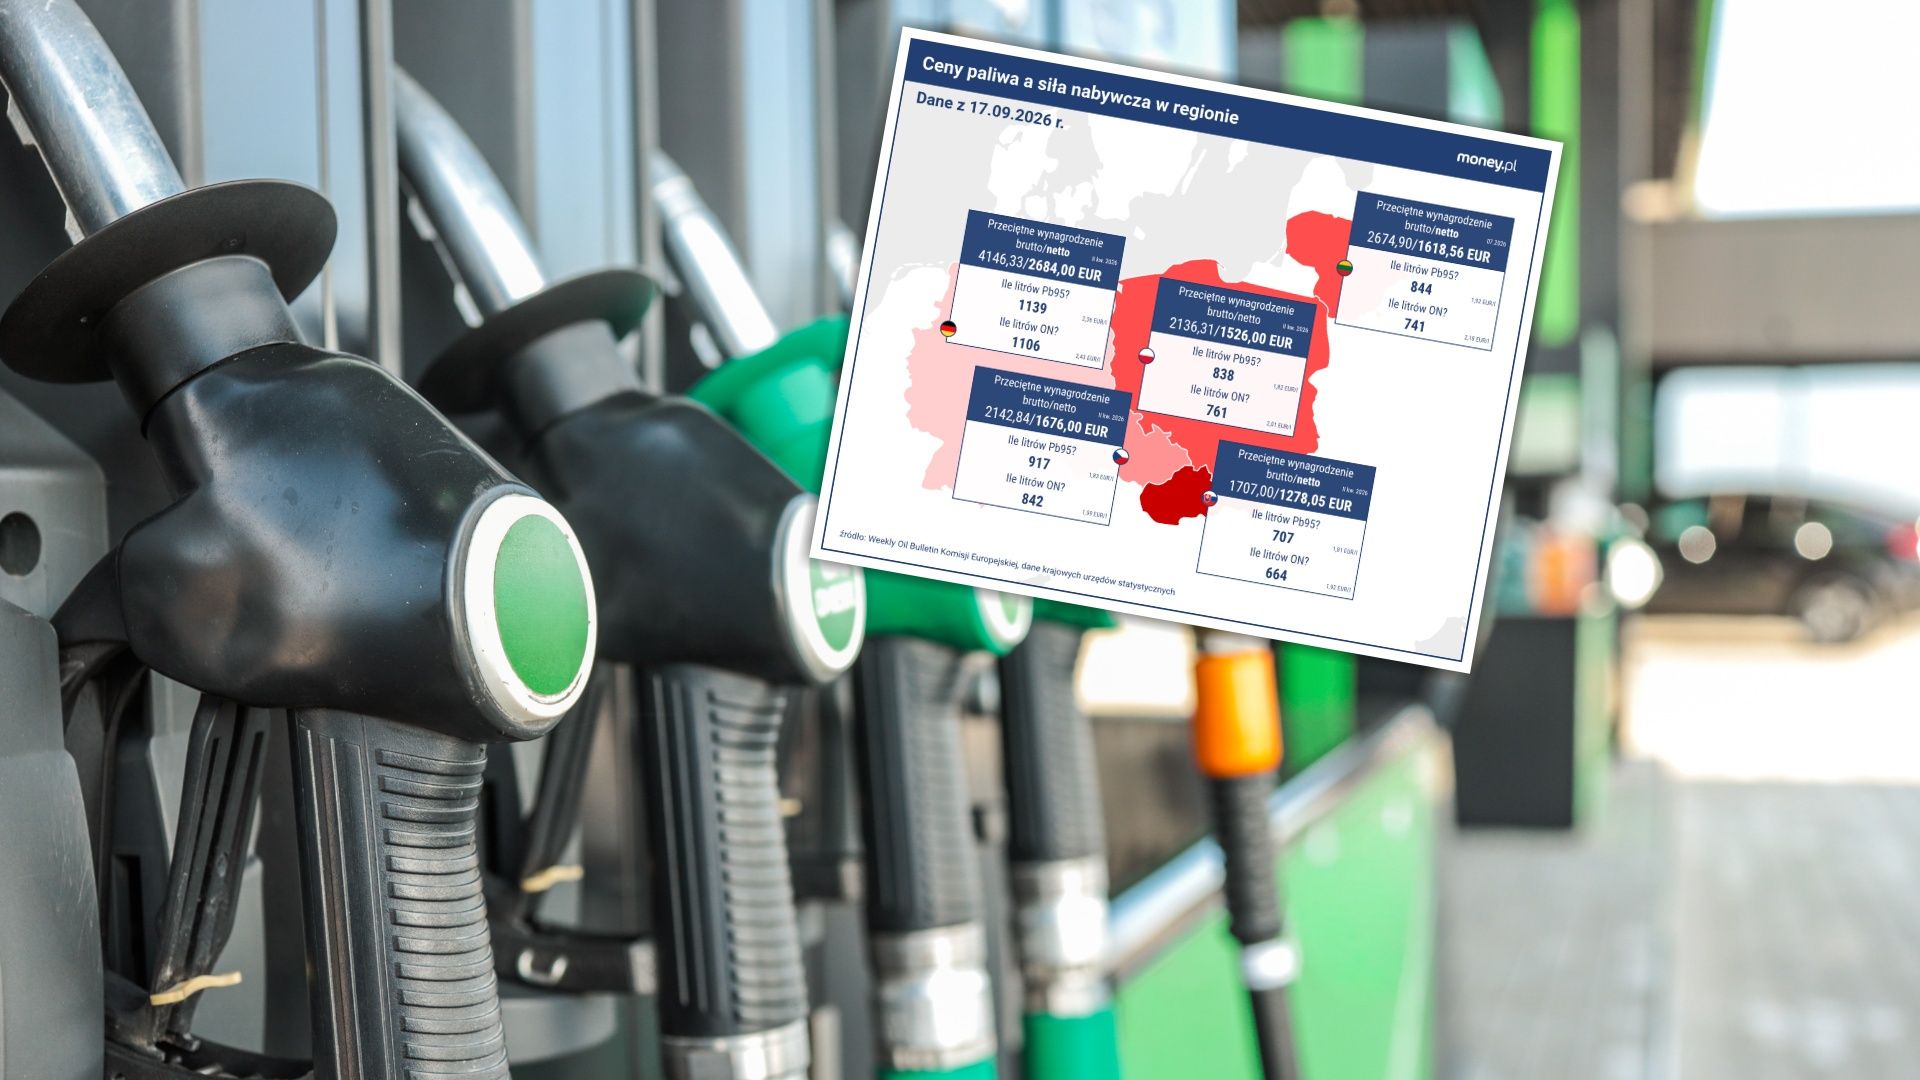
As retail fuel costs in Poland push past 8 zł for gasoline Pb95 and break the 9 zł threshold for diesel, recent European Commission data from September 2026 reveals that purchasing power parity drastically alters the reality of these high prices compared to neighboring EU economies.
Here is the math. While nominal fuel prices in Poland sit at 1.82 euro for gasoline and 2.01 euro for diesel per liter, the broader economic picture requires a deep dive into net wages, refining margins, and looming political intervention. But the balance sheet tells a different story once consumer purchasing power enters the equation.
The Bottom Line
- Purchasing Power Reality: Despite higher nominal prices, the average German net salary secures 1,139 liters of gasoline, outpacing the 838 liters accessible to an average Polish earner.
- Threshold Breaches: Polish retail prices have crossed psychological barriers of 8 zł for Pb95 and 9 zł for diesel, driven by surging wholesale costs across European markets.
- In response to expired state relief packages that previously cost the state budget a multi-billion-zloty footprint, the political opposition and executive branches are weighing aggressive retail margin caps and excise cuts.
European Fuel Price Divergence and Regional Rankings
According to data published by the European Commission via the Weekly Oil Bulletin, average fuel prices across member states point to a heavily fractured market. Across the European Union, benchmark prices settle at 2.06 euro per liter for gasoline Pb95 and 2.16 euro per liter for diesel. Malta anchors the lower end of the spectrum with gasoline at 1.34 euro and diesel at 1.21 euro per liter. Conversely, Denmark records the highest retail fuel costs in the bloc, with gasoline at 2.56 euro and diesel at 2.50 euro per liter.
Within Central Europe and immediate neighbors, the pricing landscape varies sharply. In Germany, gasoline costs 2.36 euro and diesel reaches 2.43 euro per liter. According to reporting on regional pressures, the government in Berlin faces difficult choices regarding targeted relief funded by taxpayers versus potential political fallout ahead of regional elections in Berlin and Mecklenburg-Vorpommern. Meanwhile, Slovakia records the lowest prices in the immediate region at 1.81 euro for gasoline and 1.92 euro for diesel, positioning it just below Poland’s averages.
| Country | Gasoline Pb95 (EUR/L) | Diesel (EUR/L) | Purchasing Power (Liters of Pb95) | Purchasing Power (Liters of Diesel) |
|---|---|---|---|---|
| Germany | 2.36 | 2.43 | 1,139 | 1,106 |
| Czech Republic | 917 | 842 | ||
| Lithuania | 844 | 741 | ||
| Poland | 1.82 | 2.01 | 838 | 761 |
| Slovakia | 1.81 | 1.92 | 707 | 664 |
Net Wages Versus Pump Prices
Examining these nominal prices in isolation distorts the actual financial burden on households. By mapping national net average wages from official statistical offices—reflecting Q2 2026 data alongside July figures for Lithuania—against September 17 fuel benchmarks, a clearer picture of consumer resilience emerges. An average earner in Poland commands enough purchasing power to acquire 838 liters of gasoline Pb95 or 761 liters of diesel. Lithuania displays a near-identical metric at 844 liters of gasoline and 741 liters of diesel.
Czech consumers fare slightly higher, with average earnings covering 917 liters of gasoline and 842 liters of diesel. Paradoxically, German consumers, who face the steepest prices in the region, maintain the highest purchasing power in this cohort at 1,139 liters of gasoline and 1,106 liters of diesel due to substantially higher average net wages. Conversely, Slovaks benefit from the lowest regional prices yet face the lowest purchasing power, with average salaries yielding only 707 liters of gasoline and 664 liters of diesel.
Wholesale Pressures and Regulatory Interventions
The domestic pricing environment in Poland is increasingly dictated by external commodity shifts. Wholesale fuel costs climbed steadily through the preceding weeks, placing acute upward pressure on diesel margins. Urszula Cieślak, an analyst at the Reflex bureau, noted that while psychological thresholds of 8 zł and 9 zł have been breached, catastrophic projections heading toward 10 zł per liter remain unlikely absent severe supply shocks. However, sustained high prices generate elevated VAT inflows for public finances, fueling public debate over state intervention.
The expiration of the government’s temporary “CPN – Ceny Paliwa Niżej” package at the end of August—which encompassed reduced excise duties, a VAT reduction, and maximum price mechanisms—left a substantial footprint on the state budget across its operational windows. While the administration of Donald Tusk’s frameworks sought to fund relief via a windfall tax on energy majors, that legislative mechanism faced delays after being referred to the Constitutional Tribunal by President Karol Nawrocki.
Adding to the legislative friction, the Sejm anticipates a new presidential bill dubbed the “PKN” (“Paliwo kosztuje normalnie”) act. Spearheaded by presidential cabinet chief Paweł Szefernaker, the proposed legislation aims to exempt fuel sales from retail sales taxes, institute statutory caps on refining margins, and restore the finance minister’s authority to flexibly reduce fuel excise duties.
Macroeconomic Outlook and Market Trajectory
As international crude benchmarks fluctuate, the interplay between corporate refining margins and fiscal policy will dictate the near-term trajectory of transport overheads. For logistics operators and consumer-facing businesses, sustained diesel elevation translates directly into sticky core inflation metrics. Equity analysts monitoring regional refining assets must balance these regulatory headwinds against underlying demand destruction risks as consumers adjust driving habits to match real wage growth.
