
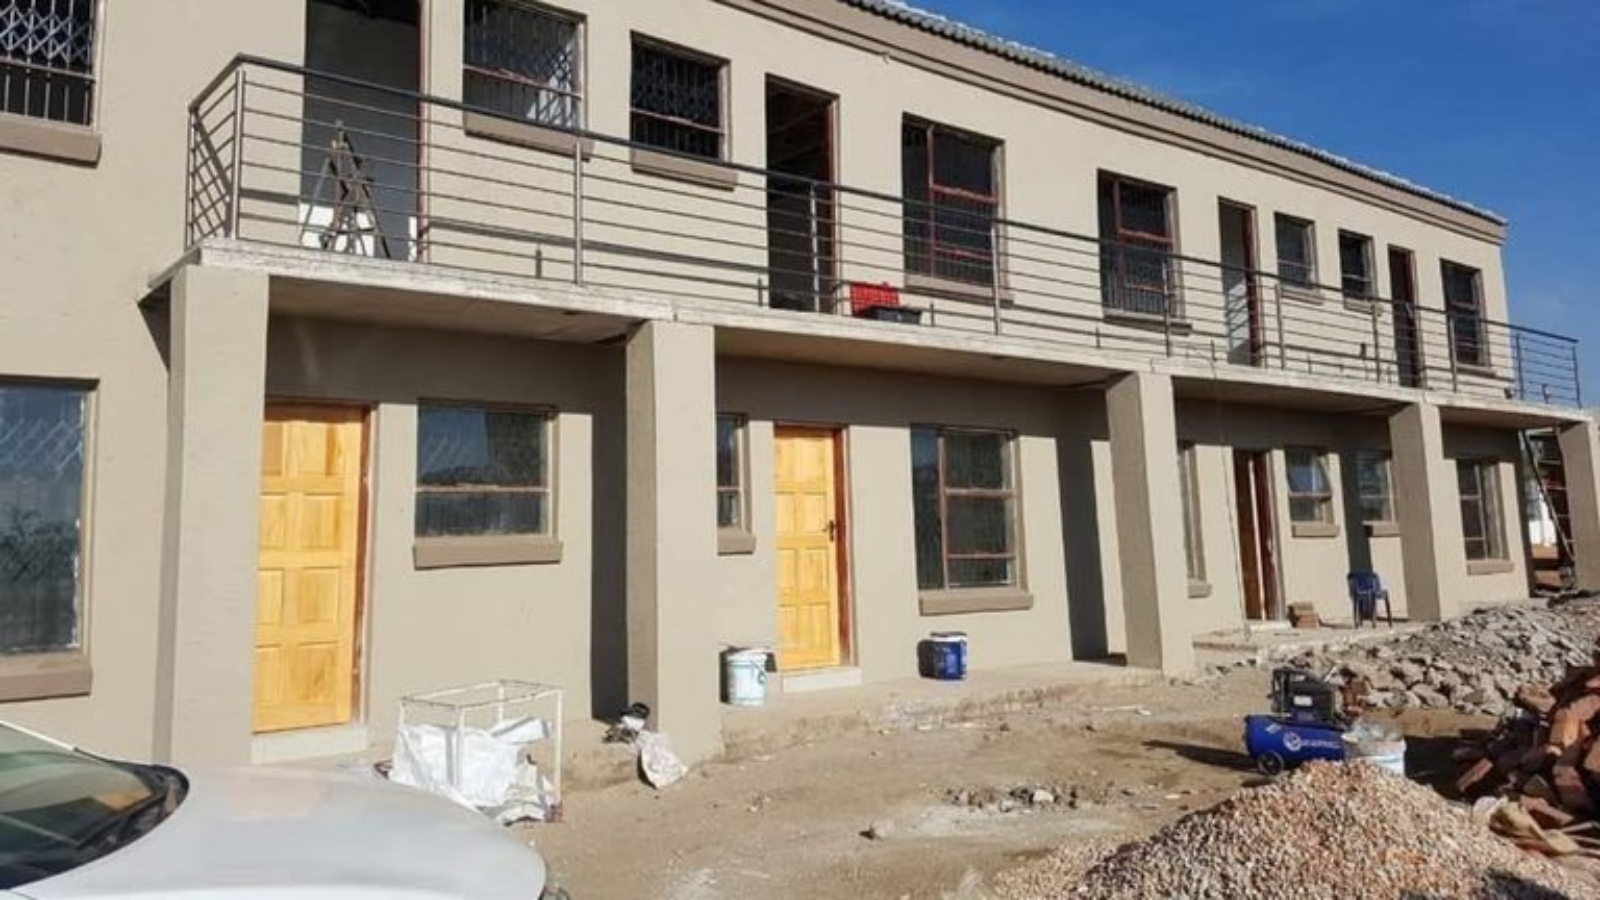
A South African entrepreneur in Soweto generates R75,000 per month by renting out 25 backroom units across two properties in Protea. Despite this consistent revenue stream, commercial banks rejected her R1.5 million financing application for student housing development due to a structural lack of data within the informal real estate market.
The Bottom Line
- Monthly Cash Flow: Rental operations across 25 units bring in R75,000, deposited directly into a standard commercial bank account alongside formal salary income.
- Financing Friction: Traditional lenders denied a R1.5 million commercial real estate loan, citing a lack of formal property valuation data, while approving a R1.3 million vehicle loan within 20 minutes.
- Macroeconomic Scale: Informal economy experts estimate South Africa’s township rental sector at R30 billion annually, highlighting a massive unserviced credit market.
Soweto Rental Expansion and the R75,000 Cash Flow
Nthabiseng, a township entrepreneur featured in reporting by Daily Investor, built her real estate portfolio incrementally. Her initial project in Protea involved dividing space within her primary residence to construct 14 high-quality backroom rental units. These spaces were priced between R2,500 and R3,000 per month, generating a baseline income of R40,000.
During the COVID-19 pandemic, she reinvested capital from her first venture to acquire a second property in Protea. On this land, she built 11 additional rooms, renting each out for R3,000 monthly. Combined with her formal employment earnings, this portfolio pushes R75,000 in monthly rental income directly through her personal banking channels.
Commercial Lending Barriers in the Township Economy
Seeking to scale into the student housing sector, Nthabiseng acquired a property in Pimville in cash. To fund the construction of 31 planned units, she submitted a R1.5 million loan application to her bank, presenting three months of statements and earnings proof from her existing rental operations.
After a three-week review period, the financial institution rejected the request. According to informal economy expert GG Alcock, the bank stated, “We don’t believe this has real estate value,” as Daily Investor reported. To test the institution’s credit assessment metrics, Nthabiseng applied for a R1.3 million vehicle loan for a Mercedes-Benz, which the same bank approved in 20 minutes.
| Project Phase | Location | Units Built | Monthly Revenue | Financing Outcome |
|---|---|---|---|---|
| Phase 1 | Protea | 14 Units | R40,000 | Funded via personal capital |
| Phase 3 | Pimville | 31 Units (Planned) | Projected | R1.5 Million Loan Rejected |
Data Gaps and the R30 Billion Township Market
The core bottleneck in scaling township real estate is not a lack of liquidity or borrower default risk, but a severe data deficit within formal banking institutions. Alcock noted that banks lack empirical models to evaluate informal urban real estate, leaving entrepreneurs who generate substantial cash flows entirely unserviced by business credit products.
This systemic blind spot affects a broader R1 trillion informal economy across South Africa. While conventional policy often focuses on venture capital for new startups, existing township enterprises operate at scale without government support. Alcock argued that regulatory bodies and financial institutions must adapt their risk frameworks to formalize and finance these established micro-economies rather than attempting to build new markets from scratch.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute financial advice.
