
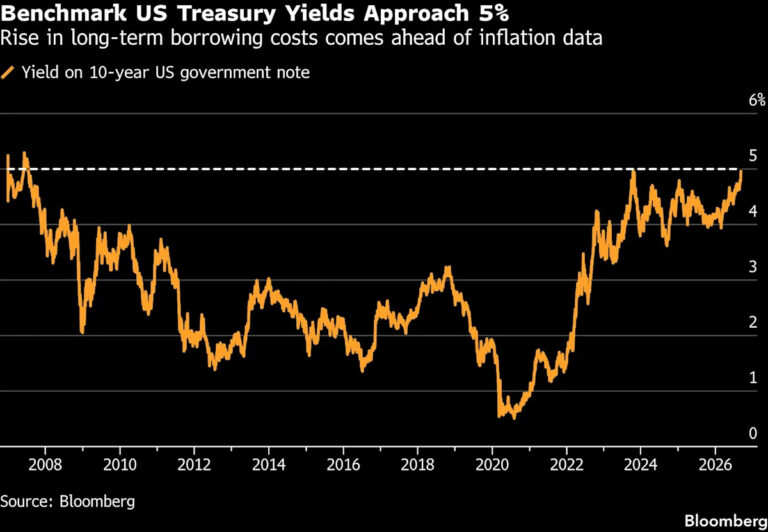
Government borrowing costs surged to their highest levels since the 2008 financial crisis on Tuesday, September 15, 2026, as 10-year U.S. Treasury yields pushed above 5%, intensifying fiscal pressure on indebted nations and rattling global financial markets.
Global bond markets faced a punishing selloff as benchmark yields breached critical psychological thresholds. The 10-year U.S. Treasury yield climbed past the 5% mark to hit 5.041% early Tuesday morning, according to Reuters, marking its most elevated position since 2007. The widening economic fallout from conflict in the Middle East has driven oil prices back above $100 a barrel, placing renewed pressure on central banks to raise interest rates to tackle inflation.
Global G7 Yields and International Debt Pressures
The turmoil has stretched far beyond American shores. The average 10-year yield for the Group of Seven largest economies climbed to 4.285%, representing its highest level since mid-2008 and sitting a full percentage point above pre-conflict figures. In the United Kingdom, 10-year yields reached 5.45%, also touching peaks not seen since 2007, while French benchmark yields hovered near an 18-year high. Meanwhile, Germany’s 10-year yield sat near 3.55%, its highest mark since 2009, as reported by Reuters.
Asian markets mirrored the distress. Japan’s 10-year government bond yield hit a three-decade high above 3%, according to Reuters, while Australian benchmark yields climbed to their highest point since 2011, noted finance.yahoo.com. These rising borrowing costs are actively expanding interest payments for sovereign governments, siphoning critical funds away from defense, social programs, and other programmes.
Central Bank Shifts and the Kevin Warsh Factor
As inflation remains stubbornly above central bank targets, monetary policymakers are shifting their postures. Money markets are pricing in a Federal Reserve rate hike to 3.75% to 4% on Wednesday, alongside expectations that the Bank of Japan will hike rates and the European Central Bank may implement further tightening. Market participants are also adjusting to a new style of monetary governance under Federal Reserve Chair Kevin Warsh.
All central banks are now following this new era of no forward guidance, just building up credibility and trust. And as you can see now in the bond markets, that currently isn’t working.
Shriya Samarth, head of EMEA rates at market maker StoneX, via Reuters
Samarth pointed to broader macroeconomic strains compounding the selloff, noting that heavy artificial intelligence capital expenditure demands, widespread fiscal anxiety, U.S. debt reaching $40 trillion, and historic high debt-to-GDP ratios across the UK and the eurozone are adding severe complications to sovereign debt sustainability.
Treasury Challenges and Market Circuit Breakers
For the $32 trillion U.S. Treasuries market, pushing past the 5% threshold presents an acute political and administrative test for Treasury Secretary Scott Bessent. Bessent’s department has attempted to stem the bleeding through interventions, including joint efforts to buy the yen to deter Japanese liquidations of U.S. paper and expanding government bond buybacks. However, during an expanded buyback operation, the Treasury Department purchased fewer bonds than expected.

Higher yields directly dictate the cost of capital across the broader economy, driving U.S. mortgage rates to their highest levels in over a year—a politically sensitive metric for voters ahead of upcoming midterm elections. Equity markets are increasingly vulnerable to these adjustments as well. While strong corporate earnings fueled by artificial intelligence infrastructure spending have cushioned equities so far, analysts warn that further yield escalation could provoke a sharper repricing.
A lower US CPI and a Fed hike are really the only circuit breakers I see at this point, otherwise I don’t think anyone is comfortable being long rates. It’s just massive hawkish sentiment taking over.
Michael Tang, rates strategist at Commonwealth Bank of Australia in Sydney, via finance.yahoo.com
Economic Growth Realities Versus Yield Realities
The overarching debate among economists centers on whether modern economic growth can comfortably absorb borrowing costs at this altitude. While the U.S. economy has displayed notable resilience, other international borrowers are poorly positioned to manage sustained 5% benchmarks.
Yields at 5% aren’t a problem if you’re growing 6.5%. But if you’re growing 5% with yields at 5%, that might be a different story.
Samy Chaar, chief economist at Lombard Odier, via Reuters
With incoming inflation data set to dictate whether central banks lock in additional tightening, market participants remain on edge. Analysts at ING Groep NV note that reaching the 5% milestone on the 10-year note has transformed from a cautious forecast into an immediate operational reality for global debt desks.
