
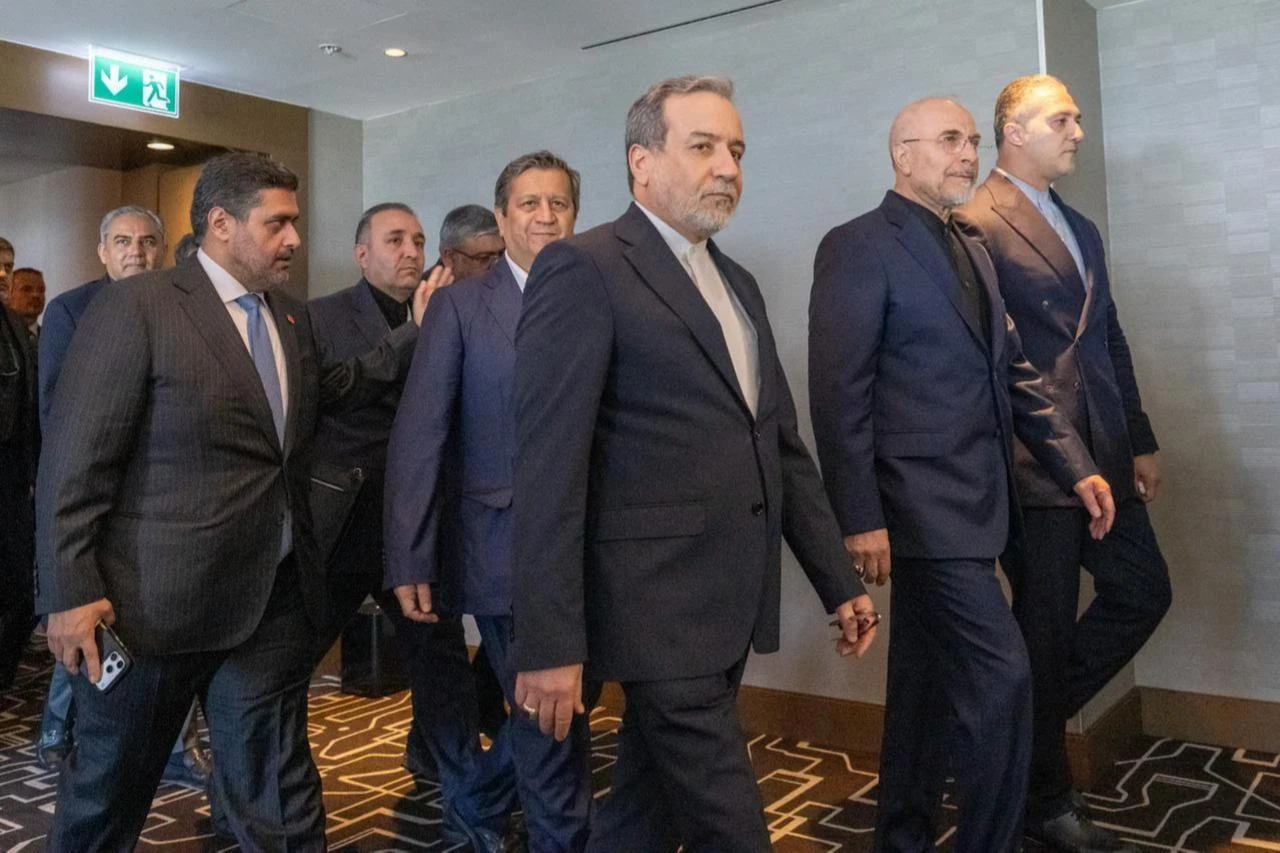
Diplomatic Calibrations: Assessing the 10% Probability Threshold in Iran-U.S. Relations
Iranian Foreign Minister Abbas Araghchi stated on July 19, 2026, that pursuing diplomatic channels with the United States remained a rational strategic choice, even when the probability of success was assessed at a marginal 10%. This admission highlights the high-stakes risk management governing Middle Eastern geopolitical negotiations and their subsequent impact on global energy markets.
The Bottom Line
- Risk-Adjusted Diplomacy: Tehran’s formal acknowledgment of a 10% success probability suggests a shift toward “option-value” diplomacy, where maintaining a seat at the table is prioritized over immediate breakthrough outcomes.
- Energy Market Volatility: With crude oil benchmarks sensitive to Iranian supply constraints, any shift in diplomatic posture directly dictates volatility premiums for producers like Chevron (NYSE: CVX) and ExxonMobil (NYSE: XOM).
- Sanctions Compliance: For multinational firms, the ambiguity of these negotiations necessitates a “wait-and-see” approach to capital expenditure in the region, as sudden policy reversals could trigger rapid compliance re-evaluations.
The Mathematical Reality of Geopolitical Risk
In the language of institutional finance, Araghchi’s 10% figure is not merely a diplomatic sentiment; it is a calculation of expected value. When states engage in negotiations with low-probability outcomes, the “payoff” is often not the deal itself, but the mitigation of tail-risk events—such as kinetic conflict or further tightening of international sanctions. According to analysis from the Council on Foreign Relations, the persistence of these talks serves to anchor expectations, preventing the total collapse of the 2015 Joint Comprehensive Plan of Action (JCPOA) framework.
But the balance sheet tells a different story. While diplomats weigh probabilities, the market is pricing in structural supply constraints. Iran’s current export capacity remains heavily hampered by U.S. secondary sanctions, which have effectively partitioned the nation’s output from the global financial system. As noted by the International Energy Agency (IEA), Iranian production figures remain a primary “wildcard” variable in global supply-demand models for the second half of 2026.
Strategic Implications for Global Energy Infrastructure
Here is the math: If diplomatic efforts were to yield a 100% success rate, the potential influx of Iranian crude could theoretically depress Brent Crude prices by 5% to 8% within a single fiscal quarter. However, with the current 10% success probability, institutional investors are largely ignoring the “relief rally” scenario. Instead, they are focusing on the fiscal health of regional competitors.
| Metric | Status / Impact |
|---|---|
| Current Success Probability | 10% (Per Official Statement) |
| Oil Price Sensitivity | High (Inverse correlation to Iranian exports) |
| Primary Market Risk | Supply chain disruption in the Strait of Hormuz |
| Institutional Outlook | Neutral-Bearish on near-term diplomatic breakthrough |
According to Bloomberg Energy, the inability to reach a durable agreement forces companies like BP (NYSE: BP) and Shell (NYSE: SHEL) to maintain higher cash reserves to hedge against sudden regional instability. The cost of this hedging, while difficult to isolate, is reflected in the wider bid-ask spreads on energy-related derivatives.
Expert Perspectives on Diplomatic Utility
Financial analysts argue that the “10% threshold” is a classic example of sunk-cost management. By remaining at the table, Iran maintains a degree of international legitimacy that is essential for its limited trade with non-Western partners.
As one senior strategist at a major investment bank noted: “Diplomacy in this context is not about the probability of a signing ceremony; it is about the cost of total isolation. At a 10% success rate, the ‘insurance policy’ of keeping communication lines open is cheaper than the alternative of total systemic exclusion.”
The Reuters Energy Desk has highlighted that until these diplomatic efforts move beyond the current impasse, the market will continue to treat Iranian supply as a “black box.” This uncertainty creates a persistent risk premium that benefits non-OPEC producers, who can operate with greater predictability in the current price environment.
Future Market Trajectory
As we move toward the close of Q3 2026, the focus will remain on whether the 10% probability shifts toward 20% or reverts to 0%. For the business owner and the retail investor alike, the lesson is clear: do not bet on a diplomatic breakthrough as a catalyst for market normalization. Instead, continue to model for a high-cost, high-volatility environment where geopolitical risk is a permanent line item on the global balance sheet.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute financial advice.
