
As data challenges four prevailing digital age forecasts regarding media, retail, publishing, and automotive sectors, evidence examines past prophecies. While internet disruption threatened traditional business models over the past three decades, hard revenue figures show legacy formats maintaining surprising dominance, offering vital perspective for portfolio managers and equity analysts tracking consumer discretionary and industrial stocks.
Printed Books and Physical Retail Maintain Market Dominance
- Print Resilience: Printed books retain 73% of total publishing revenue globally, while digital editions capture just 10%, according to recent Association of American Publishers data cited by La Nación.
- E-Commerce Stagnation: Global e-commerce accounts for 21% of worldwide retail sales, leaving physical retail with the vast majority of total transactions as store models evolve.
- Media Monetization: Legacy newspapers successfully transitioned to digital paywalls, reversing early predictions of industry collapse driven by free social media aggregation.
Legacy Publishers Rebuild Cash Flows Through Digital Paywalls
When the iPhone debuted in 2007 and social media platforms scaled rapidly, consensus held that ad-supported print journalism faced imminent liquidation. Free online distribution models threatened to permanently erode profit margins across the publishing sector. Yet, major centennial newspapers pivoted toward subscription models pioneered by digital native peers like Netflix (NASDAQ: NFLX) and Spotify (NYSE: SPOT).
By enforcing digital paywalls and refining user experience frameworks, legacy media houses convinced consumers to pay for rigorous reporting and analytical content. Rather than vanishing into the social media ecosystem, traditional publishers that successfully executed digital multi-platform transitions now report stable subscription revenues and resilient balance sheets.
Print Publishing Dominates the Global Book Market
The November 2007 launch of the Amazon Kindle sparked forecasts that physical books would quickly become obsolete. Semiotician Umberto Eco countered this digital determinism in his 2010 essay, asserting that the bound book belongs to an immutable class of human inventions alongside the wheel and the spoon. Current publishing statistics validate Eco’s thesis across major Western markets.
Data from the Association of American Publishers shows that physical books capture 73% of total industry revenue, whereas electronic books account for a mere 10%, with audiobooks and alternative formats capturing the remainder. Demographic polling indicates that 32% of Americans read exclusively print books, 33% utilize both formats, and only 9% rely solely on e-readers. These metrics confirm that the book market’s capital allocation heavily favors physical inventory.
| Publishing Format | Market Share (Revenue) | Reader Preference (%) |
|---|---|---|
| Print Books | 73% | 32% (Print Only) / 33% (Mixed) |
| E-Books | 10% | 9% (Digital Only) |
| Audiobooks & Other | Remainder | Others |
Physical Retail Retains Market Share Against E-Commerce Expansion
At the onset of the Covid-19 pandemic, market forecasters predicted that lockdowns would permanently shutter brick-and-mortar retail, driving online penetration past 50% globally. E-marketer data indicates that global e-commerce has expanded from 7.5% of total retail sales a decade ago to 21% today. While categories such as consumer electronics and appliances see online penetration hitting 35% to 40%, physical retail continues to capture 8 out of every 10 dollars of global retail sales.
Physical stores responded to digital competition by overhauling operational strategies, enhancing in-store architecture, and integrating omnichannel inventory management. Industry projections indicate that digital retail platforms will capture 25% of the global market by 2030. This growth path demonstrates coexistence rather than the complete displacement of physical shopping malls and supermarkets.
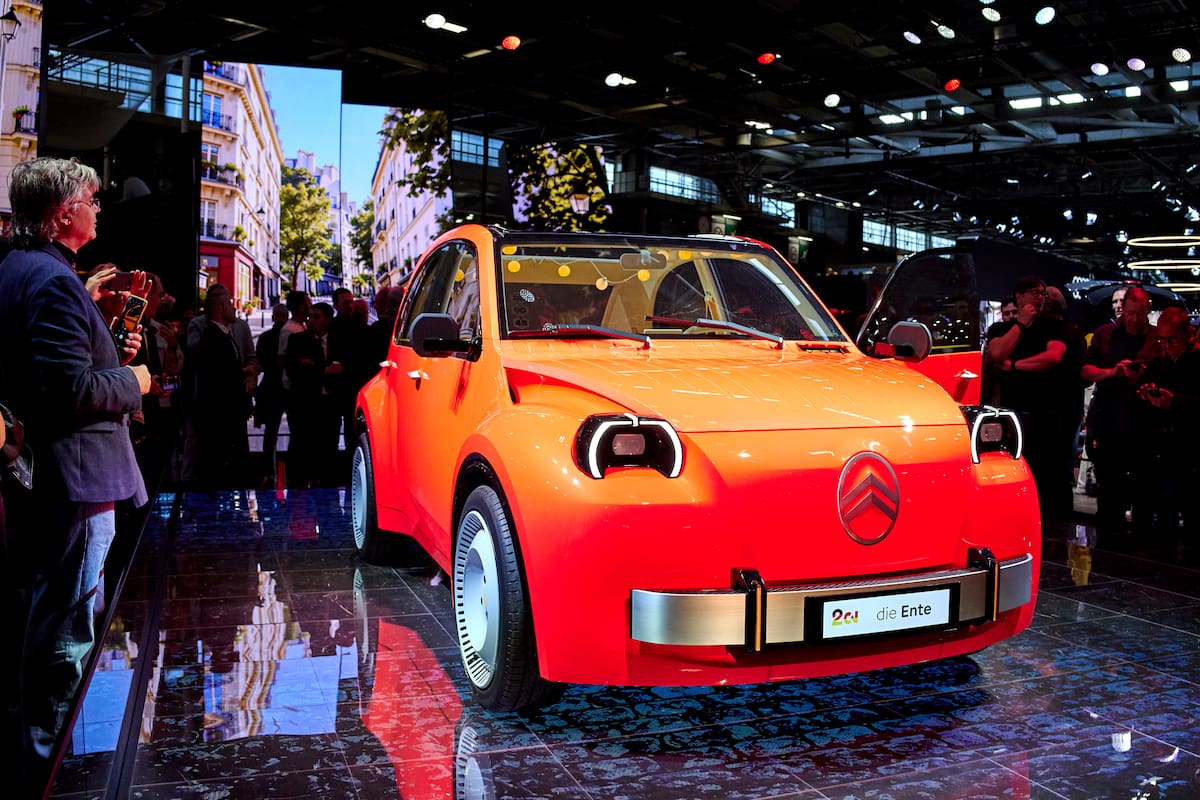
European Manufacturers Defend Market Share Against Chinese Electric Vehicles
The global automotive sector faces a complex transition as electric vehicle adoption accelerates, with Chinese manufacturers like BYD Company (HKG: 1211) scaling production and international distribution.
By pairing historical brand equity with next-generation electric powertrains, European manufacturers aim to defend their market share against low-cost imported alternatives.
