

Nearly 4 million homeowners aged 75 and older were still paying off a mortgage in 2025 — 3.93 million of them, more than double the 1.79 million recorded in 2010, according to a Realtor.com analysis of U.S. Census Bureau data published on Monday.
The share of owners in that age bracket carrying debt climbed from 20.3% in 2010 to 28.7% in 2025, meaning nearly three in ten still owe money on their homes, as Idaho Business Review reported. The count jumped 119% over the period.
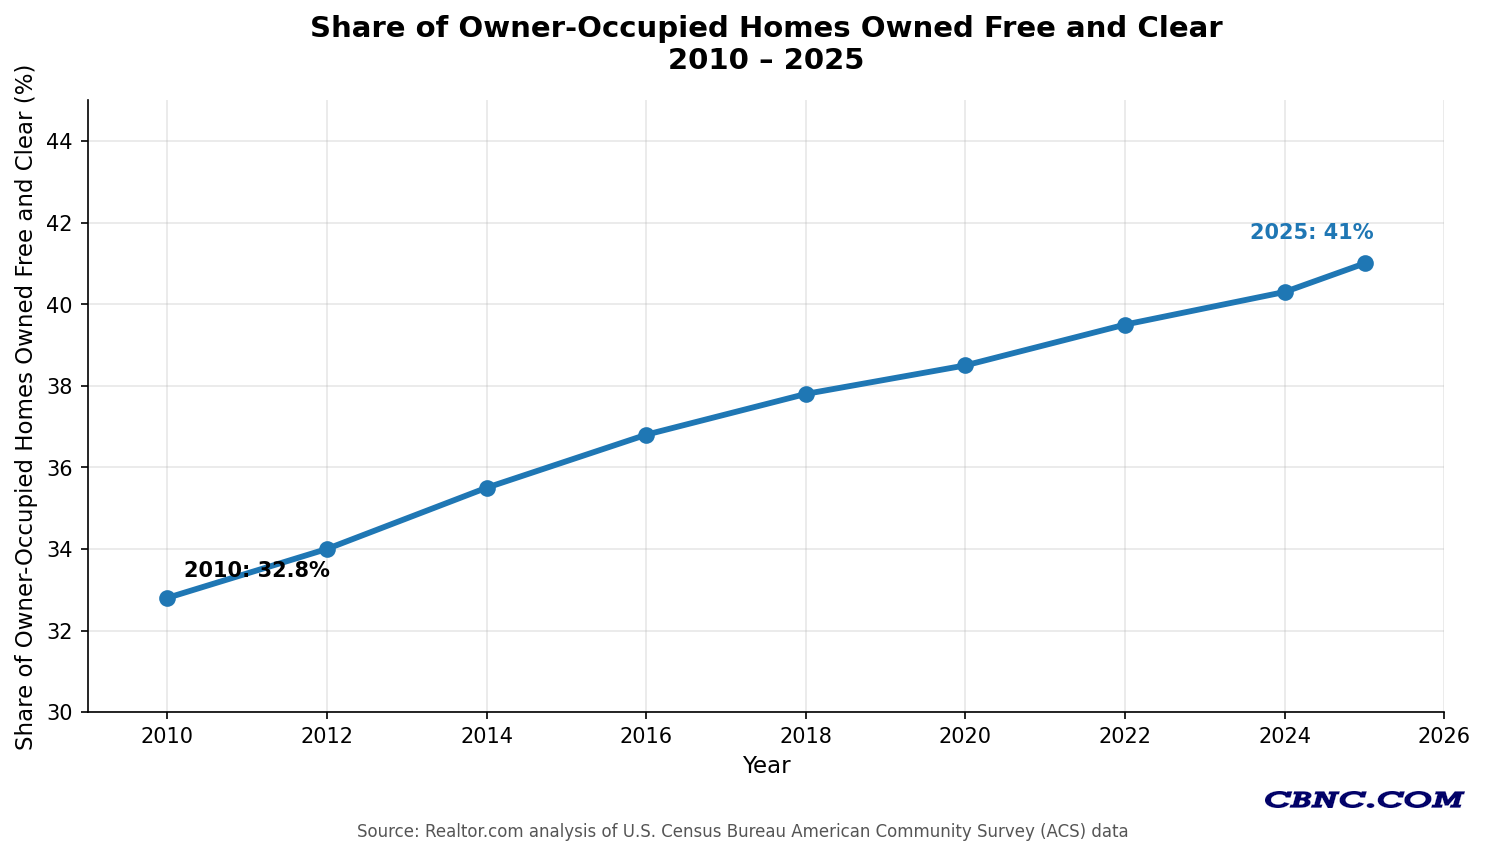
The numbers make this awkward for the housing market: the country as a whole is moving in the opposite direction. The share of owner-occupied homes owned outright rose from 32.8% in 2010 to 41% in 2025, while the share carrying a mortgage fell from 67.2% to 59%.
“Homeowners generally pay off their loans as they age, but some households buy their first home later in life, extending payments into years when earlier generations were more likely to be debt-free,” said Jiayi Xu, a senior economist at Realtor.com. “That is one of several reasons a growing share of older homeowners still carry a mortgage.”
What 3.93 million does to supply
- The debt is aging with the borrower. Median home-secured debt for households 75 and older hit $101,000 in 2025, up roughly 30% from $77,720 in 2010, per Federal Reserve data cited in the report.
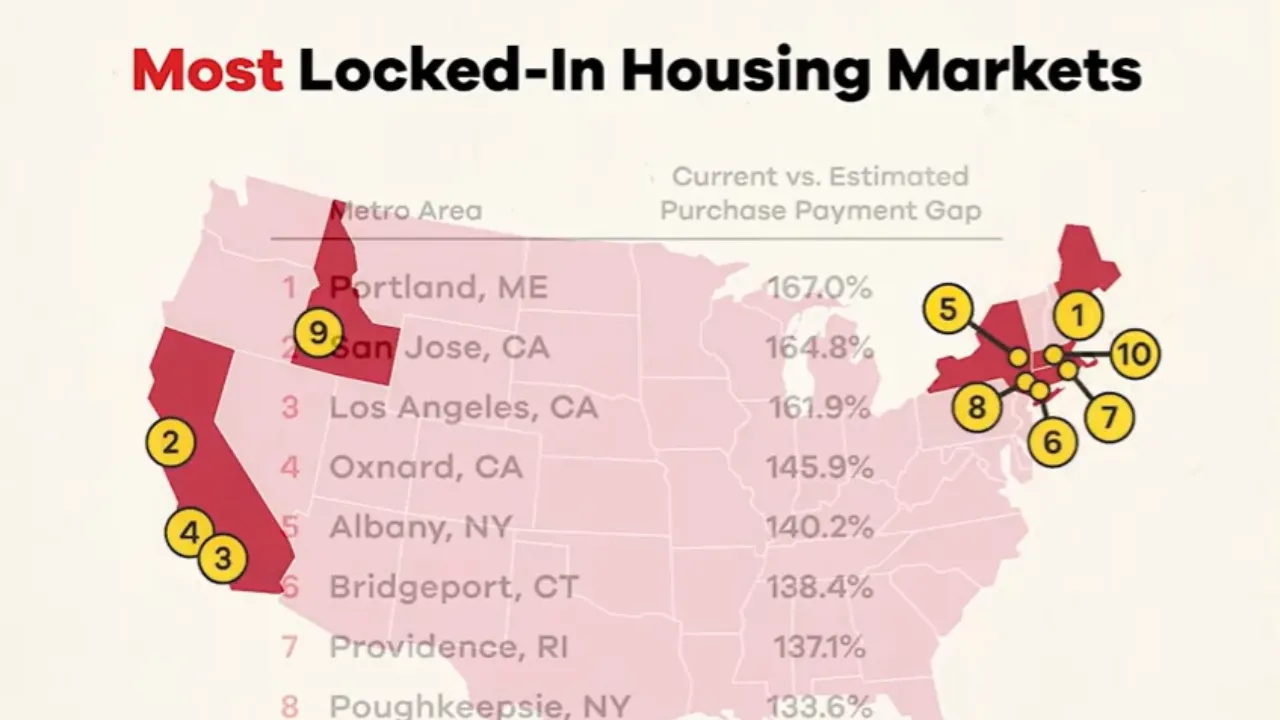
- The lock-in effect now has a price tag. Realtor.com research puts the typical cost of swapping an existing mortgage for a new one at about $1,100 more per month — an 85% jump over a typical $1,300 payment.
- Supply stays tight either way. Owners locked into loans at 3% or lower hesitate to sell into rates above 7%, and owners still paying down debt lack the flexibility of the free-and-clear.
The 119% climb, in four numbers
The analysis, built on the Census Bureau’s 2025 American Community Survey, tracks a fifteen-year divergence between what older owners owe and what everyone else has paid off. The four figures below, compiled from the report and corroborating coverage, tell that story in one view.
| Measure | 2010 | 2025 |
|---|---|---|
| Homeowners 75+ with a mortgage | 1.79 million | 3.93 million |
| Share of 75+ owners with a mortgage | 20.3% | 28.7% |
| All owner-occupied homes owned outright | 32.8% | 41% |
| Median home-secured debt, households 75+ | $77,720 | $101,000 |
Older owners also became homeowners at a higher rate: ownership among households 75 and older climbed from 75.7% to 78.3% over the period. More seniors own homes; fewer of those owners have cleared the lien.
Where the paid-off homes cluster
Geography splits sharply. Among the 50 largest metro areas, Miami led for homes owned outright at 45.9%, followed by Buffalo at 45.6% and Pittsburgh at 45%, Idaho Business Review reported. For seniors specifically, Grand Rapids, Michigan, posted the highest mortgage-free share at 79.2%, with Pittsburgh at 78.4% and Buffalo at 75.6%, according to AOL’s coverage of the study. Riverside, California, sat at the bottom at 55.2%.
On the other side of the ledger, the Washington, D.C. metro led all large metros for homes still carrying a mortgage.
Idaho Business Review put that figure at 73.2%, while CBNC’s write-up of the same analysis reported 73.6% for the metro and 73.5% for the District as the highest share of any state-level jurisdiction. Denver followed at 72.3%, and Raleigh, North Carolina, at 70.6%. West Virginia had the lowest mortgage share in the country at 43.4%, per CBNC.
Idaho sits mid-pack. The Gem State ranked 19th nationally, with 60.5% of homes carrying debt and 39.5% owned outright, Idaho Business Review reported.
The $1,100 penalty for moving
But the balance sheet is only half the story — the other half is the rate on it. Realtor.com chief economist Danielle Hale’s weekly housing outlook, cited in AOL’s report, quantified why moving is expensive: replacing an existing mortgage with a new one could raise a typical repeat buyer’s monthly payment by about $1,100, an 85% increase over the typical existing payment of $1,300.
That arithmetic defines the lock-in effect. Homeowners holding loans at 3% or lower face taking on financing well above 7% if they sell, so many stay put — even those who might prefer a smaller house. For seniors still paying down a balance, the calculation is doubly constrained: less equity flexibility, and a rate shock on top of it.
By contrast, owners without a mortgage face no such trap. Xu writes that owners who own their homes outright “are likely indifferent to changes in borrowing costs” — they can sell when they choose and buy the next place in cash.
Bigger balances on fixed incomes
The debt itself has grown faster than the group carrying it. Median home-secured debt for households 75 and older reached $101,000 in 2025, a gain of about 30% over the $77,720 recorded in 2010, based on the Federal Reserve’s Survey of Consumer Finances as cited in the report.
CBNC noted the payment pressure: every dollar of that obligation comes out of income streams that do not grow with prices, and it pointed to wholesale prices rising 6.5% in the year through October.
Carrying a mortgage late in life is not automatically distress, and the sources are careful on this point. AOL’s report notes some buyers purchase their first home later in life, others refinance or relocate, and some deliberately keep a low-interest loan rather than pay it off early.
Why the free-and-clear hold the keys
For the broader market, the divide matters most when the oldest baby boomers’ homes would otherwise come back to supply. A mortgage-free owner can decide to sell on needs alone. A mortgaged or rate-locked owner has two reasons not to: an unpaid balance to settle, or a cheap loan worth more than the move.
The result is fewer listings for buyers already fighting affordability, and a senior cohort that looks less like a coming wave of supply than a second lock-in group. The 41% who own outright — up about a quarter from 32.8% in 2010 — remain the segment able to move on their own schedule, “likely indifferent to changes in borrowing costs,” as Xu put it.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute financial advice.
