
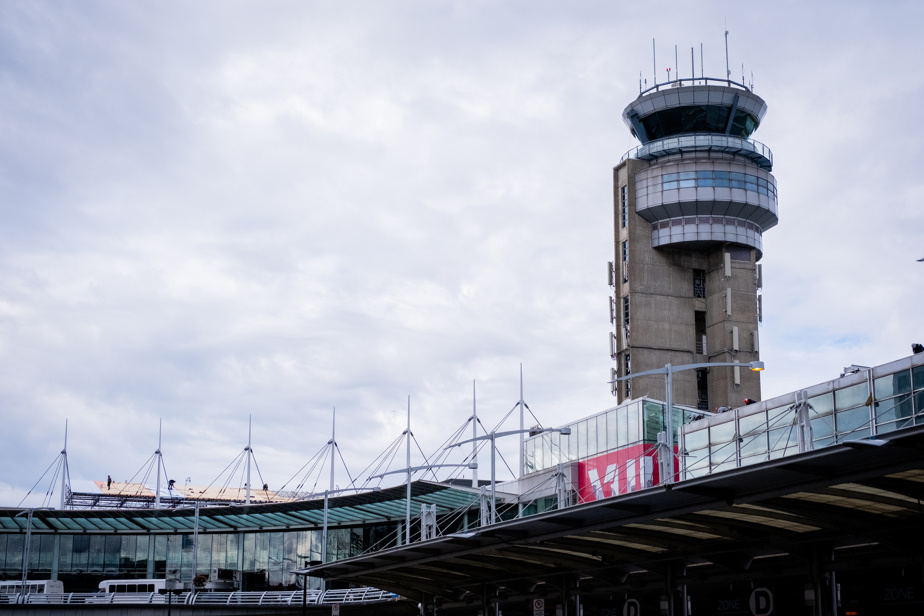
The Canadian federal government’s recent policy shift to partially privatize major international hubs—including Montreal-Trusteau, Toronto Pearson, Calgary, and Vancouver—has introduced severe capital uncertainty for Aéroports de Montréal (ADM), complicating its multi-billion-dollar infrastructure pipeline leading up to 2035.
The Bottom Line
- Privatization Pressures: Ottawa’s push to transfer operations to private investors, such as pension fund managers, leaves ADM’s capital expenditure plan facing a strategic review.
- Mounting Liabilities: ADM’s debt load sits near its previous levels and was projected by DBRS Morningstar to swell toward higher sums by 2030, straining its credit profile.
- Steep Fees: Montreal-Trudeau currently levies a 40 dollar airport improvement fee per ticket, tying with Toronto Pearson for the highest rate in Canada.
Infrastructure Ambitions Collide With Private Equity Realities
While immediate passenger-facing bottlenecks—such as landside vehicular congestion and baggage processing capacity upgrades—remain on schedule alongside the Réseau express métropolitain (REM) station slated for 2027, long-term capital projects face deep scrutiny.
The core friction point centers on the post-2028 horizon. ADM’s overarching master plan demands immense capital outlays, notably for the “side-piste” satellite pier. This four-story, 80,000-square-meter facility is engineered to add 12 boarding gates via an underground passenger tunnel, accompanied by a new multi-level parking structure. Yet, with federal authorities driving toward partial privatization, ADM finds itself unable to accelerate these multi-billion-dollar commitments unilaterally.
“ADM devra discuter rapidement avec le gouvernement du Canada avant de prendre la décision d’engager la prochaine étape de réalisation au-delà de 2028,” noted the non-profit corporation in an official statement sent to La Presse, emphasizing the regulatory limbo hanging over major developments.
Weighing Yield Expectations Against Non-Profit Restraints
Unlike corporate entities capable of issuing equity to public shareholders, ADM operates as a private, non-profit organization. Consequently, its historical financing channels have relied heavily on debt issuance and passenger fees. By the close of 2025, cash reserves hovered around 520 million dollars, contrasted with net profits of 160 million dollars for the fiscal year.
| Financial Metric (ADM) | Figure | Context / Source |
|---|---|---|
| Net Profits (2025) | 160 million CAD | Aéroports de Montréal Annual Report |
| Cash Reserves (End of 2025) | 520 million CAD | Aéroports de Montréal Financials |
| Total Debt Load | ~2.7 billion CAD | DBRS Morningstar Analysis |
| Airport Improvement Fee | 40 CAD per ticket | Current Terminal Tariffs |
Jacques Roy, professor emeritus at HEC Montréal and author of a definitive text on Montreal’s airport history, highlights the fundamental misalignment between non-profit mandates and private sector return thresholds. “Quand le privé arrivera dans le portrait, il exigera un rendement sur son investissement,” Roy explains. “Cet argent n’existe pas actuellement. À leur place, je ne serais pas pressé de poursuivre un plan d’investissement de 10 milliards. Un nouveau gestionnaire risque de vouloir tout passer au peigne fin.”
Credit Ratings and the Capital Expenditure Trajectory
Before transport minister Steven MacKinnon confirmed the federal administration’s accelerated push toward privatization, analysts projected aggressive debt accumulation.
Although DBRS Morningstar maintains an A (high) credit rating for ADM, pointing to solid financial foundations, the rating agency explicitly warned that additional borrowing capacity is severely constrained. Any unilateral debt expansion by the current administration risks triggering downward credit revisions before private equity managers step in.
With passenger throughput stabilizing at millions of travelers in 2025—a slight retraction from the preceding year across its 35 servicing carriers and roughly 160 destinations—incoming private stakeholders will inevitably audit the capital expenditure pipeline. Whether institutional investors, such as Caisse de dépôt et placement du Québec (CDPQ), choose to execute the full blueprint or pare down long-term terminal expansions remains the definitive question for Canada’s aviation infrastructure sector.
