
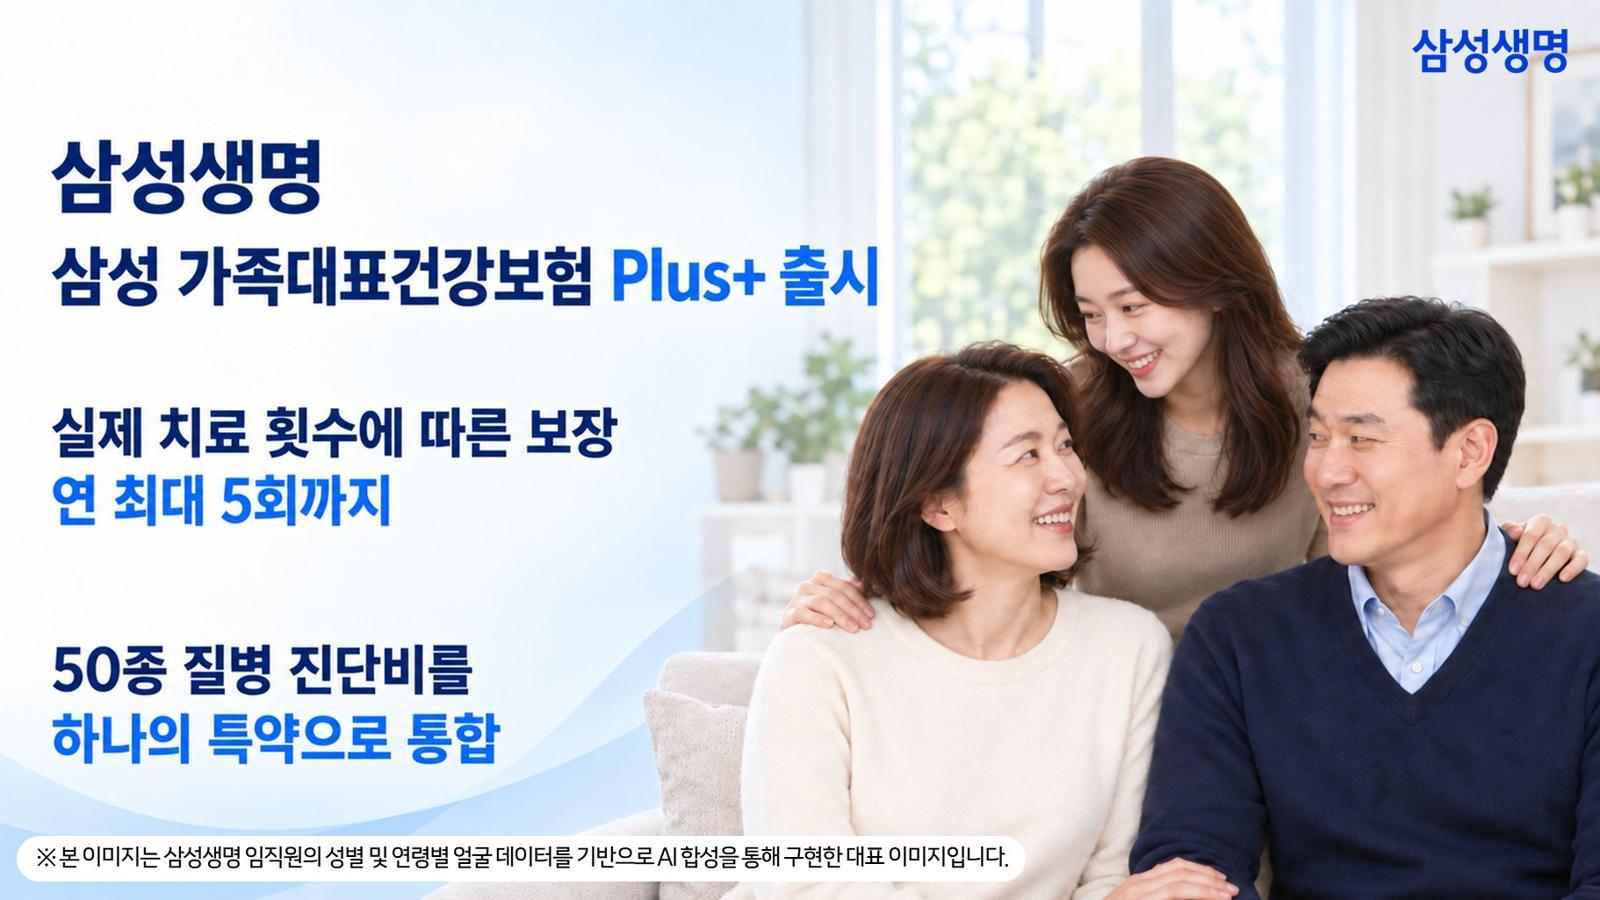
Samsung Life Insurance announced the upcoming launch of its new comprehensive health policy, the ‘Samsung Family Representative Health Insurance Plus+ (Non-Dividend, Non-Cash Surrender Value Type)’, scheduled to debut on October 10. The insurance product introduces structured financial coverage that extends up to five treatments based on frequency, addressing evolving consumer protection needs in regional health markets.
As healthcare expenditures continue to shift globally, insurance mechanisms must adapt to cover repetitive therapeutic interventions. Major health regulatory bodies and financial authorities, such as the U.S. Food and Drug Administration (FDA) and regional financial supervisory services, regularly monitor how insurance products interact with patient access to advanced medical interventions. Financial protections that account for multiple treatment sessions are increasingly vital for managing long-term chronic or recurring clinical care.
In Plain English: The Clinical Takeaway
- Multi-Treatment Provisions: The policy structures financial payouts to accommodate up to five distinct therapeutic interventions, reducing out-of-pocket strain for recurring medical care.
- Non-Cash Surrender Design: By structuring the policy without surrender value returns, premiums are balanced to prioritize ongoing risk coverage rather than investment yields.
- Access and Affordability: Designed to support patients navigating prolonged treatment cycles, minimizing the financial barriers associated with sequential medical procedures.
Clinical Implications of Multi-Intervention Insurance Models
Modern clinical pathways often require iterative procedures—such as recurring physical rehabilitation, staged surgical interventions, or ongoing pharmacological administration. When patients face conditions that demand repeated clinical touchpoints, financial toxicity can directly impede adherence to treatment guidelines. According to public health data published in journals tracking healthcare economics, out-of-pocket expenses remain a primary driver of treatment discontinuation. Products like Samsung Life’s new offering attempt to mitigate this barrier by aligning financial coverage frequency with standard clinical protocols.
The mechanism of action for insurance-backed health stabilization relies on removing economic friction between diagnosis and execution. Clinical guidelines established by organizations such as the World Health Organization (WHO) emphasize that continuity of care is paramount for improving longitudinal health outcomes. When policies cover up to five sequential treatments, patients are statistically more likely to complete their prescribed therapeutic regimens without delaying essential follow-up care due to cost constraints.
| Policy Feature | Standard Term Insurance | Samsung Family Representative Health Plus+ |
|---|---|---|
| Treatment Payout Limit | Typically single-event or capped | Guaranteed up to 5 treatments |
| Surrender Value | Varies (often includes cash return) | Non-cash surrender value structure |
| Target Care Model | Acute, catastrophic events | Sequential and recurring therapeutic care |
Contraindications & When to Consult a Doctor
While financial health products assist in managing the economic aspects of healthcare, they do not replace clinical judgment. Patients must evaluate insurance policy terms alongside their personal medical history and physician recommendations. Consult a primary care physician or a qualified medical specialist immediately if you experience new, worsening, or persistent symptoms that require diagnostic evaluation. Never delay urgent medical care or alter prescribed treatment schedules based on insurance coverage limits or financial considerations. If symptoms escalate—such as acute pain, unexpected neurological deficits, or rapid physiological decline—seek immediate emergency medical intervention.
Future Outlook on Health Insurance Innovations
The integration of flexible, frequency-based health coverage marks a shift in how financial institutions support long-term patient trajectories. As clinical research continues to validate the efficacy of staged medical treatments, insurance frameworks will likely continue to adapt. Ensuring transparent policy structures remains essential for protecting consumers as they navigate complex healthcare environments.
