
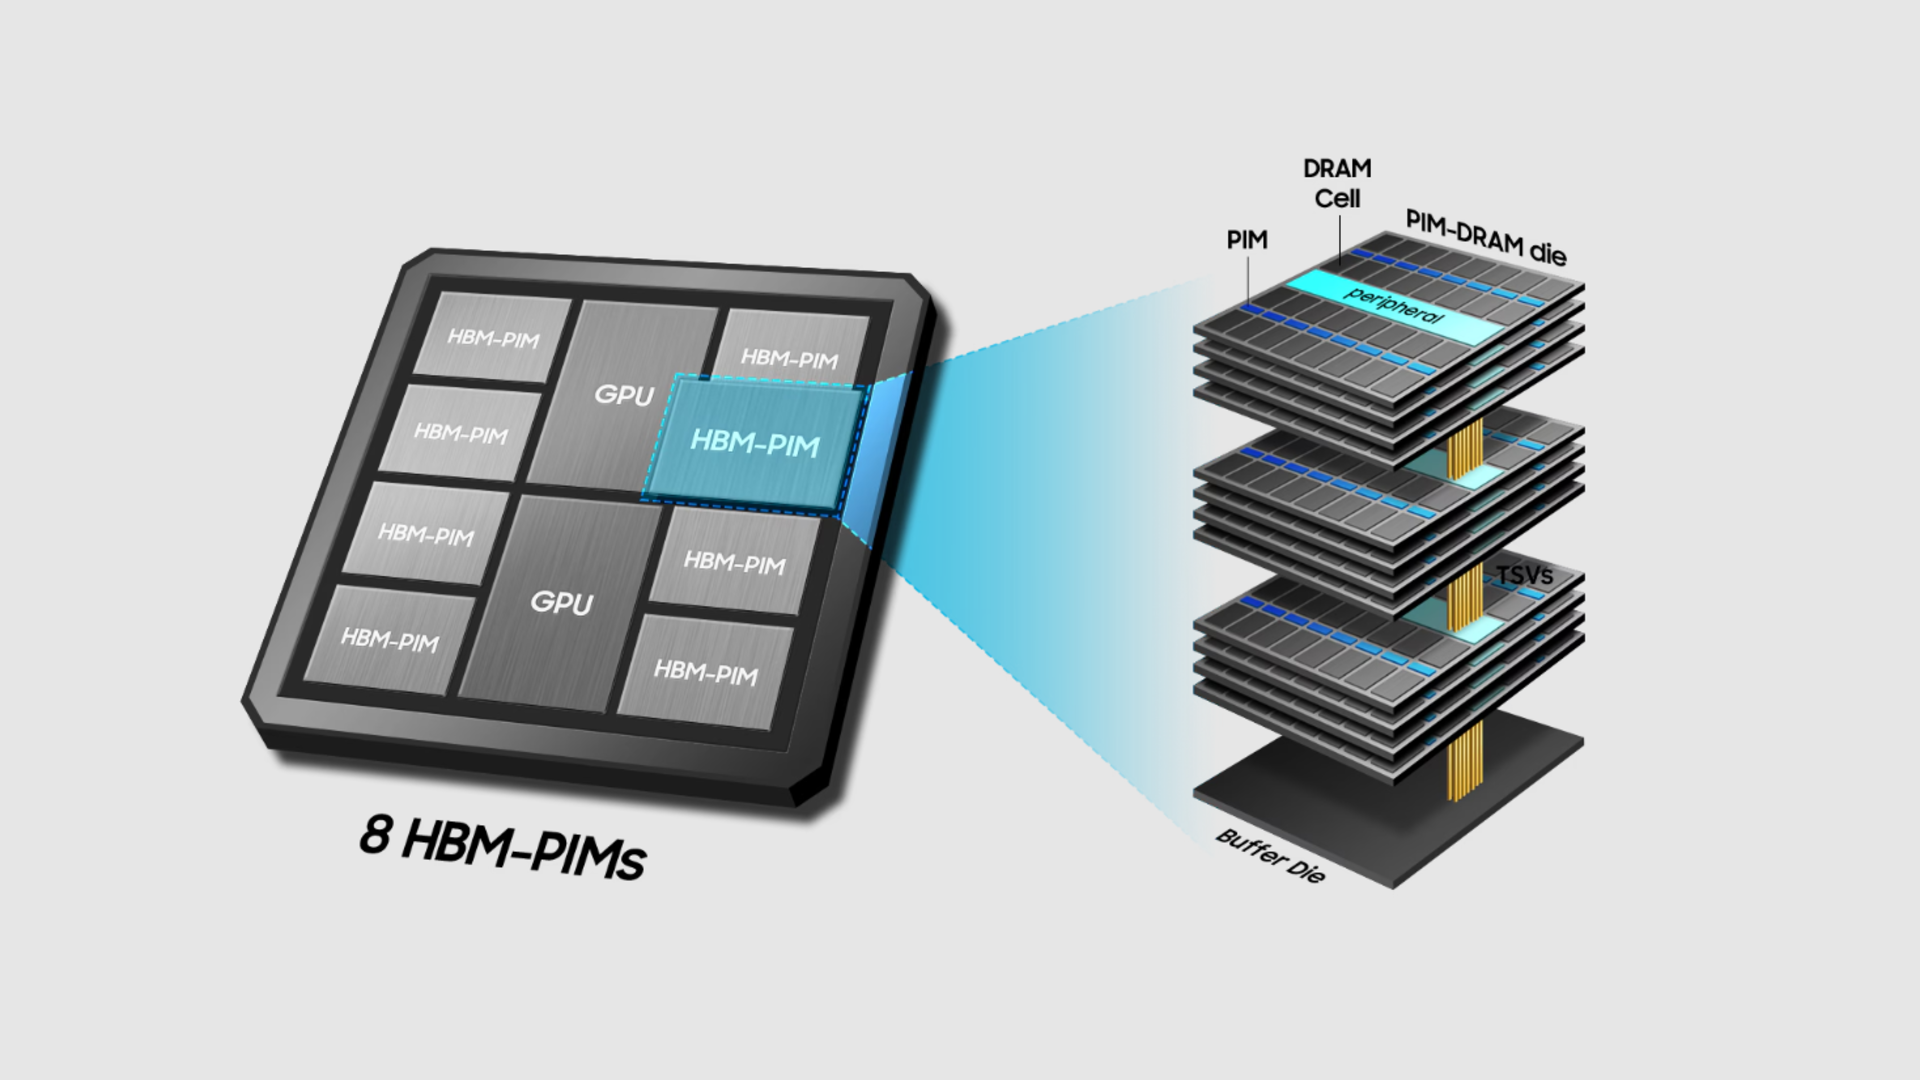
Facing extreme internal capacity constraints driven by explosive artificial intelligence hardware demand, Samsung Electronics is shifting all additional production of conventional DDR5 memory modules and solid-state drives to outsourced manufacturing partners. According to reports from The Elec and MemoryMarket, the company is reallocating factory space at its Cheonan and Onyang campuses in South Korea to prioritize advanced High Bandwidth Memory packaging lines.
The Back-End Bottleneck Driving the Shift
Modern semiconductor fabrication requires massive real estate for both front-end wafer processing and back-end packaging. Samsung lacks the physical space to expand its existing back-end lines for AI chip manufacturing. To solve this, leadership has opted to keep high-margin, complex tasks in-house while pushing conventional module assembly outward. Unlike the intricate multi-die stacking required for advanced HBM, standard DDR5 modules and SSDs rely on surface-mount technology to place pre-packaged DRAM and NAND chips onto printed circuit boards. Because this assembly process remains considerably less complex, outsourcing it to specialized partners is a logistically straightforward maneuver.
The manufacturing pivot relies heavily on several Outsourced Semiconductor Assembly and Test partners. According to industry sources cited by The Elec, Samsung has actively urged these vendors to accelerate capacity expansions that were already part of their existing roadmaps. Dreamtech has scaled up mass production of DDR5 modules in India, with its Noida facility slated to reach an annual capacity exceeding 50 million units. Meanwhile, Hanyang Digitech invested more than 31.5 billion won through 2026 to automate its existing memory module plant in Vietnam. SFA Semicon is also orchestrating a major relocation, transferring DDR5 testing and assembly equipment from Samsung’s Onyang campus to a new site in the Philippines, with a transition window stretching into the second quarter of 2027.
Capitalizing on the AI Memory Boom
This operational restructuring mirrors a broader industry trend. Micron previously pursued a similar strategy by shifting conventional memory production externally to concentrate internal resources on higher-margin enterprise products. For Samsung, the stakes are tied directly to the runaway financial success of AI accelerators. Demand for HBM has surged at an annual rate of 70%, commanding significantly higher profit margins than standard consumer memory.
Samsung’s infrastructure investments underscore this aggressive reallocation. The company is currently constructing a new HBM facility at its Onyang campus valued at 6 trillion won, a project that will take multiple years to complete. Simultaneously, a separate $1.5 billion back-end processing plant is rising in Thai Nguyen Province, Vietnam, dedicated to handling older memory types like DDR4, LPDDR4, NAND flash, and universal flash storage. By offloading general module assembly, Samsung frees up the capital and cleanroom floor space necessary to scale up front-end 1c DRAM output at its P4 facility in Pyeongtaek.
Market Realignment and the SanDisk Question
As major memory foundries pivot their internal footprints toward enterprise AI infrastructure, the supply landscape for consumer PC and server components is undergoing a structural evolution. Whether SanDisk will follow a comparable path remains uncertain. Industry analysts note that manufacturing footprints and product mixes vary wildly across the sector, making a blanket industry-wide outsourcing wave difficult to predict.
General-purpose memory is increasingly becoming a commoditized, outsourced utility, while advanced packaging capacity is treated as the ultimate corporate fortress. For Samsung, ceding control over conventional DDR5 assembly is a calculated sacrifice to secure dominance in the high-stakes battle for AI memory supremacy.
