
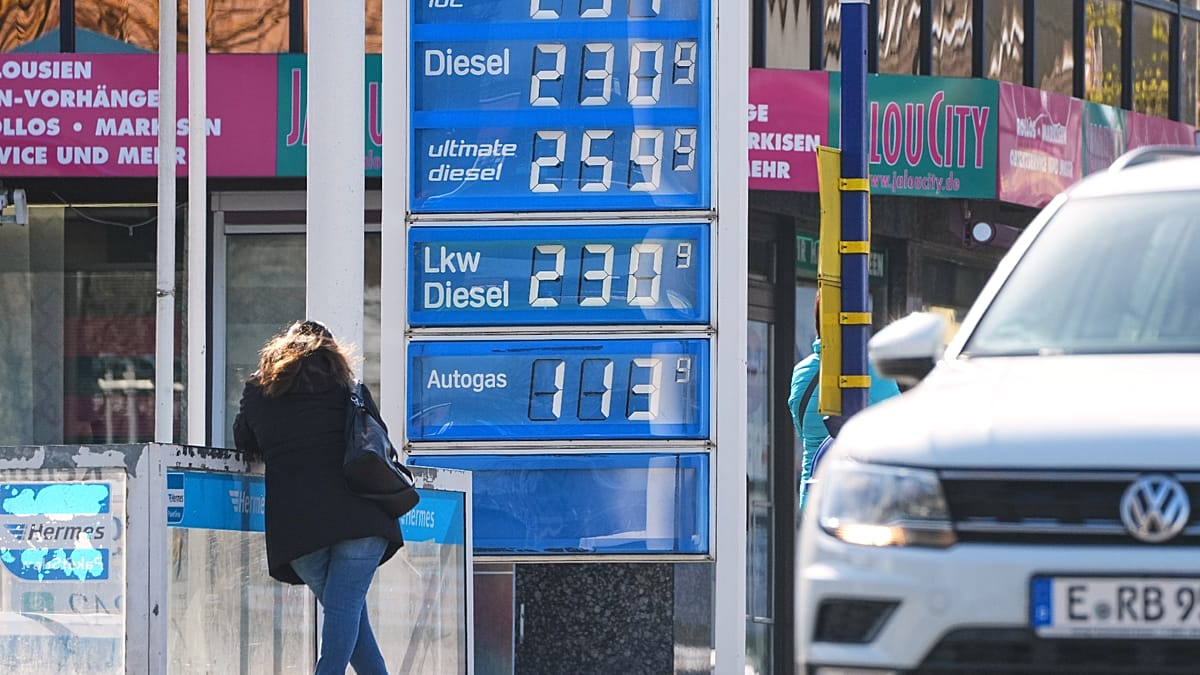
A potential United States diesel export ban could severely tighten global fuel markets, forcing European governments into emergency interventions. With the EU heavily dependent on American barrels following the loss of Russian energy and Middle Eastern supply disruptions, North-West Europe faces immediate price spikes and fierce international competition for scarce replacement fuel.
Washington’s Retention Threat and the Vulnerability of European Supply Chains
The prospect of Washington restricting domestic fuel exports has set off diplomatic alarms across Brussels. European officials acknowledge that losing access to American diesel creates an acute vulnerability. The European Commission has confirmed that the issue is currently under active discussion with member states and industry representatives.
Here is why that matters right now: Europe is already grappling with a severe fuel shortage. The ongoing conflict with Iran has disrupted traditional supply routes from the Middle East, while Moscow has clamped down on its own diesel shipments. Refineries worldwide are operating near full capacity, leaving little room to maneuver. European diesel prices have more than doubled since the beginning of the year, trading roughly 38% higher year-on-year by mid-September.
“For Europe, the immediate effect is higher prices,” Zameer Yusof, an energy analyst at market intelligence platform Kpler, explained to Euronews. “North-West Europe would have to bid up to pull in replacement cargoes, and it would be bidding against the Mediterranean, Latin America and West Africa for the same limited pool of barrels.”
Mapping the Dependency: Who Loses Most in a US Export Ban?
The European Union’s reliance on American refiners has deepened significantly. This year, the US has supplied roughly 180,000 barrels per day (b/d) out of the EU’s 580,000 b/d of extra-EU diesel imports. That accounts for about 32% of total external supplies, a sharp jump from 17% in 2025.
The exposure is far more pronounced in North-West Europe. US supplies account for approximately 200,000 b/d out of 350,000 b/d coming from outside the region—roughly 57%, compared to 37% last year, according to Kpler data. But there is a mathematical nuance to consider: removing 30% of US imports does not automatically translate to a 30% price surge. Instead, buyers will enter aggressive bidding wars, pushing market rates steeply upward.
| Country | US Diesel Import Volume (b/d) | Share of Total Diesel Imports | Key Domestic Pressures |
|---|---|---|---|
| France | ~63,000 b/d | ~36% | Refinery closures at Grandpuits and Donges; 2027 elections approaching. |
| United Kingdom | ~50,000 b/d | ~26% | Grangemouth refinery closure increases structural import reliance. |
| Spain | Variable | ~19% | Buffered by domestic refining capacity in Cartagena, Bilbao, and Huelva. |
| Italy | Variable | ~4% | Protected by domestic and Mediterranean refining networks. |
France Faces Political Shockwaves as Inventories Offer Temporary Cushion
Within the bloc, France appears to be the most vulnerable country. French President Emmanuel Macron labeled the proposed US export ban “catastrophic” on Thursday. The timing could hardly be worse for Paris, with the country heading toward polls in 2027 while an ongoing energy crisis continuously stokes far-right rhetoric.
Before the Trump administration touted a diesel ban, Macron urged the European Commission to temporarily relax strict fuel specifications. This change would allow European refineries to churn out higher volumes of diesel and jet fuel. He also pressed Brussels to coordinate a second release of emergency oil reserves.
France imported roughly 63,000 b/d of American diesel this year, making up 36% of its import mix. That dependency is exacerbated by domestic refinery closures at Grandpuits and Donges, leaving the French market structurally short. Across the Channel, the UK imports about 50,000 b/d from the US—26% of its total diesel imports—a vulnerability heightened by the shutdown of the Grangemouth refinery.
Fortunately, diesel remains among Europe’s most heavily stocked oil products. Existing inventories can absorb at least part of an initial supply shock, staving off immediate pumps running dry. Yet reserves offer no permanent escape from structural price pressures if Washington’s restrictions drag on.
The Global Search for Replacement Barrels Hits a Dead End
Once domestic reserves draw down, Europe faces a grim reality: there are no obvious replacement suppliers waiting in the wings. Major alternative exporters simply do not have the surplus volume.
“India is the only credible substitute, but its export availability has been affected sharply,” Yusof noted. Total Indian exports dropped from roughly 582,000 b/d last year to 352,000 b/d this year. Direct shipments to Europe fell even faster, plummeting from 163,000 b/d down to roughly 50,000 b/d.
Indian refiners are pivoting toward more lucrative returns in East Africa and Southeast Asia. Complicating matters further, European trade compliance rules run into hurdles regarding the origin of Russian crude processed in certain Indian refineries. Meanwhile, Asian heavyweights like China and South Korea provide virtually no relief, contributing a meager 1,000 b/d and 2,000 b/d to Europe respectively this year.
As international energy channels constrict, European policymakers find themselves with precious few options to insulate households, farmers, and hauliers from the gathering storm.
