
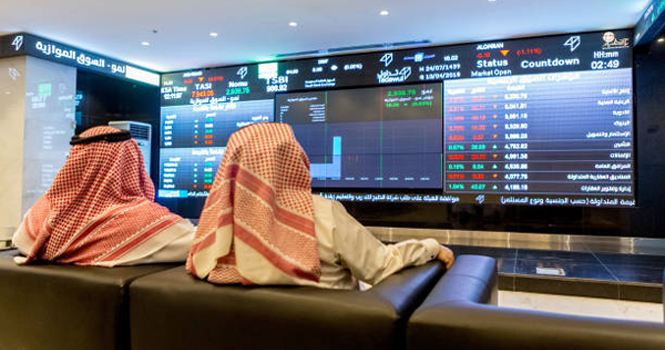
On the Saudi Exchange, known as Tadawul, market activity featured a wave of privately negotiated equity transactions.
Private Deals Execute Share Blocks, Vary Volumes
Execution Mechanics: Private deals allow buyers and direct sellers to execute substantial share blocks off the open market, keeping standard daily high, low, open, and close prices insulated from large liquidity shifts.
Cross-Outlet Discrepancies: Reporting across financial tracking platforms highlights varying transaction volumes and aggregate values across consecutive sessions, reflecting fluctuating block-trade frequency throughout the trading week.
Settlement Flexibility: Depending on the agreed terms between counterparties, private transaction settlements can range dynamically from immediate clearing up to extended multi-day settlement windows.
Anatomy of Block Trades on the Saudi Exchange
According to data compiled by Argaam, trading screens on the Main Market registered 19 private deals in a single session, accumulating a total transaction value of 176.6 million Saudi Riyals.
Under Tadawul regulations, private deals are executed when a buying investor and a selling investor agree on specific securities and exact pricing outside the continuous order matching system. These arrangements must strictly comply with Capital Market Authority (CMA) guidelines. Crucially, market rules dictate that these off-book transactions exert zero impact on the security’s last traded price, opening price, closing price, intraday boundaries, or broader sector indices.
| Company Name | Share Price (SAR) | Deal Price (SAR) | Volume (Shares) | Total Value (SAR Millions) |
|---|---|---|---|---|
| Al Rajhi Bank | 52.55 | 52.00 | 274,324 | 14.26 |
| Bupa Arabia | 60.90 | 60.70 | 165,276 | 10.03 |
| Maharah | 138.70 | 139.00 | 54,101 | 7.52 |
| Bahri | 35.12 | 35.12 | 478,461 | 16.80 |
Multisession Volume Fluctuations Across Financial Trackers
During a preceding mid-week session, Mubasher tracked 11 private deals totaling 45.49 million Riyals across approximately 1.02 million shares, featuring specific blocks in equities like Alinma Bank and Al-Dawaa Medical Services Co.. In that specific sequence, Bupa Arabia experienced separate cross-transactions valued at 7.14 million Riyals for 50,000 shares executed at 142.80 Riyals.
Further adding to the transactional timeline, Maaal reported that additional multi-million Riyal block activity cleared earlier in the weekly cycle, covering specialized entities such as Al-Mouwasat and Al-Khorayef. Maaal detailed that private negotiations permit counterparties to structure trade execution across specialized windows, including pre-open auction periods, open market hours, closing auctions, and post-closing blocks, provided formal exchange approvals and pricing limits are satisfied.
Settlement Terms Structured Dynamically, Default Standard
The operational mechanics governing these transactions dictate how capital moves between institutional desks. As outlined in exchange filings, settlement terms for negotiated orders can be structured dynamically between immediate same-day clearing and a standard five-day window. If counterparties omit a specific timeline during deal structuring, the system automatically defaults to a standard clearance cycle.
Because these substantial capital allocations bypass the central order book, retail investors trading on standard continuous volumes remain shielded from sudden price distortions driven purely by block repositioning. Regulatory oversight ensures transparency in reporting aggregate daily volumes while preserving the integrity of individual equity pricing benchmarks across the exchange.
