
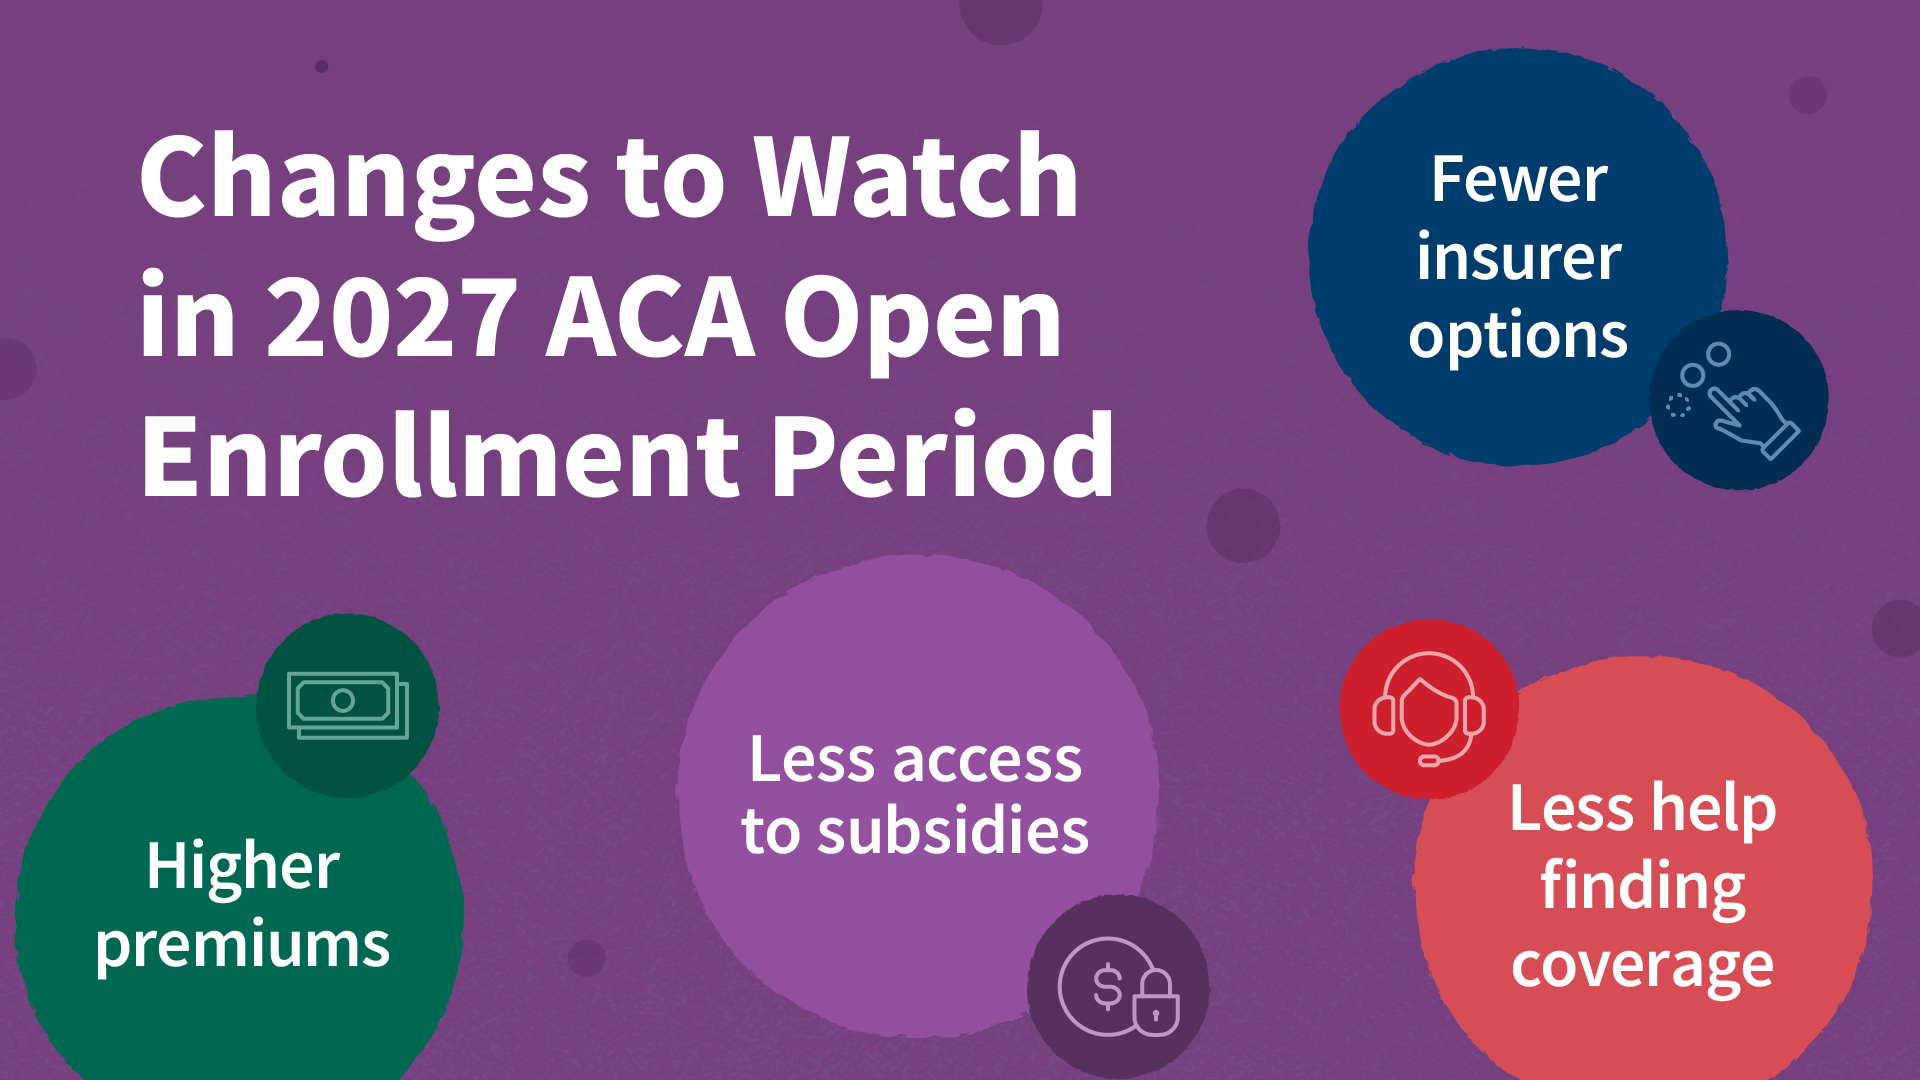
The Affordable Care Act Marketplace 2027 Open Enrollment period begins on November 1, 2026, across most states, introducing double-digit premium increases following the expiration of enhanced federal tax credits, kff.org reported.
In Plain English: The Clinical Takeaway
- Subsidies cushion costs: While benchmark premiums are rising by double digits, most enrollees will still receive financial assistance to offset price hikes.
- Income thresholds matter: Individuals earning above 400% of the federal poverty level receive no premium tax credits and must absorb the full cost of coverage.
Double-Digit Premium Increases and Subsidy Pressures
Insurers proposed a median premium increase of 15% for the 2027 plan year, resulting in an average increase of 13% for finalized benchmark silver premiums, kff.org reported. This follows a 26% rise in these premiums from 2025 to 2026. States utilizing the Healthcare.gov platform are seeing an 11% increase in benchmark silver premiums, whereas state-based marketplaces are experiencing a 16% hike.
Insurers point to rising underlying healthcare costs and the expiration of enhanced premium tax credits as primary drivers for these rate adjustments. According to kff.org analysis of insurer filings, risk pool shifts added approximately four percentage points to premiums in 2026 and are expected to have a similar, additional effect in 2027. While subsidies protect many enrollees, consumers with incomes exceeding 400% of the federal poverty level face the full financial burden.
Enrollment Declines
Marketplace enrollment has contracted following the expiration of enhanced premium tax credits. During the 2026 Open Enrollment Period, Marketplace plan selections fell by 1.2 million from 2025. By February 2026, effectuated enrollment fell by 12% (or 2.6 million people) from the previous year to 19.2 million people.
State-Level Backstops and New Federal Broker Oversight
While jurisdictions like New Jersey have kept their subsidy initiatives in place, Virginia and Rhode Island have established fresh, state-specific financial assistance options for the 2027 plan year. Even though the disappearance of federal aid poses challenges, these local measures can assist certain buyers in paying for insurance, though the degree of backing fluctuates depending on geographic location and earnings.
Concurrently, federal authorities are implementing stricter regulatory safeguards to combat broker fraud. In September 2026, HHS terminated health plans for roughly 760,000 enrollees labeled by CMS as “phantom” participants, indicating that an agent or broker might have enrolled them without their consent.
Immigrant Eligibility Restrictions and Tax Credit Repayment Limits
Asylees, human trafficking survivors, refugees, and other lawfully present immigrants remain permitted to buy Marketplace plans, yet they lose qualification for premium tax credits. Without subsidies, many may be unable to afford their premiums and could drop coverage.
Furthermore, the budget reconciliation law (“The One Big Beautiful Bill Act”) removed prior restrictions that previously capped excess premium tax credit repayments for specific Marketplace participants, with these changes taking effect starting in the 2026 tax year. Given that initial tax returns under these revised regulations will not take place until early 2027, participants will select their 2027 coverage options without prior exposure to how the uncapped repayment structure operates practically.
References
- Kaiser Family Foundation (KFF): 9 Things to Watch for the 2027 Affordable Care Act Open Enrollment Period
