
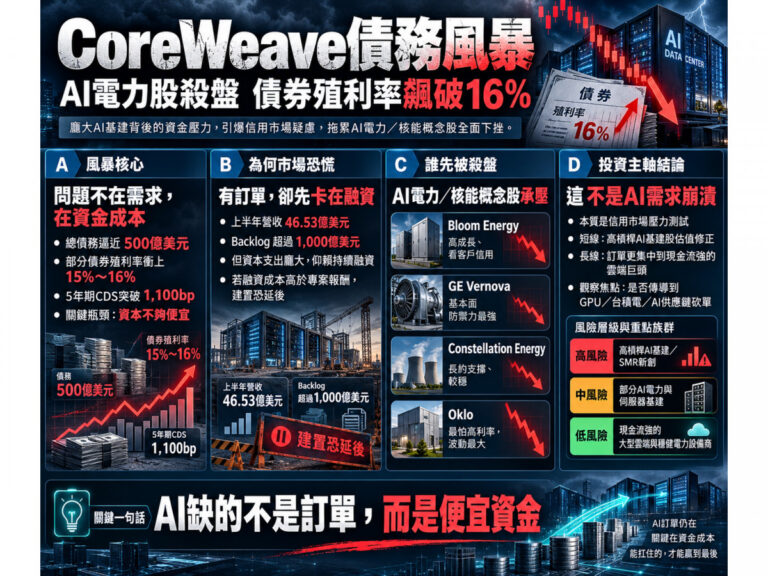
CoreWeave faces a growing credit crunch as its debt approaches 50,000,000,000 dollars and bond yields surpass 15 percent, triggering a wider market reassessment of artificial intelligence infrastructure spending and pulling down related power and hardware stocks.
Financial stress hit the artificial intelligence sector as credit markets reacted to the heavy leverage required to build out advanced computing networks. CoreWeave, an emerging cloud provider specializing in rental capacity built on Nvidia graphics processing units, saw its debt load draw intense scrutiny from investors. Market pressures pushed its 2031-maturity bonds down significantly in secondary trading, with yields surging past the 15 percent mark. According to Reuters on October 15, the firm’s five-year credit default swap (CDS) spreads breached 1,000 basis points, with some reports from Teleborsa indicating a spike to 1,194.5 basis points, implying a default probability exceeding 60 percent over the next five years.
CoreWeave Debt and Rising Yields
The company’s financial structure relies heavily on external borrowing to fund the physical assets required for large-scale machine learning operations. CoreWeave holds approximately 52,000,000,000 dollars in total debt and lease obligations, while second-quarter interest expenses rose significantly compared to the prior year.
CoreWeave’s financial position is getting better every single day, and the cost of capital is actually coming down.
Nvidia Chief Executive Officer Jensen Huang offered public support during a series of appearances in Stockholm and Berlin, asserting that the cloud provider’s fundamentals are strengthening and that additional financial backstops from Nvidia are unnecessary. The chipmaker maintains deep ties with CoreWeave as an equity investor, hardware supplier, and customer. Under an existing agreement, Nvidia committed to purchasing unsold cloud capacity from CoreWeave through April 2032 under a framework initially valued at 6,300,000,000 dollars. Despite Huang’s optimism, financial commentator Ruan Muhua highlighted the discrepancy between executive narrative and market reality, noting that investors are choosing to believe the rising bond yields and CDS prices over the verbal assurances of partners.
Market Contagion Across AI Power and Hardware Stocks
The sell-off in CoreWeave debt rapidly spilled over into publicly traded equity markets, affecting suppliers and partners across the artificial intelligence supply chain. Bloom Energy, which provides solid oxide fuel cells for rapid data center deployment, experienced sharp share price declines amid concerns that customer financing constraints might delay project timelines. GE Vernova and Constellation Energy also faced valuation adjustments, though analysts noted that Constellation benefits from long-term power purchase agreements with well-capitalized hyperscalers like Meta and Microsoft, shielding it from direct counterparty credit risks. Meanwhile, project-specific bonds, such as those related to Blackstone’s QTS Project Excalibur
and Oracle’s Project Jupiter,
have also seen prices drop below par as investors scrutinize electricity supply approvals and development delays.
At the same time, research firm Gartner released projections estimating that a substantial majority—roughly 80 percent—of newly established cloud service providers could face consolidation or exit independent operations by 2030, warning that projected sector revenues may fall short of covering total capital expenditures and financing costs.
Credit Spreads Widen for High-Debt Firms
While high-yield debt spreads widened markedly for high-debt infrastructure developers, major technology enterprises with strong operating cash flows experienced far milder adjustments. Financial institutions monitoring the credit markets point out that risk premiums are concentrating on high-debt entities rather than spreading into a systemic banking crisis. As the market undergoes this Darwinian moment,
as described by Allianz chief investment officer Ludovic Subran, the focus remains on distinguishing between firms with sustainable cash flows and those relying on self-referential financing loops.
Related reading
