
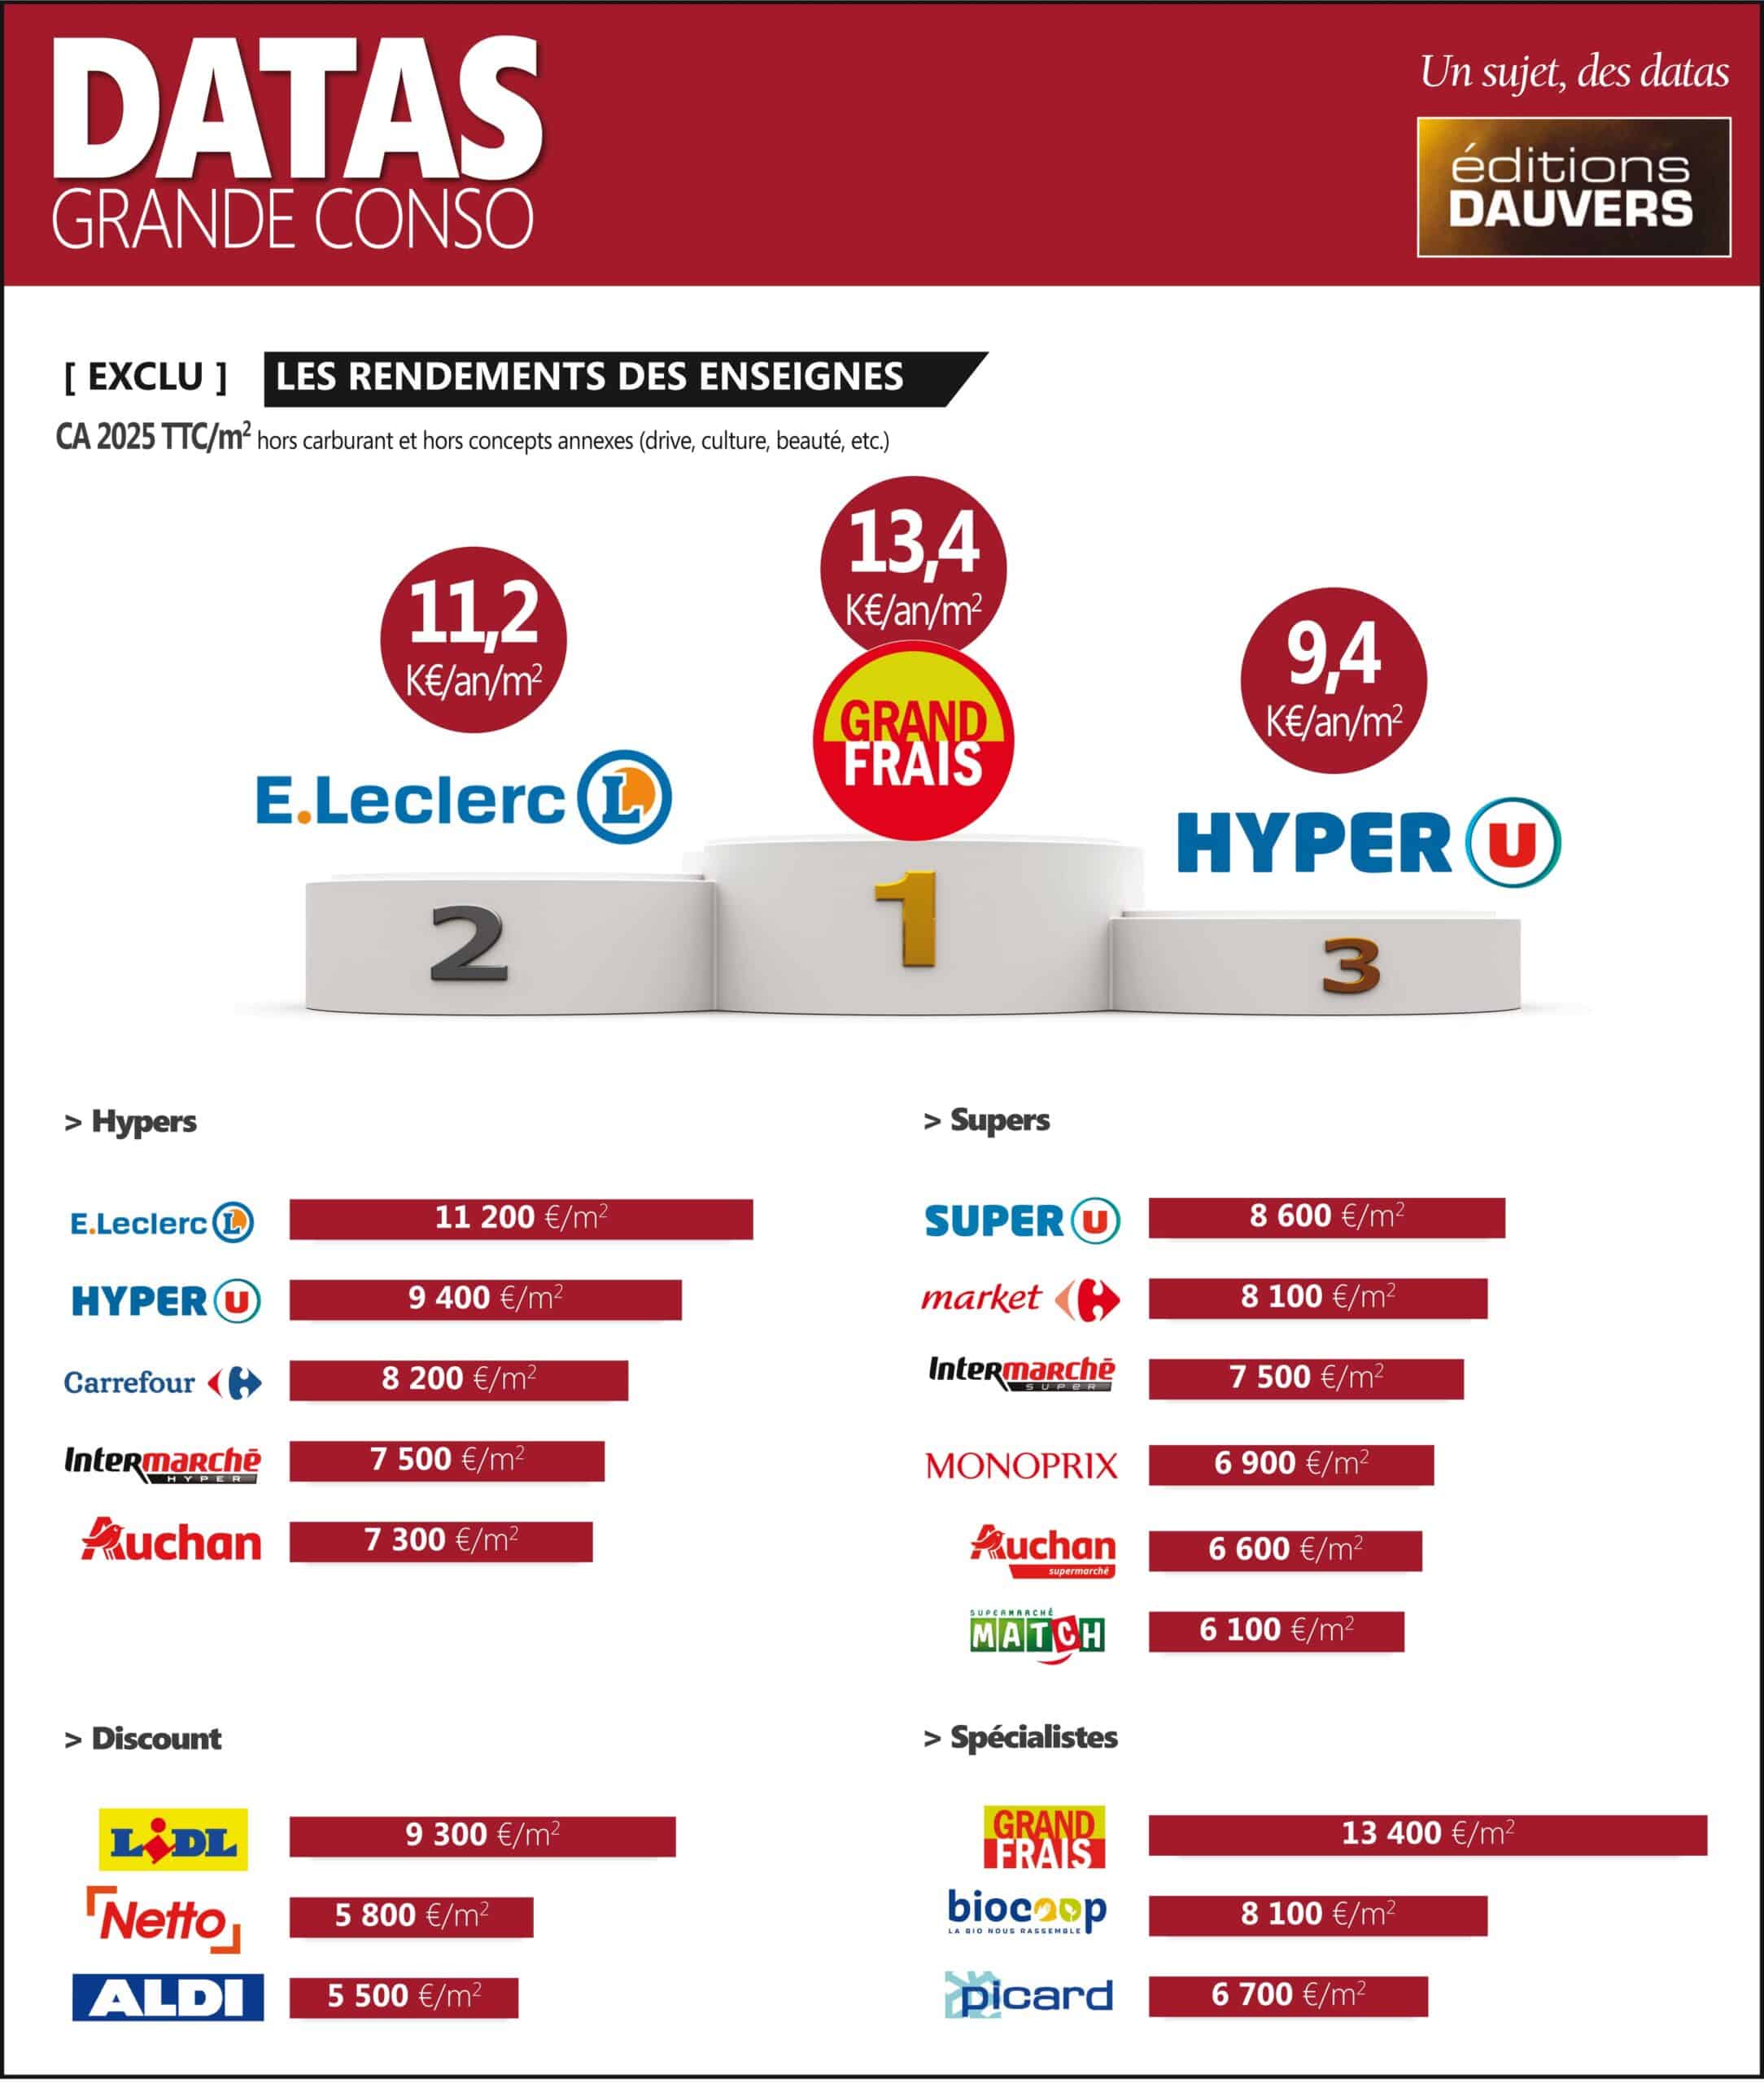
French food retail yields for 2025 reveal that Grand Frais, Leclerc, and Hyper U maintain their dominance in revenue per square meter, with Grand Frais crossing the €13 k€ threshold through its focus on traditional fresh produce, according to data published by retail analyst Olivier Dauvers.
The Bottom Line
- Grand Frais leads all major food retail formats, generating over €13 k€ in revenue per square meter by specializing in high-value fresh traditional products.
- Leclerc outpaces rival general supermarket and hypermarket competitors within the GSA sector, surpassing €11 k€ per square meter.
- Integration challenges from the Casino acquisition continue to drag down performance figures for Auchan and Intermarché stores.
Grand Frais Breaks Fresh Produce Ceilings
Specializing exclusively in traditional fresh goods—a category defined by higher product valuation—allowed Grand Frais to clear €13 k€ per square meter in 2025. Olivier Dauvers noted that this performance remains unmatched across the broader consumer food landscape. Despite these standout metrics, competing retail operators have largely avoided duplicating the format’s blueprint. The sole current exception involves Carrefour and its distinct ambitions for the Match “frais” banner.
"Bactérie mangeuse de chair": ces crevettes de chez Grand Frais et Leclerc peuvent vous rendre gravement maladehttps://t.co/NlVjlP4ewO
Leclerc Pulls Ahead of Hypermarket Rivals
Within the traditional large-scale food distribution sector, Leclerc consolidated its lead by crossing the €11 k€ per square meter threshold. That figure stands 19 percent higher than Hyper U stores and outpaces Carrefour by 37 percent. Meanwhile, the gap separating Leclerc from Auchan hypermarkets has widened significantly. Auchan historical hypermarket locations average €8 k€ per square meter, leaving the gap at an astronomical 53 percent.
Casino Integration Weights Down Auchan and Intermarché Networks
Beyond structural headwinds facing Auchan’s northern operations, the absorption of former Casino outlets—shared alongside Intermarché—continues to weigh heavily on performance averages. Legacy Auchan hypermarkets sit at €8 k€ per square meter, while former Casino locations acquired by the brand stagnate below €5k€. Performance is slightly higher within Auchan Super locations originating from Casino, which sit above €5 k€ per square meter.
For Intermarché, executing roughly thirty store closures helped partially stabilize the network inherited from the Saint-Étienne-based distributor, landing the group at an average of €7,5 k€ per square meter. However, remaining former Casino sites continue pulling down the overall average for the Mousquetaires group. These locations register €6 k€ per square meter within Intermarché Super outlets—surpassing Auchan’s equivalent footprint—while dropping to €4 k€ inside Intermarché Hyper formats, signaling forthcoming portfolio adjustments.
| Retail Banner / Format | Estimated Revenue per m² (2025) |
|---|---|
| Grand Frais | > €13 k€ |
| Leclerc (GSA) | > €11 k€ |
| Hyper U | ~ approx. 19% below Leclerc |
| Auchan Hypermarkets (Historical) | €8 k€ |
| Intermarché Network Average | €7,5 k€ |
| Ex-Casino Intermarché Hyper | €4 k€ |
