
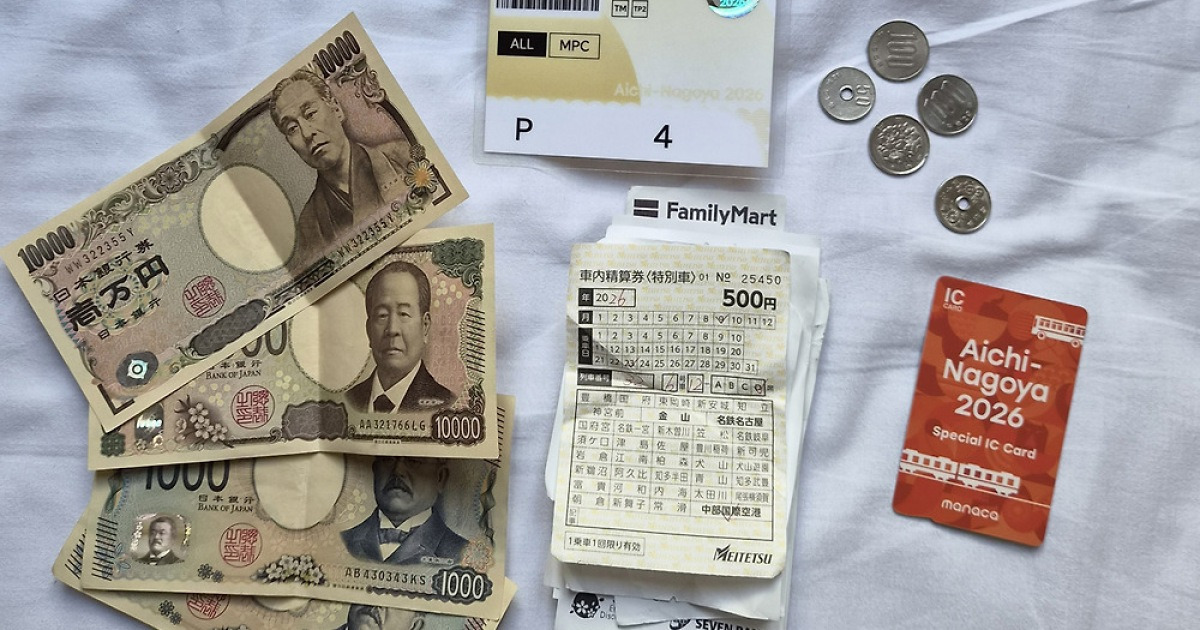
As the 2026 Aichi-Nagoya Asian Games spotlight the region, international visitors are discovering a stark contrast between Japan’s macro-level cashless statistics and the realities of neighborhood commerce. While the Ministry of Economy, Trade, and Industry reports the national cashless payment ratio reached 58.0% in 2025, small-scale merchants, local ramen shops, and venue ticket kiosks across Nagoya continue to operate strictly on cash.
The Bottom Line
- The National Metric: Japan’s Ministry of Economy, Trade, and Industry reported a 58.0% cashless payment ratio for 2025, with total transaction volume hitting 162조7000억엔.
- The Micro Reality: Despite broad adoption in large franchises and convenience stores, independent neighborhood eateries and regional transit venue ticket machines frequently lack electronic processing infrastructure.
- Structural Disconnect: The 58% figure tracks total aggregate consumer spending volume rather than merchant terminal saturation, masking the heavy reliance on cash in micro-retail sectors.
Macro Statistics Meet Main Street Realities in Nagoya
Statistical reports from government bodies often fail to capture transaction bottlenecks at the ground level. During the opening week of the 2026 Aichi-Nagoya Asian Games, visitors exploring the Kanayama Station and Higashibetsuin Station districts quickly encountered the limits of digital infrastructure. While major corporate chains—including Denny’s and McDonald’s—processed card transactions without issue, independent noodle shops and localized vendors relied entirely on coin and bill-operated ticket vending machines.
This operational friction extended directly into official athletic venues. Inside the Nagoya Municipal Gymnasium Rainbow Hall, which hosted artistic gymnastics events, concession area ticket machines lacked card processing terminals, restricting purchases to physical currency. For high-volume transit nodes like Kanayama Station—handling roughly 480,000 daily commuters and international travelers as the Chubu region's second-largest transit hub—payment methods vary widely from one storefront to the next.
Decoding the 58% Milestone
To understand why cash remains essential in modern Japan, analysts must examine how official metrics are calculated. The Ministry of Economy, Trade, and Industry figures show that total cashless spending reached 162조7000억엔 in 2025, marking a 6.3 percentage point increase from the 51.7% recorded under domestic indicators in 2024. The Japanese government maintains a target of reaching 65% by 2030, with a long-term goal of 80%.
However, transaction distribution within that 162조7000억엔 pool heavily favors traditional credit vehicles. Credit card settlements accounted for 134조6000억엔, representing 82.7% of all cashless transactions. Code-based payments followed at 16조6000억엔 (10.2%), electronic money accounted for 6조엔 (3.7%), and debit cards made up 5조5000억엔 (3.4%). Crucially, the 58.0% headline figure measures aggregate consumer spending value rather than the proportion of retail merchants equipped with digital terminals.
Payment Infrastructure Distribution in Japan
| Payment Type | Transaction Volume (JPY) | Share of Cashless Total |
|---|---|---|
| Credit Cards | 134조6000억엔 | 82.7% |
| Code-Based Payments | 16조6000억엔 | 10.2% |
| Electronic Money | 6조엔 | 3.7% |
| Debit Cards | 5조5000억엔 | 3.4% |
| Total Cashless | 162조7000억엔 | 82.7% |
Consumer Sentiment and the Path Forward
Local consumer habits reflect this ongoing transition. While urban professionals express convenience regarding widespread card acceptance in major commercial zones, the persistence of cash-only legacy establishments forces residents to maintain physical currency for everyday outings. As regional hubs like Nagoya absorb an influx of international tourism during major athletic competitions, the friction between national macroeconomic expansion goals and micro-retail limitations highlights the structural challenges facing Japan’s multi-year digital transformation.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute financial advice.
