
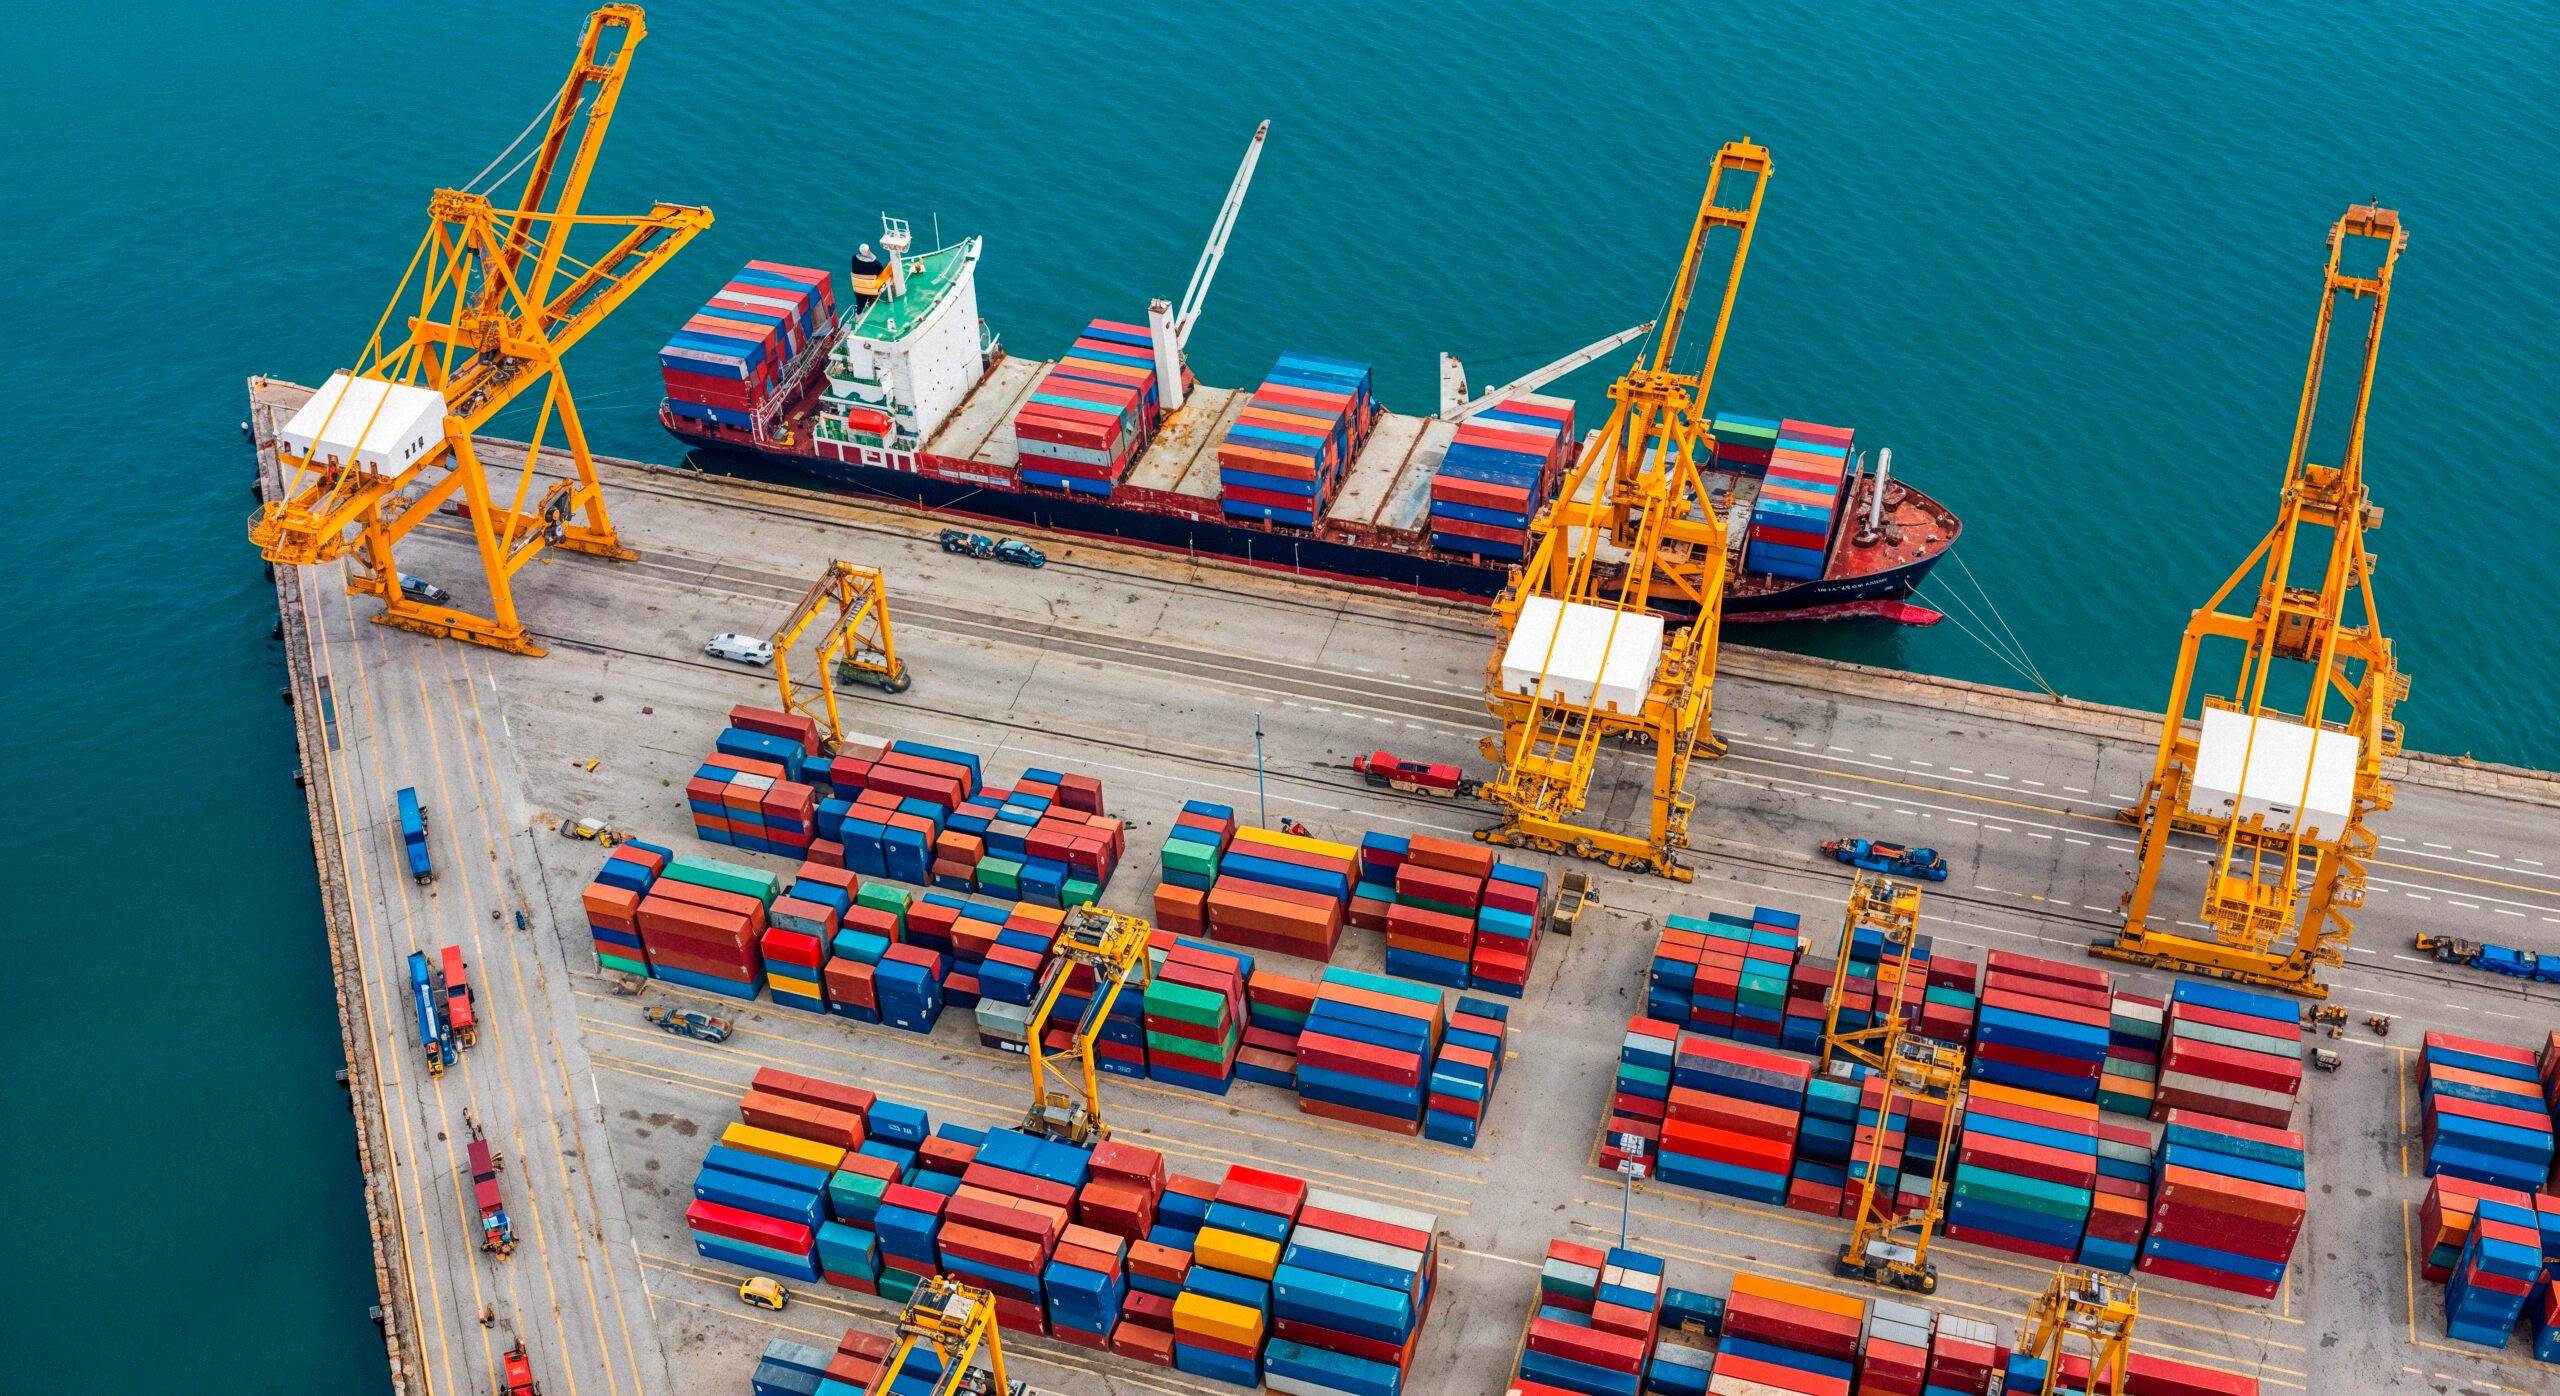
The Pinglu Canal officially opened to navigation on September 16, 2026, establishing a 134.2-kilometer, Class I inland shipping route that connects Southwest China directly to the Beibu Gulf, Fastmarkets reported. As the first river-to-sea canal constructed at the national level since the founding of the People’s Republic of China, the waterway slashes traditional shipping routes to the sea by more than 560 kilometers, reshaping logistics for bulk commodities including steel, iron ore, bauxite, manganese, and chrome.
New Canal Cuts Freight Costs for Regional Producers
The waterway’s debut alters freight dynamics for industrial hubs across Guangxi, Yunnan, Guizhou, and Chongqing. By linking the Xijiang River system in the north directly to Qinzhou Port in the south, the canal allows regional producers to bypass longer transit paths through the Pearl River Delta. Transporting materials like manganese or chrome ore via truck to inland plants typically costs around 70 yuan ($10) per tonne, according to a Guangxi-based ferro-alloy smelter cited by Fastmarkets. Shifting those shipments to river transport cuts costs to roughly 40 to 50 yuan per tonne, yielding savings of 50 to 60 yuan per tonne of ferro-alloy produced.
Additional logistical relief comes during seasonal dry spells. A Chongqing-based alumina and silico-manganese producer noted that while raw materials are typically hauled via the Yangtze River, the Pinglu Canal provides a vital alternative route when water levels drop. For Guizhou operations, the canal shortens export routes for finished industrial goods. On opening day, a vessel carrying 16,000 tonnes of hot-rolled and cold-rolled coils from Liuzhou Steel Group departed directly for overseas markets after passing through the canal locks.
The Pinglu Canal in Guangxi has officially opened to navigation after four years of construction. Stretching 134.2 km and capable of handling 5,000-tonne vessels, it provides southwest China with a shorter route to the sea and is expected to save over 5 billion yuan in transport… pic.twitter.com/mHO00GVdhS
| Port Location | Commodity | Inventories (Million Tonnes) |
|---|---|---|
| Beibu Gulf Ports | Iron Ore | 10.5 |
| Beibu Gulf Ports | Bauxite | 3.5 |
| Beibu Gulf Ports | Manganese Ore | 0.77 |
| Beibu Gulf Ports | Chrome Ore | 0.2 |
Structural Constraints Facing Southern Producers
Despite immediate freight savings, market participants caution that logistical efficiencies alone will not completely transform regional commodity markets. High electricity prices remain a persistent hurdle for energy-intensive sectors like steel, alumina, and ferro-alloy smelting. Industrial electricity prices in Guangxi sit around 0.51 yuan per kWh, compared to approximately 0.41 yuan per kWh in Inner Mongolia. When factoring in higher raw material and coke costs, southern production expenses run roughly 400 to 500 yuan per tonne higher than those in northern industrial hubs.
Geography also curtails the canal’s reach for plants located far from the Nanning-to-Qinzhou corridor. A smelter based in Guilin reported continued reliance on trucks and rail, as the facility sits too far from the new waterway to capture significant cost benefits. Port pricing disparities persist. Fastmarkets recorded the weekly manganese ore high-grade port index for Tianjin at 38.9 yuan per dry metric tonne unit (dmtu) on October 16, 2026, while semi-carbonate indices hovered at 33.40 yuan per dmtu, with southern port prices remaining 1 to 2 yuan higher than northern equivalents.
Assessing the Broader Industrial Impact
Industry stakeholders view the canal’s influence as incremental rather than structural. A Shanghai-based steel trader observed that for major producers like Liuzhou Steel—which already maintains a coastal production base at Fangchenggang capable of direct maritime shipping—the inland waterway offers limited export advantages. Shipowners additionally note that bulk carriers typically favor loading at northern ports such as Qingdao or Tianjin before topping up at the Yangtze River estuary, leaving regional inland volumes too small to dramatically shift major bulk shipping patterns.
At the same time, the project generates targeted domestic demand within the region’s manufacturing sector. A Guangxi-based mill source noted that the canal was currently being used mainly to transport steel products, reducing freight costs and shortening delivery times from mills to sea ports. While the Pinglu Canal successfully lowers regional transit barriers and accelerates cargo turnover, structural cost disparities in power supply ensure that broader market competitiveness will continue to depend on wider macroeconomic conditions.
More on Pinglu Canal
China's newly opened 134-km shortcut from its inland southwest to the sea, cuts trade distances to ASEAN and gives Chinese goods a new route into Southeast Asian markets through Guangxi’s Pinglu Canal. https://t.co/t0gyrUvMVV
China opened the Pinglu Canal on Wednesday, giving its landlocked southwest a shortcut to the coast and overseas markets, particularly those in the Association of Southeast Asian Nations, the country's largest trading partner. #ChinaPulse https://t.co/3P19YQy0qw pic.twitter.com/WDvAir89h7
