
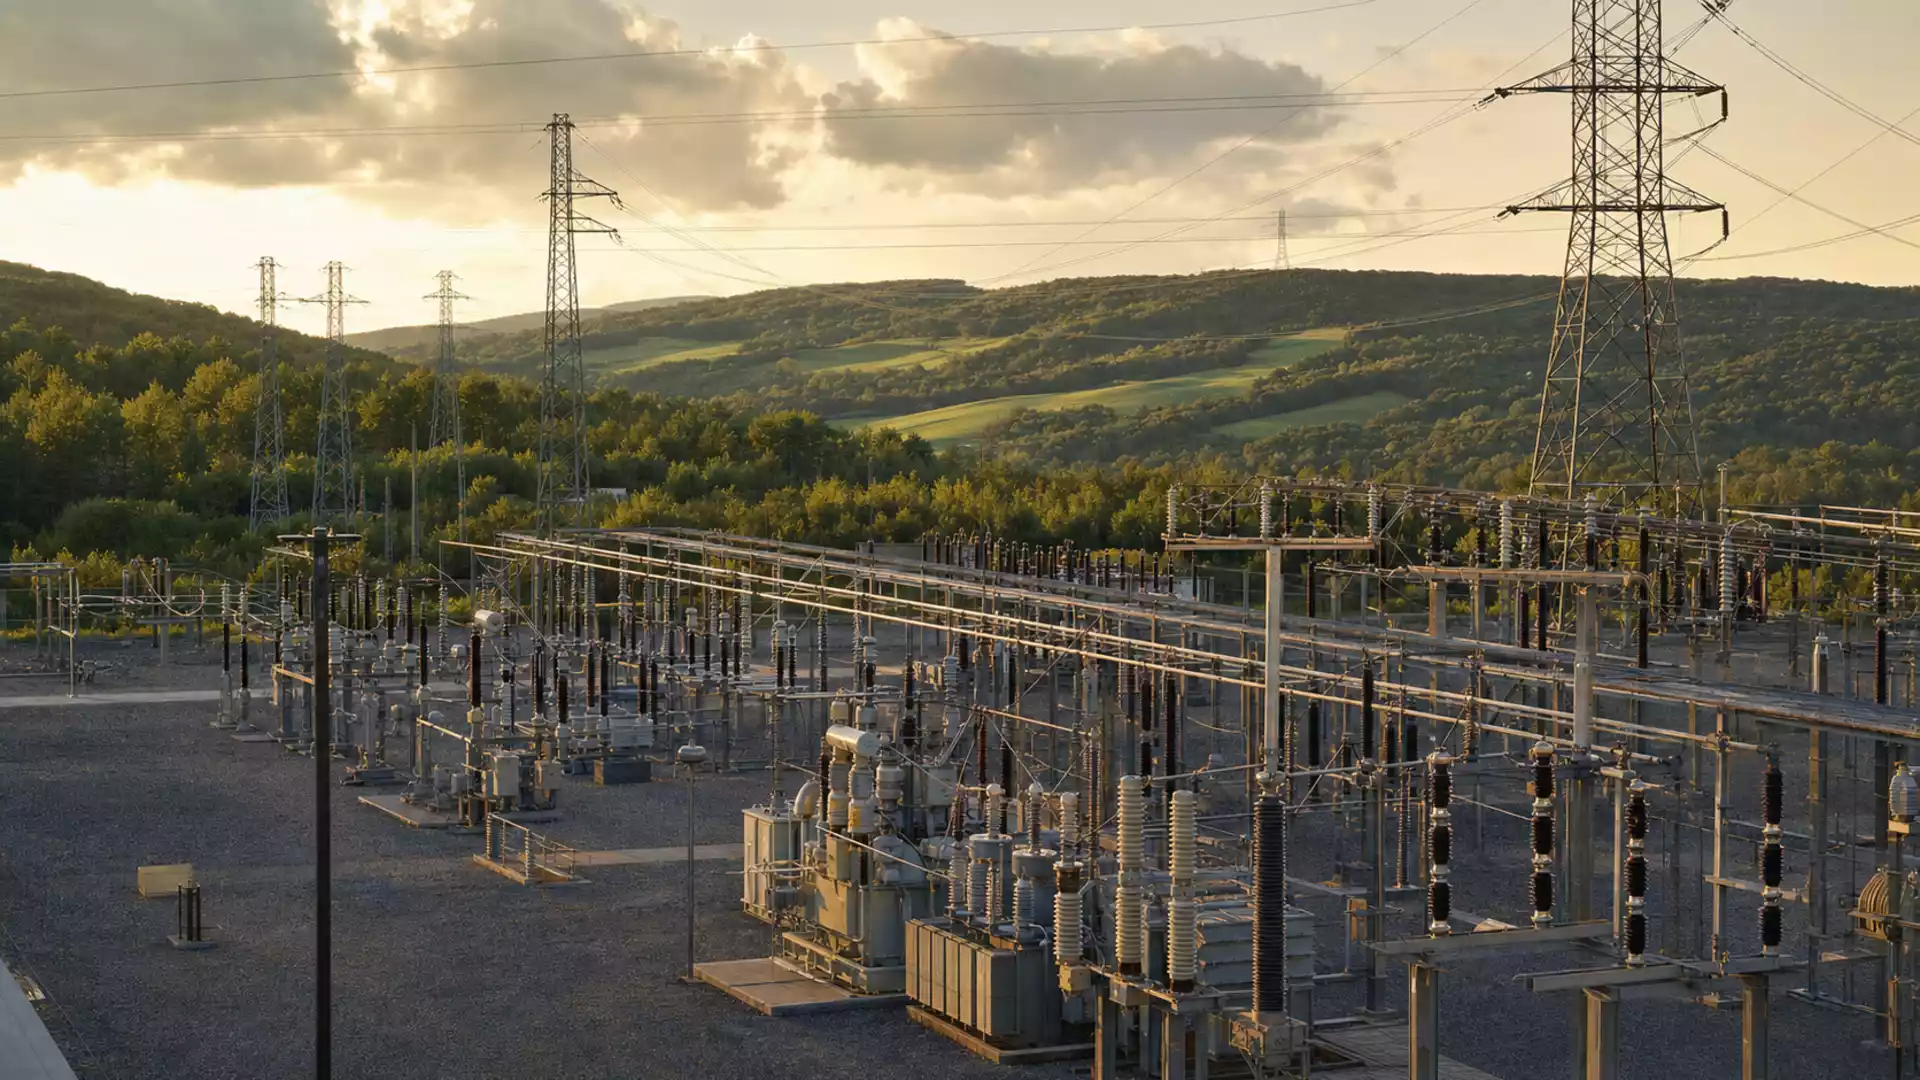
Part of the SPARK program, the Montour Grid Resilience and Advanced Reconductoring Project aims to upgrade a 230-kilovolt line to enhance regional energy reliability and infrastructure stability.
On the surface, this looks like a standard utility upgrade. But for those of us tracking the intersection of energy security and macroeconomics, it is a signal of something larger.
Here is why that matters. The energy transition is only as fast as the grid allows. You can build all the wind farms and solar arrays you want, but if the "pipes"—the transmission lines—are outdated, the power never reaches the city.
The Financial Friction Between Grants and Earnings
The timing of this announcement is curious. While the $71.5 million grant provides a clear infrastructure anchor, PPL’s recent financial performance has been a bit bumpy. In the second quarter of 2026, the company narrowly missed analyst expectations, posting an adjusted earnings per share (EPS) of $0.33 against a consensus of $0.34.
Revenue also lagged slightly, coming in at $2.11 billion compared to the expected $2.19 billion. However, the broader trajectory remains positive; that revenue figure still represents a 4.2 percent increase over the same period last year. For the long-term investor, the noise of a one-cent EPS miss is secondary to the company’s aggressive investment roadmap.
But there is a catch. The market hasn’t fully rewarded this stability yet. As of late September, PPL’s stock was trading around $32.03, which is more than 20 percent below its 52-week high of $40.11. The market is currently weighing the immediate pressure of missed consensus figures against the long-term promise of a modernized grid.
| Key Metric | Value / Detail | Context |
|---|---|---|
| Grant Amount | Up to $71.5 Million | U.S. Dept of Energy (SPARK Program) |
| Project Scope | 29.3 Miles | 230-kV Line Modernization |
| Investment Target | $23 Billion | Total Infrastructure Spend by 2029 |
| EPS Growth Goal | 6% to 8% Annually | Target through at least 2029 |
| Market Cap | $24.1 Billion | As of September 25, 2026 |
Connecting the Pennsylvania Grid to Global Macro Trends
When we look at PPL’s $23 billion investment framework through 2029, we see a mirror of what is happening across the OECD.
For foreign investors, PPL represents a classic defensive play. Regulated utilities offer a predictable return on equity, and federal grants like the one for the Montour project act as a subsidy for growth. It effectively lowers the risk profile of the infrastructure spend. When the U.S. government co-funds the resilience of a grid, it is essentially underwriting the stability of the companies managing that grid.
Dividends and the Path to 2029
Despite the stock price volatility, PPL is maintaining its commitment to shareholders. The company announced a quarterly dividend of $0.285 per share, payable on October 1, 2026. This consistency is designed to soothe investors who are wary of the current 20 percent gap from the yearly high.
The company’s 2026 annual forecast remains steady, with an adjusted EPS range of $1.90 to $1.98. By keeping this guidance intact despite the Q2 miss, PPL is signaling that the Montour project and other SPARK-funded initiatives are part of a controlled, long-term ascent rather than a series of erratic jumps.
The specifics of that contract will determine exactly how much of the $71.5 million is accessible and under what conditions. For now, the "infrastructure anchor" is set, but the ship is still navigating choppy market waters.
Is the current discount on PPL’s stock a sign of fundamental weakness, or is it a window for those betting on the inevitable federalization of grid resilience? Given the scale of the $23 billion investment plan, the latter seems more likely. The grid is the foundation of the modern economy; those who own the foundation usually win in the end.
What do you think—is federal funding enough to offset the volatility of regulated utilities in a high-interest-rate environment? Let’s discuss in the comments.
