
Interest rates govern the time value of money by discounting future income streams, shaping how individuals and institutions evaluate risk, savings, and capital allocation across modern financial markets.
As Edward Chancellor details in The Price of Time, capital cannot exist without interest, and capitalism cannot function without capital. However, shifting abruptly from zero-interest-rate policies to rapid monetary tightening leaves markets vulnerable.
The Bottom Line
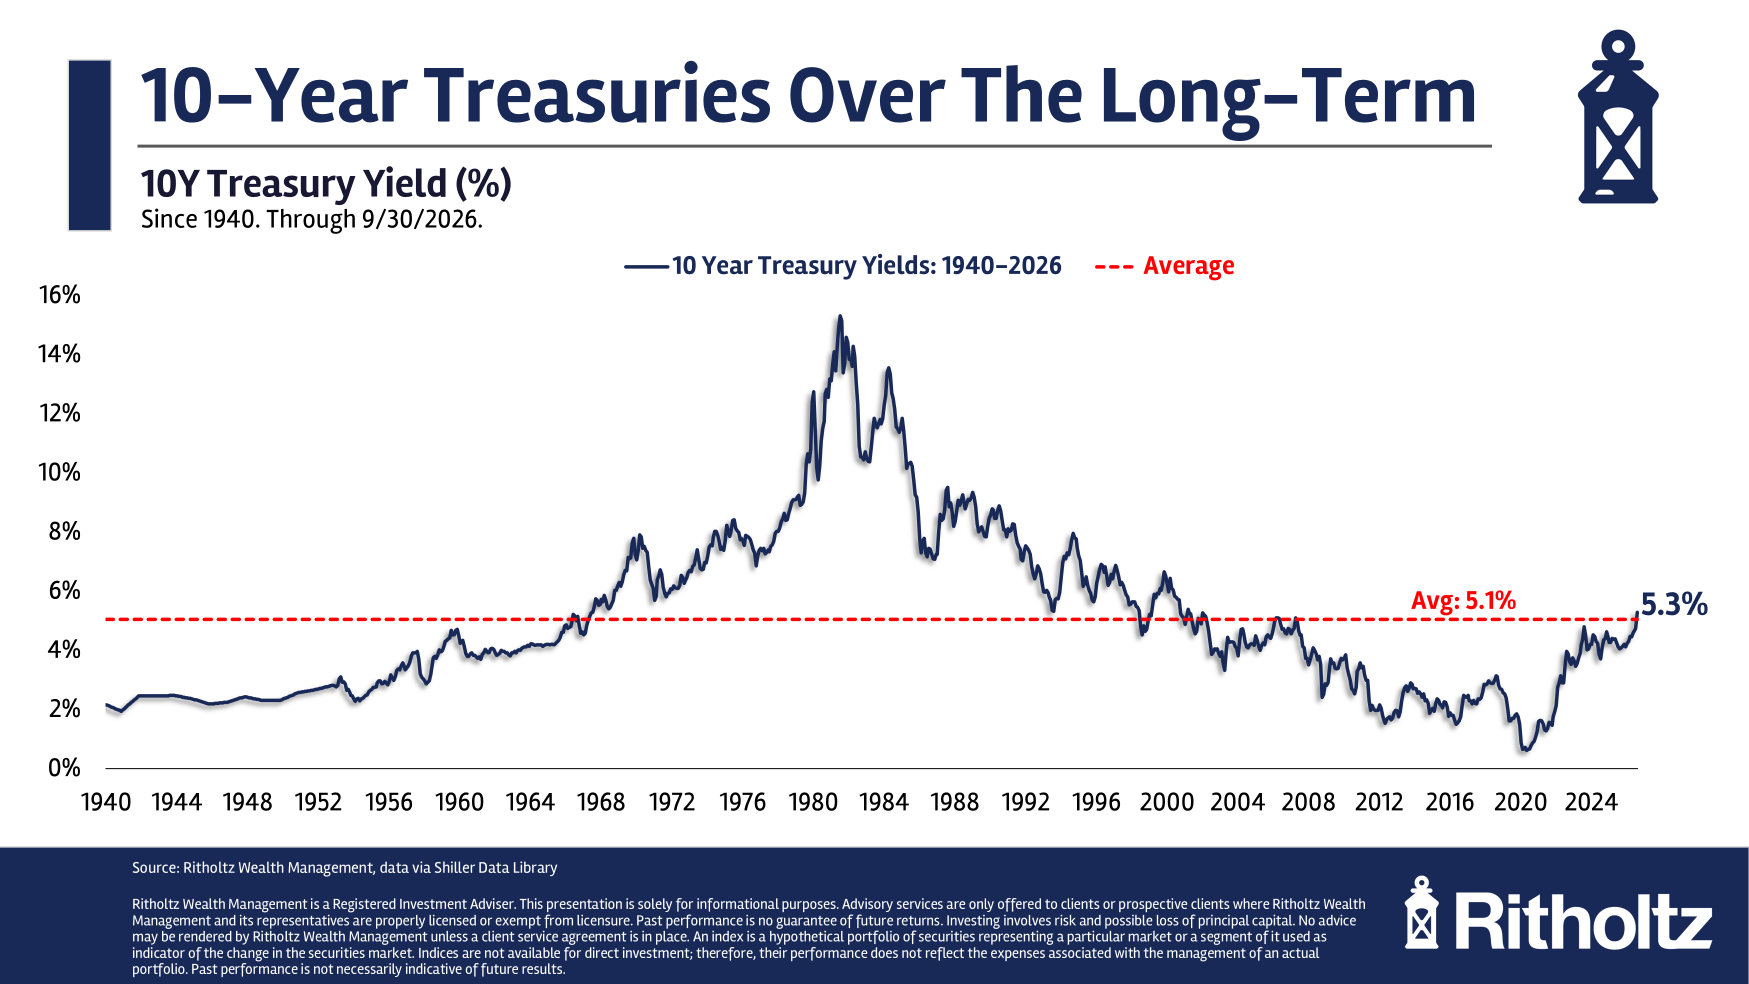
- Fixed-income yields across the 10-year U.S. Treasury have historically fluctuated well outside traditional definitions of a permanent “normal” rate.
- Ultra-low interest rate periods remove safety margins, exposing housing and credit markets to severe shocks when monetary policy changes.
- Housing market activity remains depressed as homeowners locked into low mortgage rates refuse to sell, restricting inventory despite population growth.
Historical Volatility in U.S. Treasury Yields
Market observers frequently search for a baseline normal interest rate, yet historical data reveals that a standard rate is virtually nonexistent. Government intervention during World War II suppressed bond yields to manage war financing, while inflation drove yields upward from the 1950s through the early 1980s.
Subsequent decades brought structural disinflation and declining yields, culminating in pandemic-era monetary easing. Bond yields averaged more than 10% through the 1980s while equity markets expanded, demonstrating that high yields do not preclude strong asset performance during economic booms.
| Economic Era | Average 10-Year Treasury Yield | Housing & Market Conditions |
|---|---|---|
| 1980s | More than 10% | Elevated mortgage rates; equity market expansion. |
| 2010s (ZIRP) | Not specified | Suppressed borrowing costs; low yield environment for savers. |
| Present Decade | 4% to 5% range | Elevated borrowing costs paired with robust equity market returns. |
Housing Market Activity and the Lock-In Effect
The rapid transition from multi-decade lows to an environment featuring 7.5% 30-year fixed mortgage rates has severely disrupted residential real estate transactions. In 2000, the U.S. recorded more than 5 million existing home sales annually with a population of 280 million.
Today, with a population exceeding 340 million and 135 million households, annual existing home sales are just shy of 4 million. Existing home sales have remained below the bottom of the housing bust for three years.
This stagnation stems directly from homeowners holding 3% mortgages who refuse to relinquish favorable financing terms. Because residential real estate accounts for roughly 20% of broader economic activity, compressed transaction volumes act as a persistent drag on macroeconomic growth.
Evaluating the Long-Term Impact of Monetary Extremes
Critics of zero-interest-rate policies in the 2010s predicted hyperinflation, currency crashes, and systemic financial failure. Those severe outcomes did not materialize, largely because behemoth tech companies generated actual profits to offset the prior decade’s sluggish equity returns.
Yet the primary damage of prolonged monetary accommodation lies in the absence of a safety margin when central banks eventually reverse course. Policymakers failed to anticipate the friction generated by pivoting rapidly from multi-year monetary easing to aggressive tightening without accounting for structural consumer dependencies.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute financial advice.
