
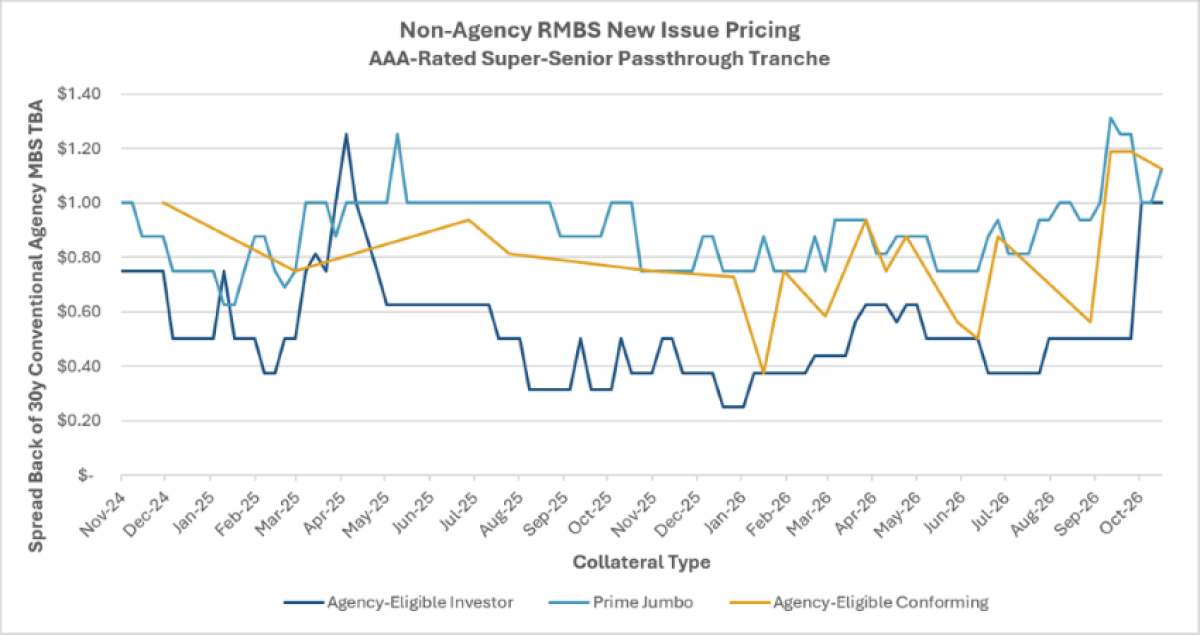
Non-agency residential mortgage-backed securities (RMBS) are increasingly capturing agency-eligible collateral, with issuance projected to reach $20 billion in 2026. This shift, driven by favorable pricing compared to government-sponsored enterprise (GSE) fees, offers institutional investors a mechanism to capture additional spread by assuming credit and liquidity risks typically absent in agency markets.
Strategic Financial Implications
- Pricing Arbitrage: Lenders are bypassing Fannie Mae and Freddie Mac when non-agency execution—net of loan-level price adjustments (LLPAs)—offers superior economics for specific loan profiles.
- Credit Risk Exposure: Unlike agency MBS, which carry explicit or implicit U.S. government guarantees, non-agency RMBS forces investors to price in the underlying credit quality of the mortgage pool.
- Diversification Tactics: By building non-agency platforms, originators are actively reducing their reliance on volatile GSE guarantee fees (g-fees).
Market Forces Driving Non-Agency RMBS Growth
The U.S. residential mortgage market holds roughly $14 trillion in debt. While the vast majority remains within the agency ecosystem—guaranteed by Ginnie Mae, Fannie Mae, or Freddie Mac—a distinct segment of the market is migrating toward non-agency securitization. Bloomberg noted in a recent assessment that while the non-agency RMBS market was once reserved for non-qualified mortgages (non-QM), it is now absorbing high-quality, agency-eligible collateral at an accelerating pace.
The numbers illustrate a clear trend: non-agency issuance of agency-eligible collateral hit $6.4 billion in 2024, doubled to $12.8 billion in 2025, and is on track to approach $20 billion by the end of 2026. This migration is not merely coincidental; it is a calculated response to the rising cost of GSE participation. As g-fees fluctuate due to policy adjustments, originators are finding that establishing internal non-agency platforms provides a more stable, diversified funding source.
Real Estate Investment Trusts Retain Subordinate Bonds
The institutional market includes several frequent issuers that are real estate investment trusts (REITs). These entities frequently act as issuers, selling the senior, higher-rated tranches of their securitizations to external investors while retaining the subordinate bonds. This structure allows REITs to take on debt to buy residential mortgage credit, effectively positioning themselves to capture the additional spread that non-agency assets provide over their agency counterparts.
For the broader market, this means that the line between “safe” government-backed debt and private-label mortgage credit is blurring. Investors who traditionally relied on the liquidity and safety of agency MBS are increasingly evaluating the relative-value opportunities within non-agency pools. However, this transition requires a sophisticated approach to liquidity risk, as the non-agency market lacks the depth and standardized liquidity profile of the agency MBS market.
| Metric | Agency MBS Market | Non-Agency RMBS Market |
|---|---|---|
| Government Guarantee | Yes (Implicit/Explicit) | No |
| Market Size | ~$9.3 Trillion | >$800 Billion |
| Primary Driver | GSE Liquidity | Relative Value/Spread |
| Collateral Type | Conforming Loans | Non-QM & Agency-Eligible |
Institutional Investors Capture Additional Spread Relative to Agency MBS
The migration of agency-eligible loans into private wrappers reflects a tightening of the cost-benefit analysis regarding government-guaranteed financing. U.S. households carry approximately $14 trillion of residential mortgage debt, and the non-agency residential mortgage-backed securities market has surpassed $800 billion in size, offering institutional investors opportunities to capture additional spread relative to agency MBS.
Market observers note that this trend is not without risk. Bloomberg has previously highlighted how shifts in mortgage securitization can impact the secondary market’s liquidity. For institutional investors, the primary question remains whether the additional spread captured in non-agency RMBS adequately compensates for the inherent liquidity constraints of private-label securities.
The Urban Institute’s Housing Finance at a Glance data suggests that while the agency channel remains the backbone of the U.S. housing market, the non-agency sector is a faster-growing source of financing.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute financial advice.
