
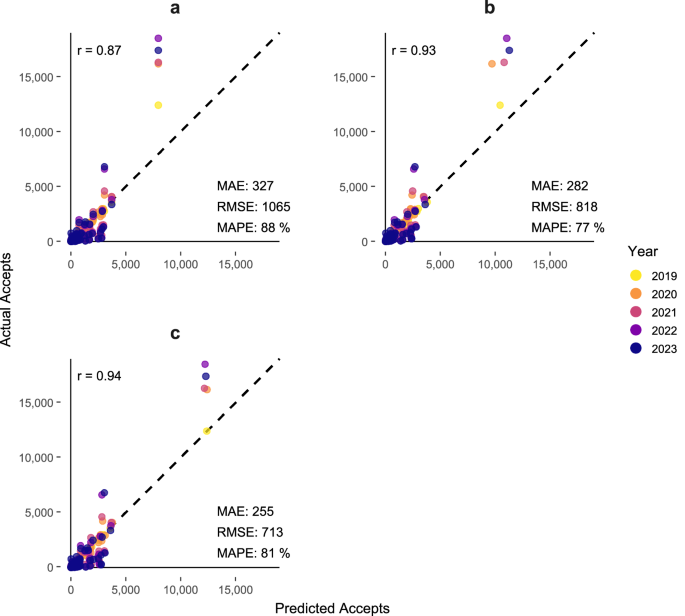
Recent machine learning administrative forecasts reveal a concentration paradox in international student mobility, showing that applications to the United Kingdom from China, Hong Kong, India, and the European Union will comprise over 60% of international demand by 2030, even as absolute numbers from these blocs stagnate or decline.
International student mobility underpins the financial resilience, soft power, and knowledge production of major destination countries like the United Kingdom, the United States, and Australia. Yet, the long-term trajectory of these academic flows is growing increasingly uncertain. Recent policy shifts and geopolitical tensions have coincided with a measurable slowdown in international student growth, sparking mounting concerns over sectoral stability across British campuses.
Forecasting Through Structural Shocks With Machine Learning
To understand where these academic pipelines are heading, researchers turned to advanced administrative data. Using records from the Universities and Colleges Admissions Service (UCAS) covering successful undergraduate applications from 86 origin countries between 2010 and 2024, analysts linked economic and demographic projections to forecast international applications through to 2030.
This predictive architecture covered an out-of-sample period spanning major structural disruptions like Brexit and the COVID-19 pandemic. The machine learning model delivered consistently lower forecast errors and stronger correspondence with observed flows than traditional benchmarks. But here is the catch: these predictive gains remain modest when structural economic and political shocks occur.
Decoding the Concentration Paradox in Higher Education
The forecasts point toward a counterintuitive structural reality that researchers term a concentration paradox. Even as overall inflows soften and absolute application numbers from key regions plateau or drop, higher education systems will become heavily reliant on a narrowing set of origins.
By 2030, demand is heavily consolidated. Applications originating from mainland China, Hong Kong, India, and the European Union will together make up more than 60% of total international demand. But this deepening reliance carries a heavy hidden cost for institutional planners.
| Metric / Variable | Detail / Scope |
|---|---|
| Data Source | UCAS administrative undergraduate application records (2010–2024) |
| Geographic Scope | 86 origin countries linked with economic and demographic projections |
| Forecasting Model | Poisson-based XGBoost benchmarked against ARIMA and negative binomial gravity models |
| Consolidated Demand Share | Over 60% originating from China, Hong Kong, India, and the European Union by 2030 |
Concentrating student recruitment in just a handful of corridors leaves universities deeply exposed. When an education sector relies on a narrow pool of source countries, it inherits the macroeconomic vulnerabilities, currency fluctuations, and sudden visa policy shifts of those specific jurisdictions.
Navigating Global Volatility on University Balance Sheets
When those pipelines narrow or institutional stability wobbles under the weight of regulatory changes, the ripple effects touch everything from high-tech labor supplies to transnational research partnerships.
As universities look ahead to the end of the decade, administrators face a tough strategic choice. Spreading recruitment efforts across a more diverse global footprint is easier said than done when machine learning models show demand locking into familiar corridors. How institutions adapt to this tightening bottleneck will determine not just their own financial health, but the future shape of global knowledge exchange.
