
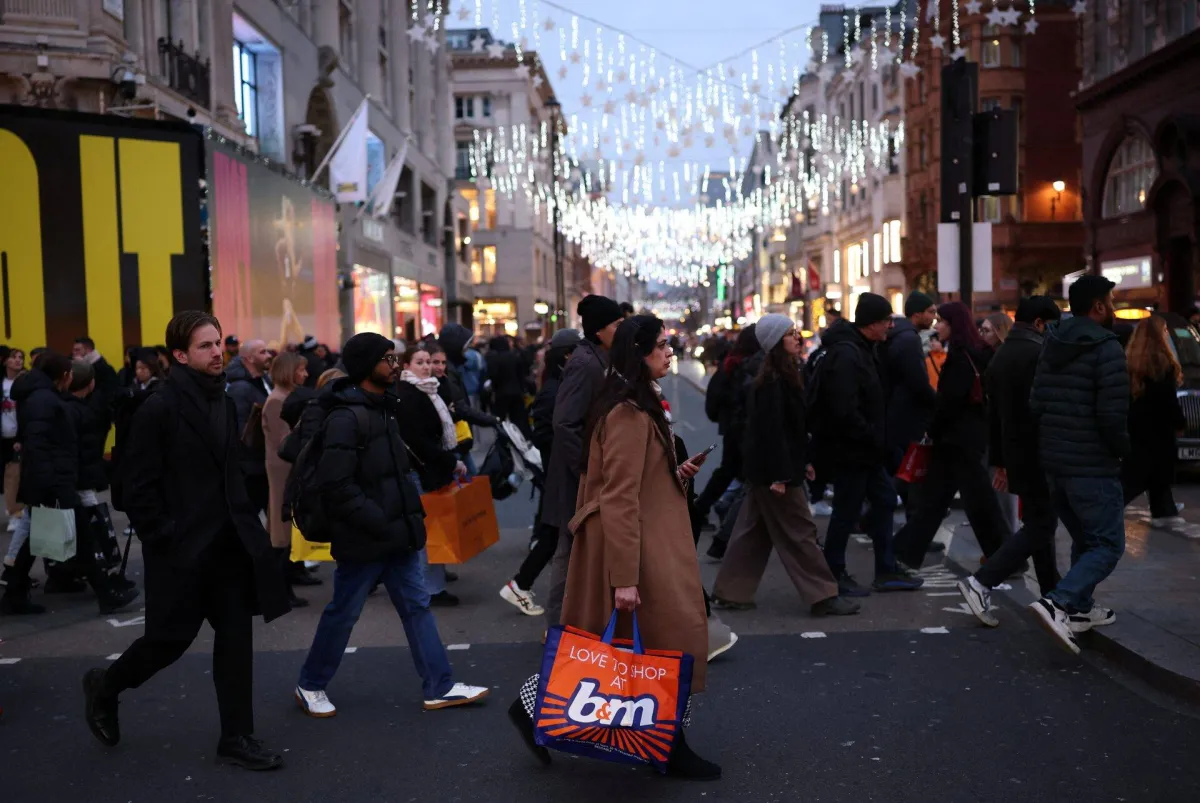
UK retail sales increased by a surprising 0.5% in August, defying economist expectations of a 0.2% decline and recovering from a 0.5% contraction in July. According to official data released by the Office for National Statistics, the uptick was driven by online channels, department stores, and food sales, even as soaring fuel prices driven by resumed conflict with Iran squeezed household budgets.
The Bottom Line
- Retail Volume Rebound: Total retail sales volume grew year-on-year in August, showing surprising resilience among British shoppers.
- Monetary Policy Stigma: Markets now price in a probability that the Bank of England will hike interest rates in November.
- Corporate Caution: Major high street names including Next (LON: NXT) and Primark (LON: ABF) report softer forward guidance, pointing to underlying consumer strain.
Dissecting the August Sales Surge
Market consensus ahead of the data release pointed toward consumer fatigue. Reuters polls of economists had predicted a 0.2% drop in sales volume for August, following July’s 0.5% decline. But the balance sheet tells a different story. Online platforms, major supermarkets, and apparel retailers posted gains that offset a 1.3% drop in fuel sales.
Here is the math: on an annual basis, total retail sales volume expanded. This contrasts with the weather-boosted spending sprees seen in June, which were heavily propped up by the men’s World Cup and warm summer conditions. Yet, beneath the headline consumer strength, the corporate landscape reveals a distinct split between macroeconomic resilience and high street realities.
Corporate Reality Check vs. Macro Data
While macro data points to active consumer spending, individual corporate updates tell a much more cautious story. Budget fashion chain Primark reported flat baseline sales growth in the UK for its fourth quarter. Meanwhile, John Lewis Partnership announced widening losses for the first half of the year.
Compounding the sector’s unease, apparel retailer Next downgraded its sales growth projections for the upcoming months. Management cited mounting anxieties over the broader British economic outlook. High street names are bracing for potential tax hikes ahead of the new government’s upcoming budget on October 28, where Prime Minister Andy Burnham and Chancellor of the Exchequer John Healey face severe fiscal constraints.
The Inflationary Pivot and Bank of England Pressures
The unexpected sales strength arrives at a delicate time for monetary policymakers. On Thursday, the Bank of England held its benchmark interest rate at 3.75% (while other reporting, such as Investing.com, noted differing baseline interpretations of the rate level). However, the central bank signaled it may be forced to hike borrowing costs if energy-driven inflationary pressures persist.
The resumption of conflict with Iran has injected fresh volatility into energy markets, pushing fuel prices higher. The Bank of England’s updated projections indicate inflation could breach 4% in early next year. Consequently, major institutional desks have adjusted their monetary forecasts. Barclays (LON: BARC) anticipates a 25 basis point hike in November, citing a structural shift in medium-term energy price trajectories. JPMorgan Chase (NYSE: JPM) similarly projects rate hikes in November 2026 and February 2027, superseding previous expectations of an imminent easing cycle.
Market Reaction and Bond Yield Volatility
Foreign exchange and fixed-income markets responded swiftly to the converging pressures of resilient consumer data and hawkish central bank signals. The British pound ticked up to $1.337 against the US dollar, while remaining virtually unchanged against the euro at 85.91 pence.
Concurrently, UK government bond yields reacted to shifting expectations. 10-year gilt yields climbed back to 5.25% after absorbing the stronger-than-expected retail figures. Traders are now navigating a complex global tightening cycle, punctuated by the Bank of Japan lifting interest rates to a 31-year high.
Macroeconomic Indicators Snapshot
| Indicator | August 2026 Data | Previous Month / Consensus |
|---|---|---|
| Retail Sales (MoM) | +0.5% | Consensus: -0.2% | July: -0.5% |
| Retail Sales (YoY) | +2.4% | July (Revised): +0.7% |
| Bank of England Base Rate | (Held) | Hawkish forward guidance |
| GBP/USD Exchange Rate | $1.337 | Stable post-data release |
| 10-Year Gilt Yield | 5.25% | Rebound following prior dip |
Strategic Outlook for Q4
The resilience of the UK consumer in August offers a temporary buffer for corporate revenues, but it complicates the central bank’s path toward price stability. With terminal rate expectations shifting upward and geopolitical energy shocks threatening supply chains, corporate margins will remain under intense scrutiny as the market approaches the critical fourth-quarter trading period.
- Indonesia Settles 1997-1998 BLBI Debt Obligations Using Bank Indonesia Surplus
- Nationalising Chiltern Railways a significant milestone
- Bank of Japan Raises Interest Rates to Highest Level Since 1995 (world-today-journal.com)
- Bank of Japan Raises Interest Rates to 31-Year High Amid Inflation Risks (time.news)
