
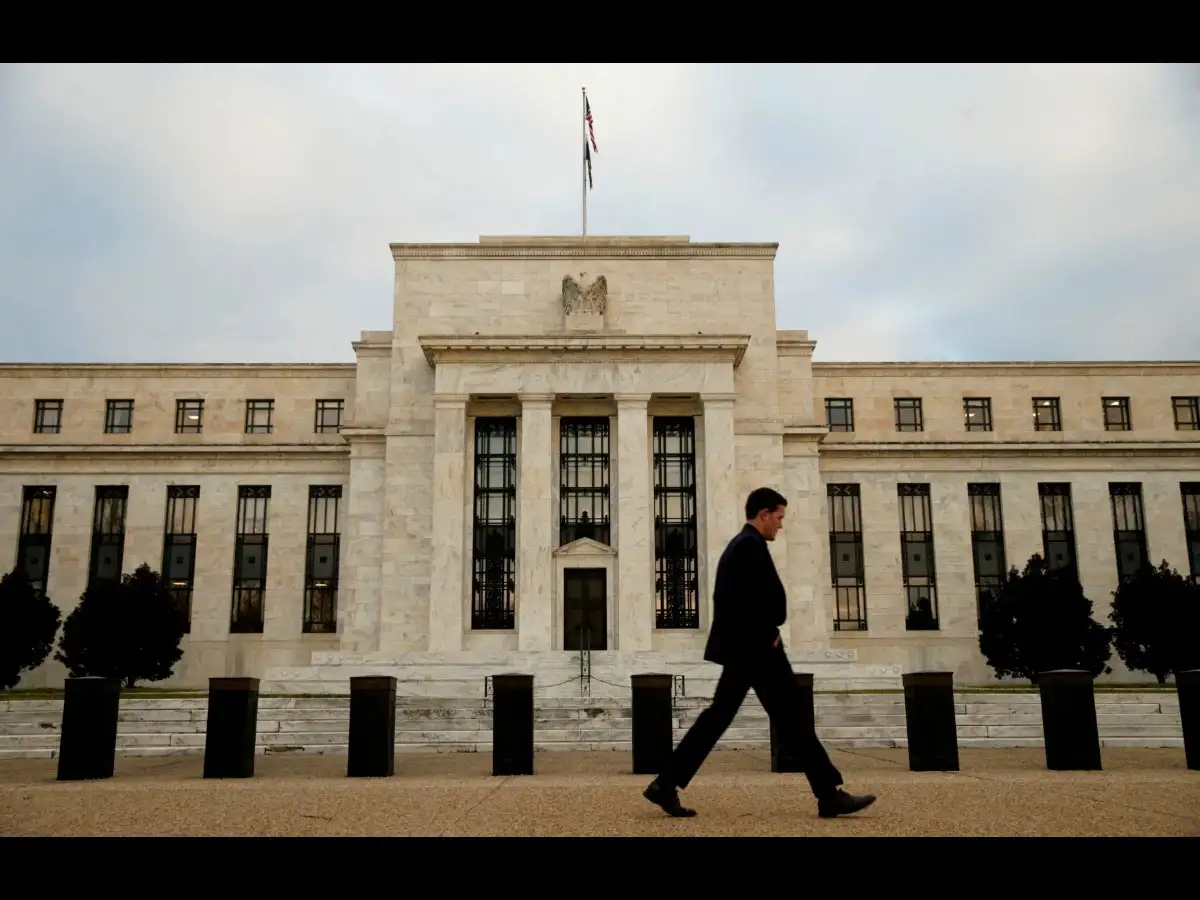
Federal Reserve Policy Divergence Following September Rate Increase
Federal Reserve Vice Chair Philip Jefferson and Minneapolis Fed President Neel Kashkari have signaled conflicting approaches to future interest rate adjustments. While Jefferson advocates for a cautious, data-dependent pace following the September 15-16 rate increase to the 3.75%-4.00% range, Kashkari suggests that further hikes may be necessary to curb persistent inflation.
The Bottom Line: Strategic Implications for Investors
- Data Dependency vs. Restrictive Policy: The Fed remains in a holding pattern for the October 27-28 meeting as leadership weighs the impact of rising bond yields against an unexpectedly resilient labor market.
- Inflationary Upside Risks: Despite long-term targets, officials remain concerned that geopolitical shocks and robust aggregate demand could prevent inflation from returning to the 2% goal.
- Market Stability: Despite the volatility associated with rapid shifts in borrowing costs, the Treasury market has successfully absorbed recent repricing, with no immediate signs of systemic risk in the banking sector.
Jefferson’s Call for Measured Observation
Speaking at the University of Virginia’s Darden School of Business, Vice Chair Philip Jefferson stated that he sees no immediate urgency to move rates again. As reported by Reuters, Jefferson emphasized that any future policy adjustments must be determined by a careful examination of emerging data trends and the evolving balance of risks.
The Fed raised its benchmark rate by 25 basis points last month, a move Jefferson supported. However, he noted that with financial markets currently reassessing the economic outlook, policymakers require additional time to discern the appropriate stance. Jefferson explicitly identified risks to his inflation forecast as “tilted to the upside,” citing recent geopolitical developments and stronger-than-anticipated aggregate demand as primary drivers.
Kashkari’s Outlook on Sustained Tightening
Minneapolis Fed President Neel Kashkari offered a more hawkish perspective, indicating that additional rate increases will likely be required through 2027 to effectively restrain economic activity. While Kashkari expressed uncertainty regarding whether a hike is required at the upcoming October meeting, he maintained that the current policy may not be sufficiently restrictive.
“The labour market looks quite healthy right now. It seems like the economy is doing quite well,” Kashkari stated. He noted that if the economy continues to display such resilience, policy might need to move higher than currently anticipated. Kashkari, who voted for the September hike, noted that he is monitoring the banking sector closely due to the rapid shift in borrowing costs, though he currently observes no systemic threats.
Comparative Projections for 2026 Policy
| Official | Stance on October Meeting | View on Future Hikes |
|---|---|---|
| Philip Jefferson | Urges patience; no urgency to act. | Data-dependent; risks tilted to upside. |
| Neel Kashkari | Open-minded; no strong view. | Expects one more hike in 2026, plus 2027. |
| New York Fed President John Williams | Expects time to assess data. | Anticipates one more increase by year-end. |
Market Dynamics Reflect Real Economic Developments and Market Perception
Kashkari noted that the movement in long-term rates reflects both real economic developments and a clear market perception that the current leadership is committed to controlling inflation. As financial markets have broadly priced in a pause for the Fed’s October 27-28 meeting, the focus of the central bank remains on the final meeting of the year, scheduled for December 8-9, where policymakers will reconcile the resilience of the labor market with the mandate to return inflation to the 2% target.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute financial advice.
