
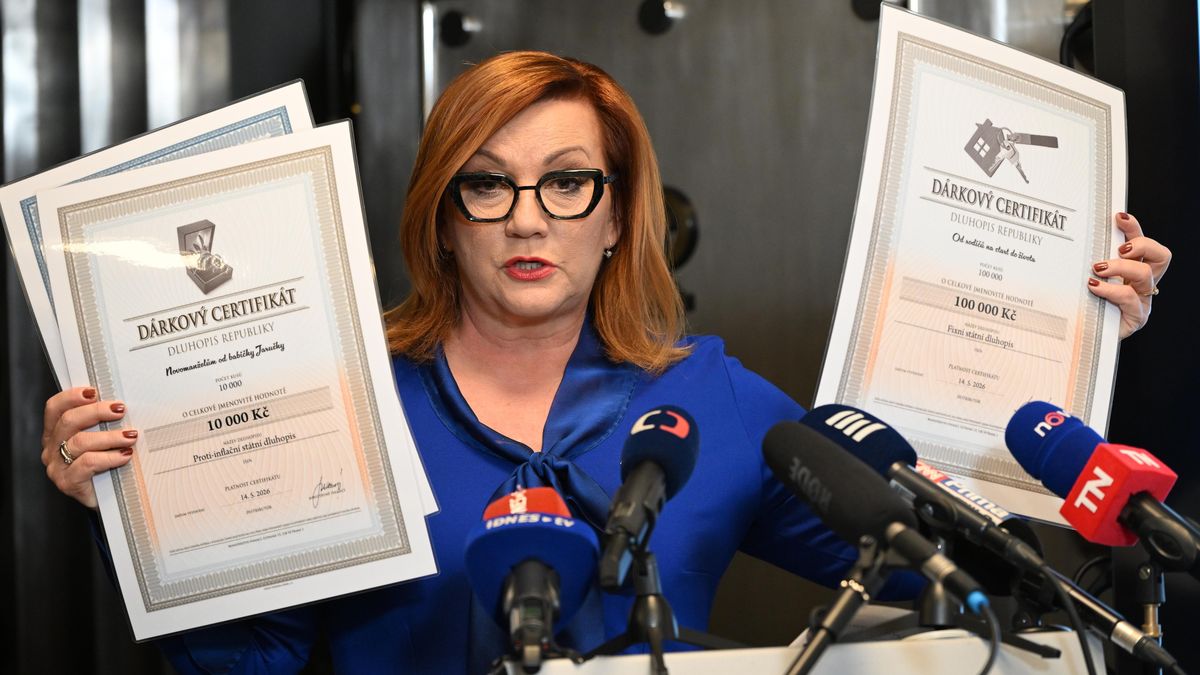
The Czech Republic has secured substantial funds from citizens this year through state bond issuances, driven by strong reinvestment into short-term Flexi Bonds. According to data reported by the Ministry of Finance, investors rolled over nearly all of their holdings from the initial summer offering into subsequent issues.
The Bottom Line
- Citizens purchased 27.6 billion korunas worth of three-month Flexi Bonds during the first offering period, retaining and reinvesting almost the entirety of those funds plus yields for the subsequent term.
- The second issuance offered a three-month maturity with an annualized yield of 3.75 percent, attracting 49,724 buyers with an average age of 57.2 years.
- Across all offerings to date, the Ministry of Finance has raised funds from retail investors, including 74 billion korunas secured through both the three-month and five-year tranches issued in the summer.
High Retention Rates in Summer Flexi Bond Tranches
Holders of the initial three-month Flexi Bonds purchased during the summer demonstrated near-total loyalty to the instrument, rolling their capital directly into the next period. Alena Schillerová highlighted this behavior as a clear metric of public satisfaction with the product’s parameters.
For the second issuance, investors have until January 11 to request a full cash payout of their principal and accumulated returns. Funds left untouched by that deadline undergo an automatic reinvestment into the third wave of Flexi Bonds. The Ministry of Finance stated it will announce the exact yield rate for this upcoming period in December.
Tax-Exempt Yields and Demographic Profiles
The second batch of state obligaties featured a 3.75 percent annual yield, bolstered by a full exemption from income tax. Ministry figures show the buyer base leans experienced, with the 49,724 participants registering an average age of 57.2 years.
The Ministry of Finance plans to open the subscription window for the third Flexi Bond emission in the pre-Christmas period. That upcoming round will reintroduce all three variations of the debt instruments previously offered to the retail market.
Historical Precedent and Prior Policy Shifts
Retail-targeted state debt is not entirely new to the Czech fiscal framework. The Ministry of Finance previously issued “Dluhopisy Republiky” between 2018 and 2021 during the government of Andrej Babiš, executing 13 subscription periods that raised a cumulative 80.1 billion korunas.
That retail issuance pipeline was subsequently halted by Zbyněk Stanjura, who held office from 2021 to 2025. Stanjura defended the suspension by arguing that retail bond programs generated higher servicing costs for the state compared to debt placed with institutional investors.
