
Europe faces a potential natural gas deficit of up to 15% during a cold winter, according to a warning issued by ENTSOG, the European Network of Transmission System Operators for Gas. This vulnerability stems from storage levels resting at 72% by October 1, down from 83% at the same point in 2025, setting up a high-stakes energy test as colder months arrive.
Here is why that matters right now: the European Union enters the heating season following what ENTSOG characterized as a challenging injection period. While Brussels has drastically reduced its historical reliance on Russian pipeline gas, the bloc still retains exposure through landlocked member states like Hungary and Slovakia.
The primary concern centers on a worst-case convergence. ENTSOG analyzed scenarios modeling a complete absence of Russian pipeline supplies alongside a potential disruption of major offshore infrastructure feeding continental Europe, paired with an unexpected total stop of pipeline imports from Algeria. That combination would severely pressure regional energy security.
Infrastructure Bottlenecks Threaten Southeast Europe
Vulnerability across the continent remains unevenly distributed. Western European nations benefit from modern liquefied natural gas (LNG) import terminals and steady pipeline flows, particularly from Norway. Central and eastern landlocked states face steeper obstacles due to domestic pipeline constraints that make quick rerouting difficult.
In the event of a harsh winter coupled with sudden supply route losses, pipeline bottlenecks could prevent Western terminal gas from reaching Eastern markets efficiently. ENTSOG projects that southeastern Europe could experience local supply shortfalls reaching 12% during peak demand days, testing cross-border solidarity mechanisms among EU capitals.
To mitigate the risk of competitive panic buying and subsequent price spikes, the European Commission has granted member states additional flexibility. Governments can target storage fill levels between 75% and 80% by November 1, stepping back from the traditional 90% benchmark. Even so, the market cushion remains thin.
Global LNG Competition Drives Price Volatility
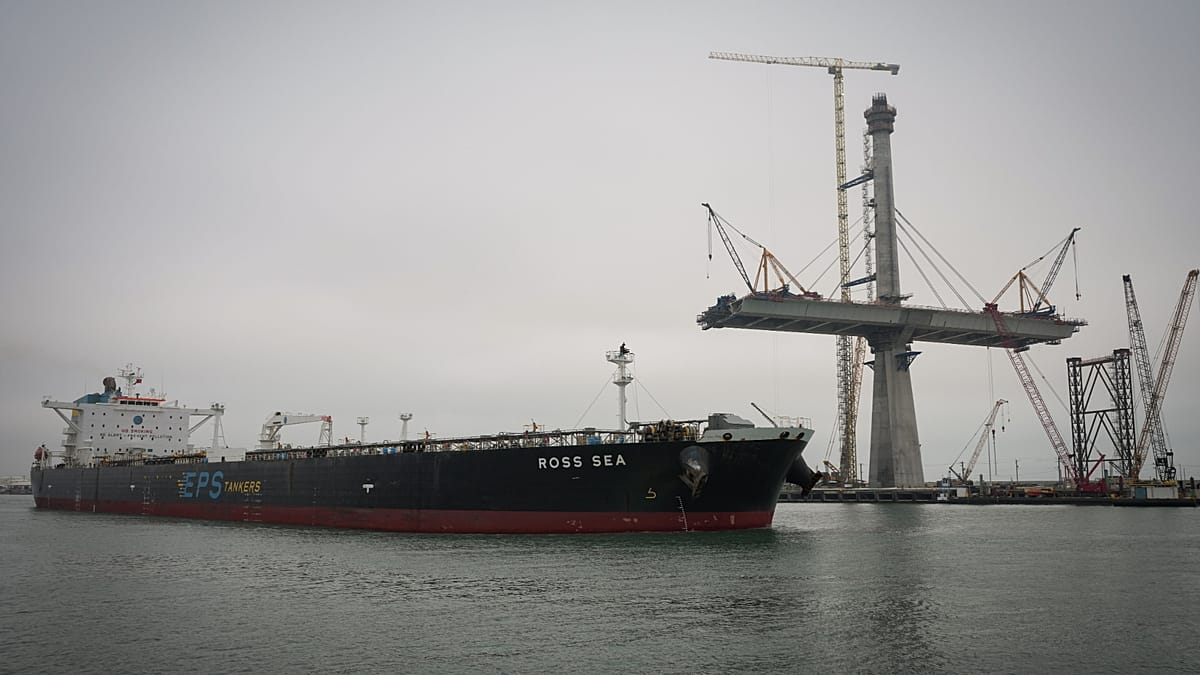
With pipeline routes diminished, Europe relies heavily on the global LNG marketplace to balance its energy ledger. The United States has stepped in as the primary LNG supplier to the bloc. Yet that reliance exposes European utilities and consumers directly to international price swings and fierce global bidding.
Adding to the maritime strain, trade restrictions in the Strait of Hormuz have curtailed exports originating from Qatar and the United Arab Emirates. Although direct European exposure to Qatari gas sits at roughly 8%, with Italy standing among the most exposed, tightening global supplies amplify the scramble for cargoes between Asian and European buyers.
Market reaction reflects this underlying tension. Trading on the Dutch Title Transfer Facility (TTF), Europe’s benchmark wholesale gas price, fluctuated between 79.80 and 80.22 euros per megawatt-hour. That figure marks nearly triple the price level recorded prior to the outbreak of the conflict involving the United States, Israel, and Iran.
| Indicator | Current Metric | Previous Comparison |
|---|---|---|
| EU Storage Level (Oct 1) | 72% | 83% (Oct 1, 2025) |
| Projected Peak Winter Deficit | Up to 15% (Cold Scenario) | Normal seasonal margins |
| Flexible Nov 1 Storage Target | 75% to 80% | 90% traditional target |
| TTF Dutch Gas Price Range | ~€79.80–€80.22 / MWh | Tripled since Middle East conflict escalation |
Under baseline weather conditions, continued tight LNG availability could pull European storage down to 13% by March 2027. Such depleted inventories would likely force energy-intensive industrial sectors to curtail manufacturing operations, while high retail costs pass through to households.
As the heating season progresses, European policymakers must balance inventory preservation against global market volatility, watching weather forecasts closely as import margins shrink.
Related reading
- EU Lawmakers Back Plans for Unified High-Speed Rail Network by 2040
- Why We Need Storytellers to Probe the Powerful and Protect Facts
- EU Watchdog Warns Debt Could Hit €1 Trillion by 2027 (archyworldys.com)
- Singapore Opposition Politician Lim Tean Faces New Charges Over Alleged Flight to Malaysia (archynewsy.com)
