
Maryland residents can begin comparing 2027 health insurance plans and prices online starting Wednesday, ahead of the state open enrollment window running from November 1 through January 15, 2027. Premium costs vary based on income, provider, household size, and age.
In Plain English: The Clinical Takeaway
- Dynamic Plan Verification: A health plan active in 2026 can alter its legal issuer, network, or drug coverage for 2027, requiring a complete renewal audit rather than automatic rollover.
- Income-Based Subsidies: State financial assistance programs reduce monthly health insurance premiums for eligible residents accessing coverage through the state exchange.
Marketplace Open Enrollment Dates and Income-Based Variances
Open enrollment for Maryland’s health insurance exchange begins November 1 through January 15, 2027, with preliminary comparisons available online starting Wednesday. Financial obligations scale with household demographics and chosen metal tiers. For instance, a 27-year-old resident in Baltimore City earning $25,000 annually faces no monthly premium for the lowest-cost silver plan, while the same individual earning $50,000 would pay a $187 monthly premium for the lowest cost gold plan. For a 40-year-old resident in Baltimore City with a $50,000 income, the lowest-cost silver plan requires a $1 monthly premium, whereas a low-cost gold plan costs $201 per month.
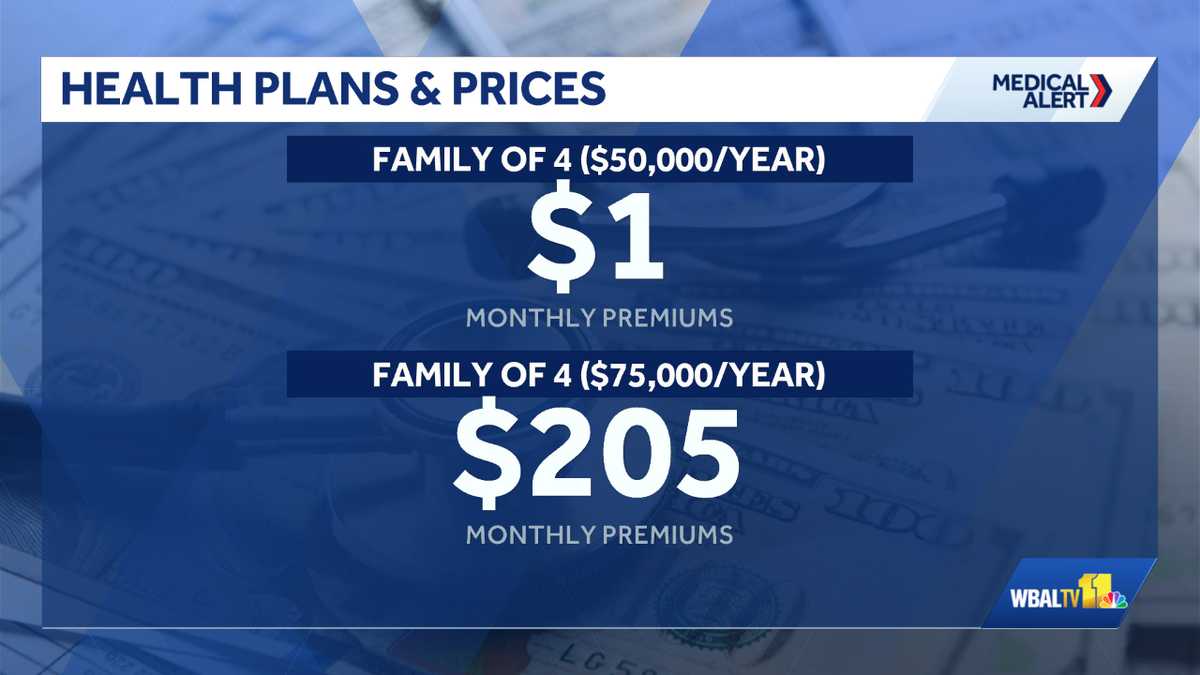
Household scale shifts these financial calculations further. A family of four in Baltimore City earning $50,000 annually pays $1 monthly for the lowest-cost silver plan. When that same household size reports an income of $75,000, the monthly premium for a low-cost gold plan rises to $201. The Maryland Premium Assistance Program provides state financial help to eligible residents purchasing coverage through the exchange, lowering monthly health insurance premiums based on household income.
Clinical and Administrative Considerations for 2027 Coverage
Marketplace planning requires a comprehensive renewal audit rather than carrying a 2026 name, network, premium, or benefit forward. Insurers can alter service areas, legal issuers, formularies, and provider participation between plan years.
Selecting healthcare coverage requires balancing net premiums against deductibles, services, drugs, and in-network limits. Administrative oversights—such as missing the official state marketplace route or deadline, or operating with outdated household and income facts—can block intended applications or alter subsidy eligibility.
| Demographic & Location | Household Income | Selected Plan Tier | Estimated Monthly Premium |
|---|---|---|---|
| 27-Year-Old (Baltimore City) | $25,000 | Lowest-Cost Silver | $0 |
| 27-Year-Old (Baltimore City) | $50,000 | Lowest-Cost Gold | $187 |
| 40-Year-Old (Baltimore City) | $50,000 | Lowest-Cost Silver | $1 |
| Family of Four (Baltimore City) | $50,000 | Lowest-Cost Silver | $1 |
| Family of Four (Baltimore City) | $75,000 | Lowest-Cost Gold | $201 |
Verify Enrollment Details to Prevent Care Gaps
Individuals experiencing disruptions in care continuity due to network changes should verify live plan, eligibility, and enrollment details with the responsible official source to prevent gaps in prescription access.
References
- Maryland health insurance plan cost comparisons and open enrollment schedule.
- 2027 Health Insurance Marketplace Planning and Plan Comparison Guidelines.
