
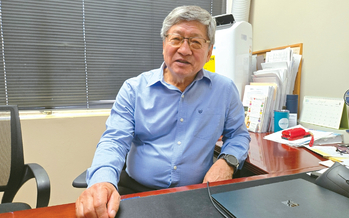
Goldwell Insurance has marked two decades of operations by prioritizing deep technical product literacy over high-pressure sales tactics. Led by CEO Richard Kim, the firm emphasizes training agents to master complex insurance mechanics. This approach underscores a broader shift in consumer finance toward specialized advisory expertise amid changing regulatory and economic conditions.
Here is the math: insurance distribution models relying purely on volume sales are facing increased friction as consumers demand sophisticated financial planning. But the balance sheet tells a different story for firms investing in continuous advisor education.
The Bottom Line
- Advisory Shift: Agencies focusing on comprehensive product education are outperforming traditional volume-driven sales models in client retention.
- Leadership Focus: Richard Kim’s 20-year operational strategy at Goldwell anchors long-term firm stability in continuous agent training rather than transactional quotas.
Decoding the 20-Year Operational Playbook
The traditional insurance brokerage model historically relied on aggressive acquisition metrics. Goldwell’s operational framework diverges from this norm. By centering its corporate philosophy on the premise that an agent who truly understands policy mechanics builds higher lifetime client value, the firm has sustained operations for two decades.
According to industry disclosures, the emphasis remains on rigorous internal training protocols. Agents are required to comprehend underlying risk structures before interacting with commercial or individual policyholders. This strategy reduces policy churn and mitigates errors in coverage selection.
| Strategic Metric | Traditional Sales Model | Goldwell Advisory Model |
|---|---|---|
| Primary KPI | Volume of policies sold | Technical comprehension & retention |
| Training Focus | Sales scripts & closing techniques | Risk mechanics & policy structure |
| Client Acquisition Cost | High due to constant turnover | Optimized via long-term retention |
Macroeconomic Headwinds and Brokerage Valuation
Insurance distribution does not operate in a vacuum. Broader financial services trends, including shifting interest rate environments tracked by the Federal Reserve and evolving compliance standards overseen by bodies like the Securities and Exchange Commission, dictate how independent agencies operate. When capital costs rise, policyholders scrutinize every line item on their commercial and personal balance sheets.
Financial analysts note that independent agencies lacking technical depth often struggle during economic transitions. Conversely, firms with deeply trained advisory staff maintain pricing power. Institutional investors tracking insurance brokerage networks—such as those monitored via financial data providers like Bloomberg—increasingly favor organizations that demonstrate low client attrition over those dependent on short-term sales spikes.
As market conditions evolve, the differentiation between selling a policy and structuring risk becomes starker. Firms maintaining rigorous internal education standards are better positioned to weather regulatory shifts and margin compression.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute financial advice.
