
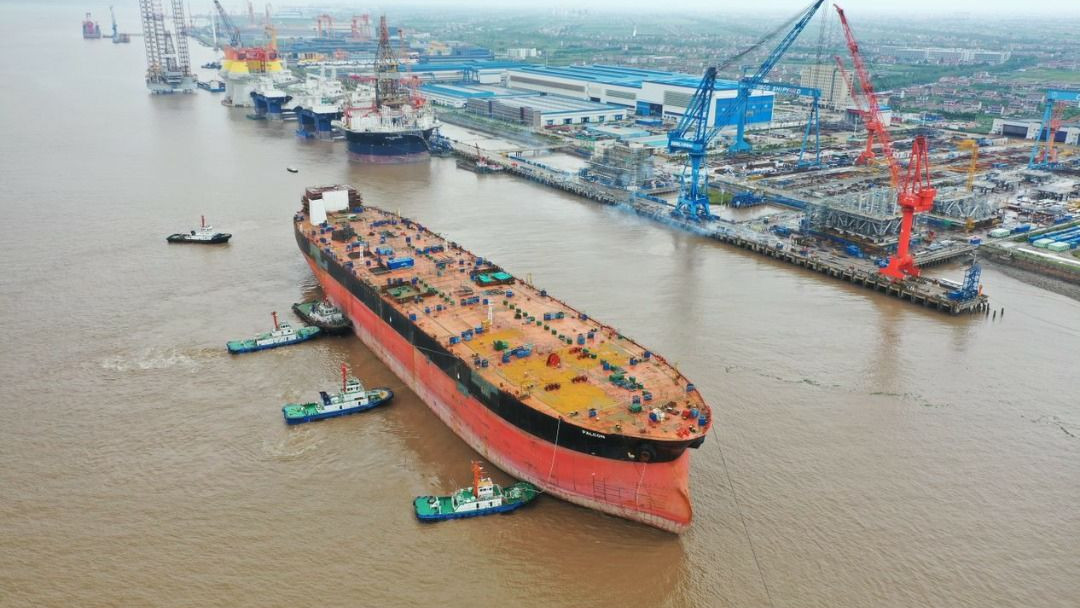
As soaring maritime transport costs rewrite global oil trade routes, producers are forced to slash export prices as delivered costs surpass what refiners are willing to absorb. According to Oilprice.com, ballooning freight expenses in the wake of Middle Eastern conflicts are decoupling benchmark crude values from actual landed prices, redirecting millions of barrels toward alternative buyers in India while leaving Asian refiners scrambling for predictable supply.
The Bottom Line
- Freight Surges: Very Large Crude Carrier (VLCC) spot rates from the Middle East Gulf to China climbed as high as $36 per barrel by early October, driving total landed costs past $130 per barrel.
- Pricing Pressures: State-backed producers like Saudi Arabian Oil Co. (Saudi Aramco, Tadawul: 2222) are cutting official selling prices and fixing future differentials to keep barrels moving.
- Trade Shifts: Refiners in India are rapidly increasing imports of Latin American and West African crude as transportation expenses make those routes more competitive than long-haul Middle Eastern supplies.
Tanker Rate Volatility Upends Middle Eastern Supply Chains
The pricing squeeze is most acute in the Middle East, where crude freight rates have surged in two distinct waves since military conflicts escalated in March. VLCC spot rates from the Gulf to China initially jumped from roughly $4 per barrel to $17 per barrel before easing between April and July, Oilprice.com reported. However, the expiration of the US-Iran ceasefire in August triggered a second steep ascent, pushing freight to $36 per barrel by early October and elevating landed costs in China to approximately $130 per barrel.

Alternative loading points have offered little structural relief. Houthi restrictions on Saudi cargoes transiting through the Bab el-Mandeb strait drove freight from Saudi Arabia’s Yanbu terminal to China up to $28/bbl by mid-October. Consequently, Saudi loadings at Yanbu have slowed as intensified attacks along the Red Sea coast divert operations back to the Gulf.
To maintain market share, Saudi Aramco has adjusted its pricing mechanisms. The company set its November Official Selling Price (OSP) for flagship Arab Light at a $5 per barrel discount to Oman/Dubai benchmarks, partially offsetting the steep cost of moving barrels outside the Strait of Hormuz. By fixing a differential for loading roughly two months forward, Aramco secures buyers while exposing its netback margins to future freight fluctuations.
Global Trade Redistribution Toward Latin America and West Africa
The maritime inflation has expanded far beyond the Middle East, altering trade flows across the Atlantic basin. By mid-October, freight from the Americas to Asia rose to more than $80 million, or about $40 a barrel, according to data, pushing landed prices up. Because Chinese buyers are targeting delivered prices closer to $130 per barrel, Brazilian export offers have slowed, prompting producers to pivot toward Indian refiners.
West African suppliers face identical pressures. While Djeno crude trades at a free-on-board (FOB) discount of roughly $10 per barrel to ICE Brent, freight from West Africa to Asia has also eased from record highs this week. This disparity has redirected cargoes away from traditional Chinese destinations toward India’s west coast, where import volumes from Angola are estimated to rise from 35,000 barrels per day in September to 315,000 barrels per day in October.
Meanwhile, the International Energy Agency (IEA) reported that these elevated transportation expenses pushed margins for Asian refiners processing medium sour crude into negative territory in September. According to EnergyNow, the resulting increase in delivered costs forced refiners to heavily reevaluate their crude slates, prioritizing short-haul voyages and purchasing spot cargoes only when delivery dates and final costs are verifiable.
| Origin Route | VLCC Freight Cost / Barrel (Peak) | Estimated Landed Cost in China |
|---|---|---|
| Middle East Gulf to China | ~$36 | > $130 |
| Yanbu, Saudi Arabia to China | ~$28/bbl | ~$140/bbl |
| Brazil (Tupi) to China | ~$40 a barrel | above $130/bbl |
| West Africa to China | Competitive with regional alternatives | Competitive with regional alternatives |
Demurrage and War-Risk Premiums Complicate Market Execution
Freight tallies alone fail to capture the full friction of transacting in current energy markets. Loading reliability has become a primary metric for Asian purchasing decisions. Ship-to-ship (STS) transfers outside the Strait of Hormuz face persistent delays driven by regional security incidents. Demurrage rates for vessels exiting the Gulf have soared—equivalent to roughly $0.50 per barrel for a fully laden VLCC for each day of delay.

Compounding these operational hurdles, war-risk insurance premiums have climbed, adding $4 to $5 per barrel to the average VLCC voyage. These severe loss vectors reinforce the comparative advantage of Latin American barrels, whose supply routes bypass restricted Middle Eastern waterways and avoid hurricane-prone US Gulf Coast loading schedules.
As transportation expenditures continue to command a historic share of total landed value, market participants must navigate an environment where physical delivery certainty often outweighs baseline commodity pricing.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute financial advice.
