
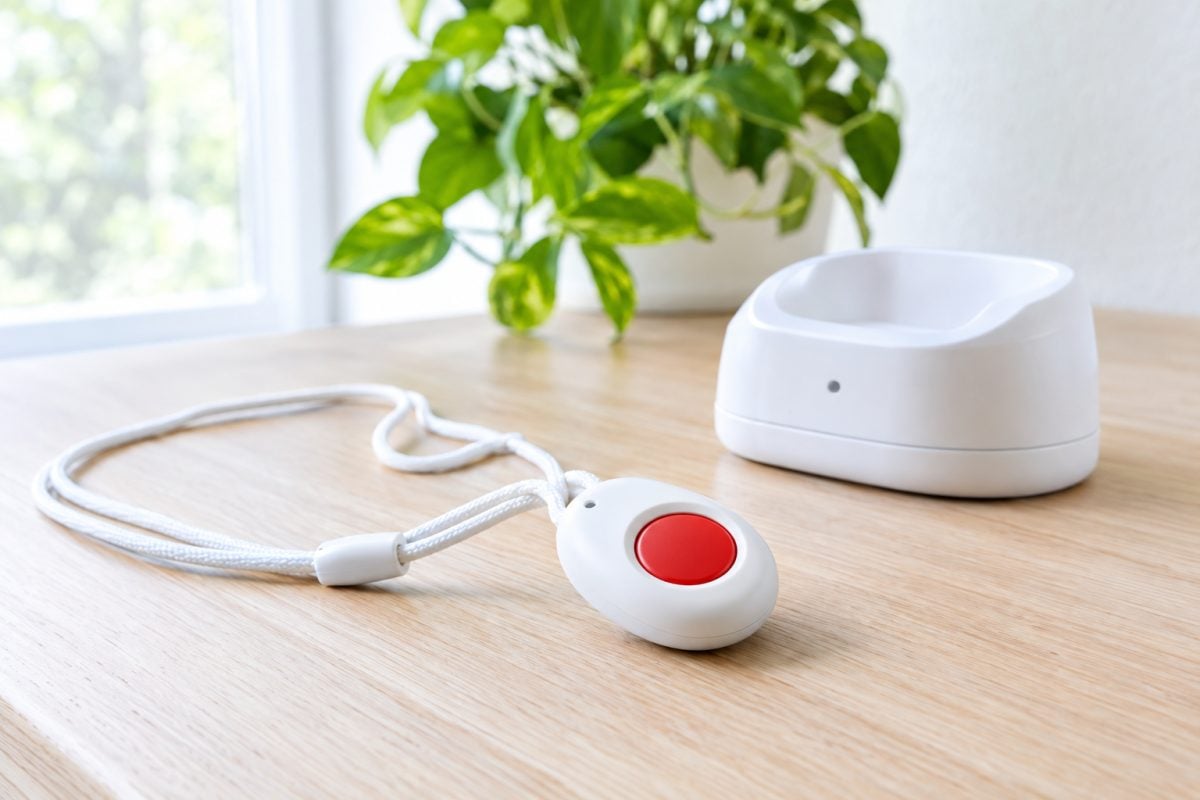
Deploying remote monitoring for an aging parent involves managing a tiered pricing structure ranging from 25 € to 50 € per month, which drops significantly to 12,50 € to 25 € after a tax credit, and can reach 0 € when integrated into the APA (Allocation Personnalisée d'Autonomie) funding scheme.
The Bottom Line
- Net Cost Breakdown: Basic necklace or bracelet buttons cost 25 € to 30 € monthly, halving to 12,50 € to 15 € after applying the French personal services tax credit.
- Advanced Tech Margins: Fall-detection pendants (35 € to 45 €) and multi-room movement sensors (30 € to 50 €) carry higher gross subscriptions, reducing to 17,50 € to 22,50 € and 15 € to 25 € net, respectively.
- Zero-Cost Integration: Families can eliminate the out-of-pocket expense entirely by incorporating the subscription into an official APA home-help plan managed by the local department.
Decoding the Monthly Subscription Matrix
Evaluating remote assistance solutions requires looking past the base marketing rates. The market range spans from 25 € to 50 € per month, with a basic call button sitting at the floor of that bracket. Crucially, the underlying listening service remains identical regardless of the hardware package chosen.
| Equipment Type | Gross Monthly Price | Net Cost After Tax Credit | Detection Mechanics |
|---|---|---|---|
| Call button necklace or bracelet | 25 to 30 € | 12.50 to 15 € | Manual activation by the user |
| Fall-detection pendant | 35 to 45 € | 17.50 to 22.50 € | Automatic trigger during incapacitation |
| Room movement sensors | 30 to 50 € | 15 to 25 € | Abnormal inactivity tracking without manual trigger |
| GPS tracking option | Additional fee | The half of the added cost | Real-time outdoor location mapping |
Subscribing to a standard 30 € monthly plan accumulates to 360 € annually. But the balance sheet tells a different story once statutory relief mechanisms are applied to household expenses.
Using the Personal Services Tax Credit
Remote assistance qualifies legally as a personal service, placing it in the same regulatory category as professional housekeeping. Consequently, it unlocks a tax credit, provided the chosen provider maintains official personal services accreditation.
The distinction between a tax reduction and a tax credit matters for fixed-income retirees. A tax reduction merely offsets existing liability and vanishes when tax liability reaches zero. Conversely, a tax credit triggers a direct cash disbursement to the household even if no income tax is owed.
Without proper accreditation, the financial advantage disappears entirely, doubling the actual cost of the service. Households must verify this paperwork before signing, retain the annual fiscal statement provided by the operator, and declare the expenditure under personal services.
Eliminating the Remaining Balance Through the APA
For individuals aged 60 and older experiencing declining autonomy, regional departments finance a portion of home-care support. A designated medical-social team conducts an assessment to establish a formal aid plan detailing covered services.
Remote assistance can be embedded into this plan, but families must explicitly request its inclusion during the evaluation phase. Numerous departmental councils, alongside local municipalities and retirement funds, finance remote assistance for modest-income households based on internal income thresholds.
However, strict aggregation rules apply. The portion of the bill covered by the APA or departmental aid cannot be claimed under the personal services tax credit. The tax credit applies strictly to the out-of-pocket residual amount paid directly by the household.
Hidden Overhead Costs Before Contract Execution
Operational expenses frequently extend beyond the monthly subscription fee. Providers routinely bill upfront equipment installation charges alongside hardware security deposits.
These line items often escape initial price disclosures.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute financial advice.
